


Genco Shipping & Trading has delivered a powerful share price run in recent years, which naturally puts the focus on whether the current tag still lines up with what its earnings can support. With that kind of backdrop, the question is how much of the past gains already reflect the profit power of the business today.
- Over the past 3 years the stock has returned 131.0%, which puts real pressure on the earnings story to justify how far the market has already moved.
- Recent earnings news highlighted strong charter rates and higher adjusted EBITDA, which can influence how investors think about the sustainability and timing of future profits that underpin any earnings based valuation.
- Your read on Genco Shipping & Trading is one view; the desks covering it have another. See what analysts think Genco Shipping & Trading's shares could be worth.
The issue now is whether Genco Shipping & Trading's current share price fairly reflects what its earnings suggest the business is worth.
To stress test whether Genco Shipping & Trading's 131.0% three year return is exceptional or just part of a wider pattern in similar businesses, compare it with: 29 high quality undervalued stocks
Has Genco Shipping & Trading Run Too Far on Earnings?
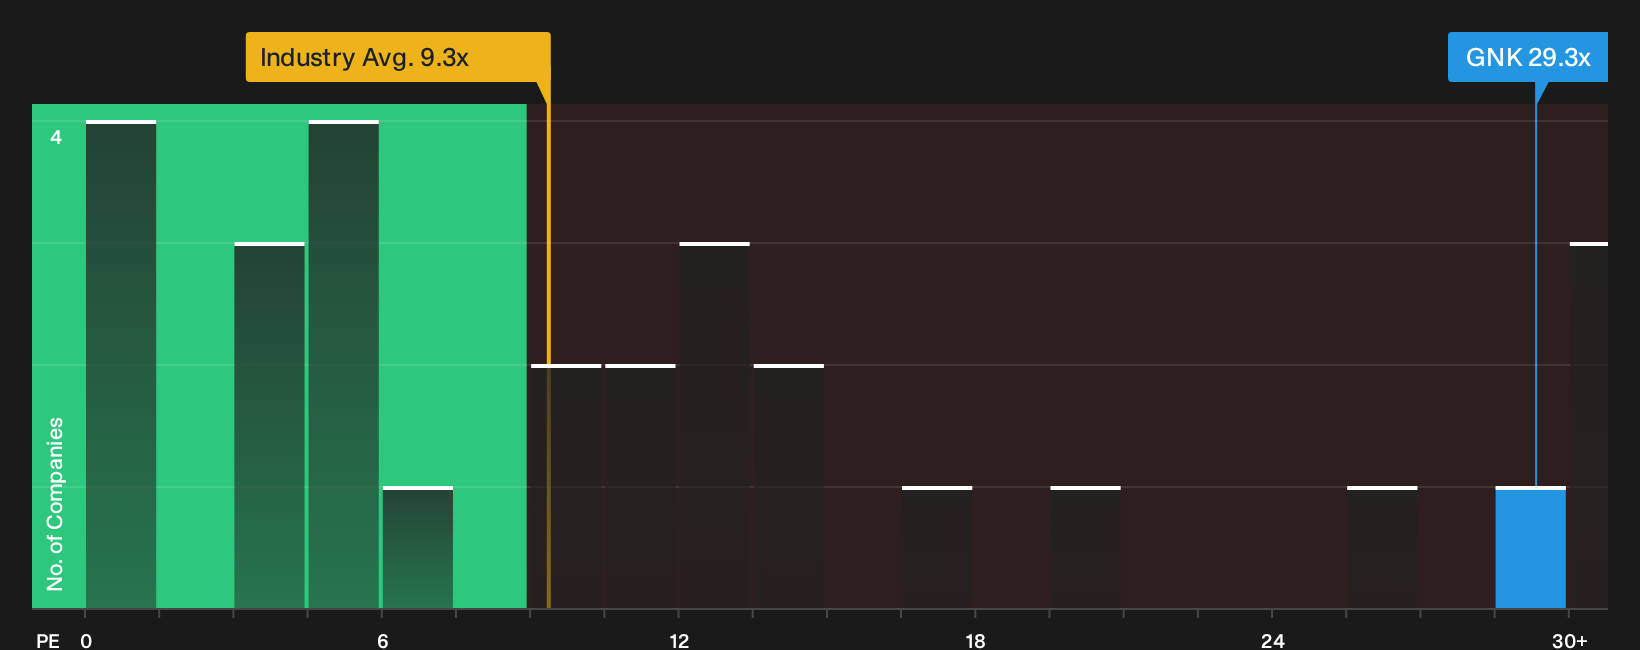
The P/E ratio is an appropriate metric for Genco Shipping & Trading because earnings remain the core yardstick investors watch for a shipping operator with meaningful charter exposure. On this measure, the stock trades on about 29.3x earnings, while the wider shipping industry sits closer to 9.3x and the immediate peer group averages roughly 8.7x. That represents a sizable premium to both the sector and similar businesses.
The internal fair multiple model, which blends factors such as profitability profile, risk and size, points to a lower P/E than where Genco Shipping & Trading trades today, so the shares appear overvalued on this framework. Because recent Q2 2026 numbers showed strong time charter equivalent rates and adjusted EBITDA, the current valuation looks heavily influenced by upbeat conditions already reflected in the price, rather than leaving a clear margin of safety. Explore the numbers behind Genco Shipping & Trading's P/E valuation.
The Genco Shipping & Trading Narrative: What Would Justify Today's Price?
Genco Shipping & Trading's valuation puzzle only really comes into focus once you spell out what future path for growth, margins and earnings would need to hold for the current price to look cheap or expensive, which is exactly what Simply Wall St's Narratives on the Community page aim to map. Where a single ratio or valuation model throws up one number, these scenarios unpack the future business conditions that number quietly relies on so you can watch in real time whether the story lines up with what actually happens.
Community views on Genco Shipping & Trading split between those who see more upside in the Capesize story and those who are more cautious on earnings quality and valuation.
Bull case: 8% undervalued
"Net dry bulk fleet growth of 3.9% in the first half of 2026, with only 1% growth for Capesizes and an aging global fleet..."
Discover why this Narrative puts Genco Shipping & Trading at 8% undervalued.
Bear case: roughly fairly valued
"Third party analysis that Genco Shipping & Trading’s shares trade 42% to 50% above some intrinsic value estimates, combined with US$5.5 million of insider selling..."
Explore why this Narrative puts Genco Shipping & Trading at roughly fairly valued.
The unanswered piece for Genco Shipping & Trading
Everything hinges on how the profit picture evolves over the next few years. Analyst projections offer a separate lens to compare with today’s multiples and recent news. Explore where analysts expect Genco Shipping & Trading to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com