


- Vertex Pharmaceuticals has seen consensus EPS estimates for its upcoming report revised down by 4.5% over the past month to $4.86, even as the business continues to report solid revenue and margin performance from cystic fibrosis therapies and newer products.
- The combination of lower earnings projections and what analysts describe as a premium valuation relative to biotech peers highlights pressure on Vertex Pharmaceuticals to convert its expanding late stage pipeline into future cash flows without eroding profitability.
- This analysis will consider how Vertex Pharmaceuticals' investment narrative holds up as recent EPS estimate cuts begin to challenge confidence in execution.
Vertex Pharmaceuticals Investment Narrative Recap
To own Vertex Pharmaceuticals, you need to believe its cystic fibrosis engine can stay resilient long enough for newer areas like sickle cell, acute pain, renal disease and endocrinology to matter more. The recent 4.5% trim to the next EPS estimate nudges expectations lower, but does not change those core building blocks.
The key near term swing factor is execution on launches such as CASGEVY, JOURNAVX and ALYFTREK while keeping CF pricing pressure in check, especially outside the US. The biggest risk remains that CF volume or pricing weakens faster than diversification ramps, which would make sustaining current profitability harder.
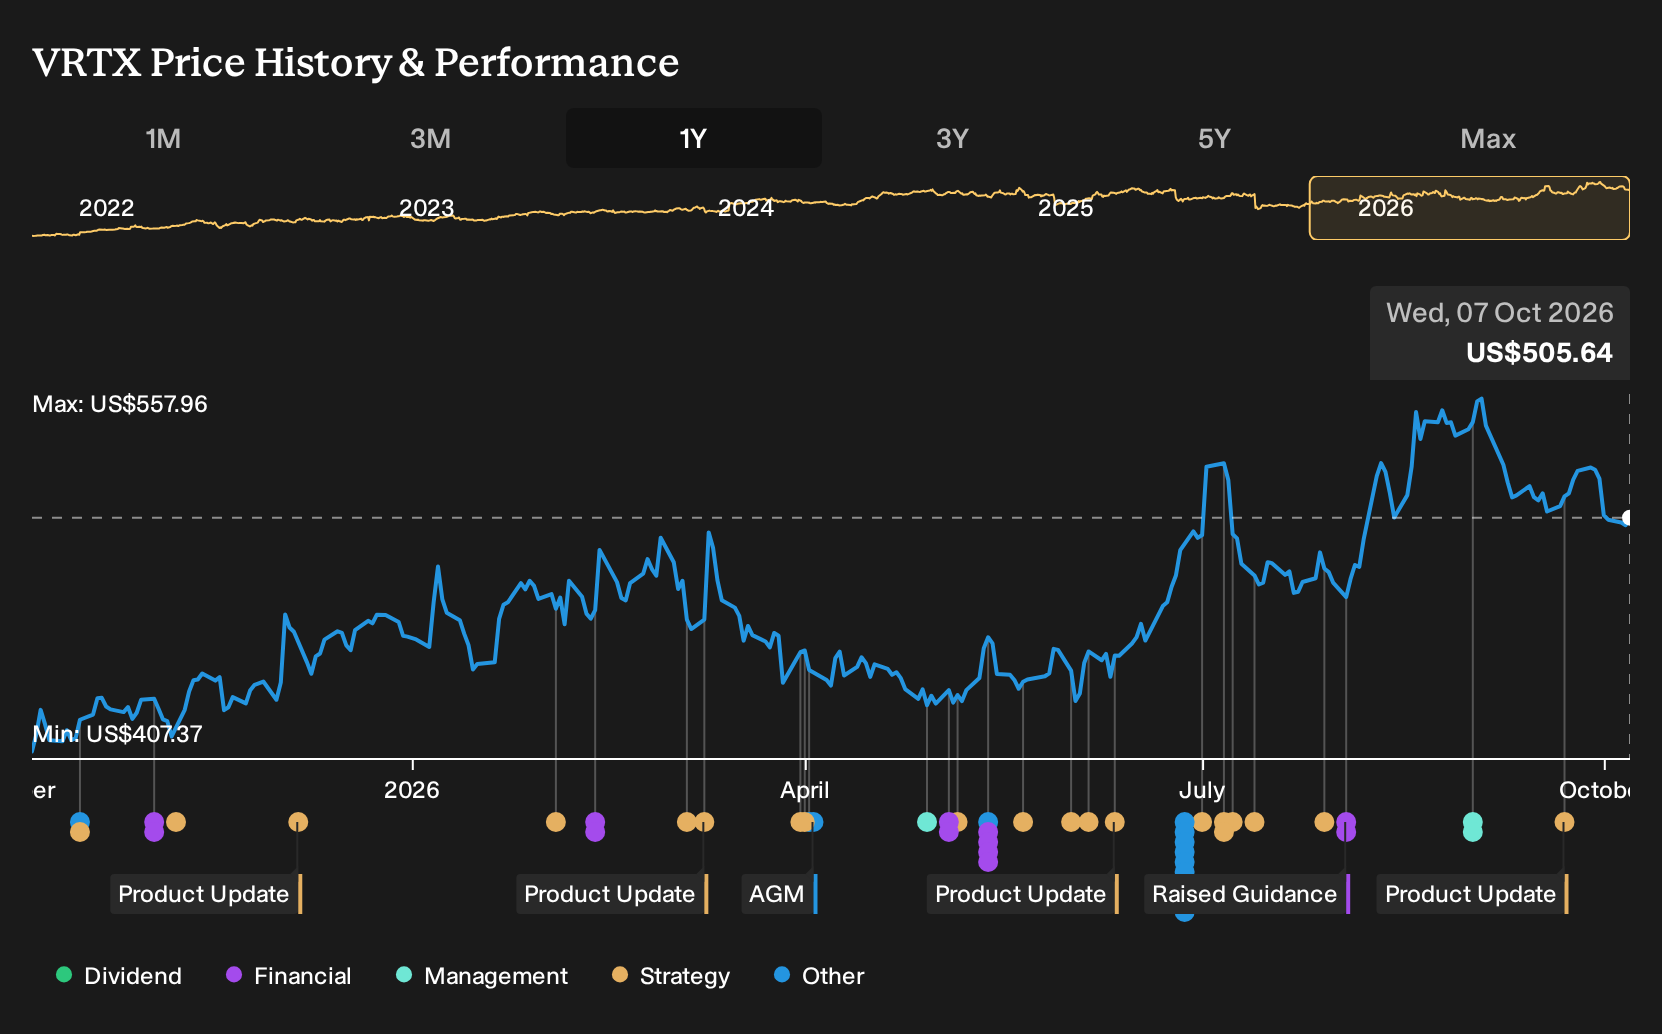
The most relevant data point tied to this earnings reset is management’s raised 2026 revenue guidance to US$13.1b to US$13.2b, supported by broader uptake of ALYFTREK, CASGEVY and JOURNAVX. That signal sits in the background as EPS expectations for the upcoming quarter shift down to US$4.86.
For you as an investor, the tension is clear. Consensus is inching lower on near term earnings while Vertex Pharmaceuticals still talks about non CF products contributing at least US$0.5b of 2026 sales and expanding renal and endocrinology programs. The story is increasingly about timing and execution rather than new information on direction.
Vertex Pharmaceuticals’ current analyst blueprint points to revenues of US$17.6b and earnings of US$6.3b by 2029, based on an assumed 11.7% yearly gain in revenue and an increase in earnings of about US$1.9b from US$4.4b today.
Uncover why Vertex Pharmaceuticals' fair value indicates a 13% potential upside to its current price before enthusiasm around Vertex Pharmaceuticals closes that gap.
Exploring Other Perspectives
One alternate view on Vertex Pharmaceuticals leans heavily on JOURNAVX patient support costs. The most cautious analysts had already penciled in slower normalization and were only expecting about US$16.3b of revenue and US$5.1b of earnings by 2029, compared with the higher consensus path. That is a much more pessimistic story. With the fresh EPS cut to US$4.86, you can assume both the upbeat and bearish narratives may shift. It is worth reading across several viewpoints before deciding how this new data point fits your own expectations.
Explore 5 other Vertex Pharmaceuticals fair value estimates, including one that suggests as much as 15% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vertex Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Vertex Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vertex Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Vertex Pharmaceuticals?
If the shifting expectations around Vertex Pharmaceuticals have you rethinking where the next opportunity might come from, it can help to line it up against a broader watchlist of candidates with different risk and return profiles.
- For investors who care most about financial strength and cleaner balance sheets, scan a list of solid balance sheet and fundamentals (25 results) and see which businesses match your risk comfort.
- If steadier income is higher on your list than rapid upside, review a curated set of 7 dividend fortresses that might better align with a cash flow focused approach.
- When the goal is to uncover something off the beaten path with solid fundamentals, work through a hand picked 20 high quality undiscovered gems that could expand your opportunity set beyond the usual large caps.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com