


Powell Industries (POWL) is back on screens after a sharp long term performance story resurfaced, highlighting how a US$1,000 investment five years ago would now be worth US$22,942.40.
Short term, Powell Industries has been choppy, with the share price down about 3.4% over the last day but up 7.2% over the week and 9.2% across the past month, while the 90 day share price return has fallen 16.4% as some earlier enthusiasm cools.
That pullback sits against a much stronger backdrop, with the year to date share price return at 68.3% and the 1 year total shareholder return at 88.5%, and longer term investors still holding a very large 3 year and 5 year total shareholder return. This points to momentum that has been powerful even if shorter term swings now hint at investors reassessing how much growth and risk they are prepared to price in at around US$197.74 per share.
Capitalize on Powell Industries’ momentum story and see how it compares with other infrastructure and power-grid plays in our hand picked 43 power grid technology and infrastructure stocks.Powell Industries appears to be a strong operator in power equipment. However, after a long run and a recent wobble, the key question is straightforward: Are you paying a fair price for that quality today?
Most Popular Narrative: 41% Undervalued
The most followed narrative on Powell Industries pegs fair value at $333 per share, well above the last close of $197.74, which frames today’s price as baking in far less growth and profitability than that scenario assumes.
The multi year build out of U.S. LNG export facilities and related natural gas infrastructure is contributing to a pipeline of large, complex projects, supporting backlog stability, higher plant utilization and stronger gross margins.
Strategic capacity expansions in Houston and ongoing productivity investments are increasing throughput and manufacturing leverage. This may enable Powell to convert its record backlog more efficiently and support higher operating margins over time.
See why 5 investors see Powell Industries as 41% undervalued.
That storyline leans on a 9.22% discount rate and assumes revenue growth of about 21.9% a year with profit margins edging toward 17.8%, which is more optimistic than the consensus forecasts embedded in the broader Statements data. It also implies Powell Industries would be valued on a richer multiple in 2029 than the wider US Electrical peer group, so investors are effectively being asked to judge whether that level of execution and market share capture is realistic.
For anyone weighing this profile against other grid and power plays, it can help to cross check the narrative’s assumptions on backlog conversion, LNG exposure and data center demand against your own expectations for capital spending cycles, then decide how much of that upside you are comfortable baking into your own valuation work.
Result: Fair Value of $333 (UNDERVALUED)
Still, the Powell Industries story depends heavily on LNG and data center projects arriving as expected, and on current record level margins not slipping back toward more typical levels.
Find out about the key risks to this Powell Industries narrative.
Another View On Powell Industries’ Valuation
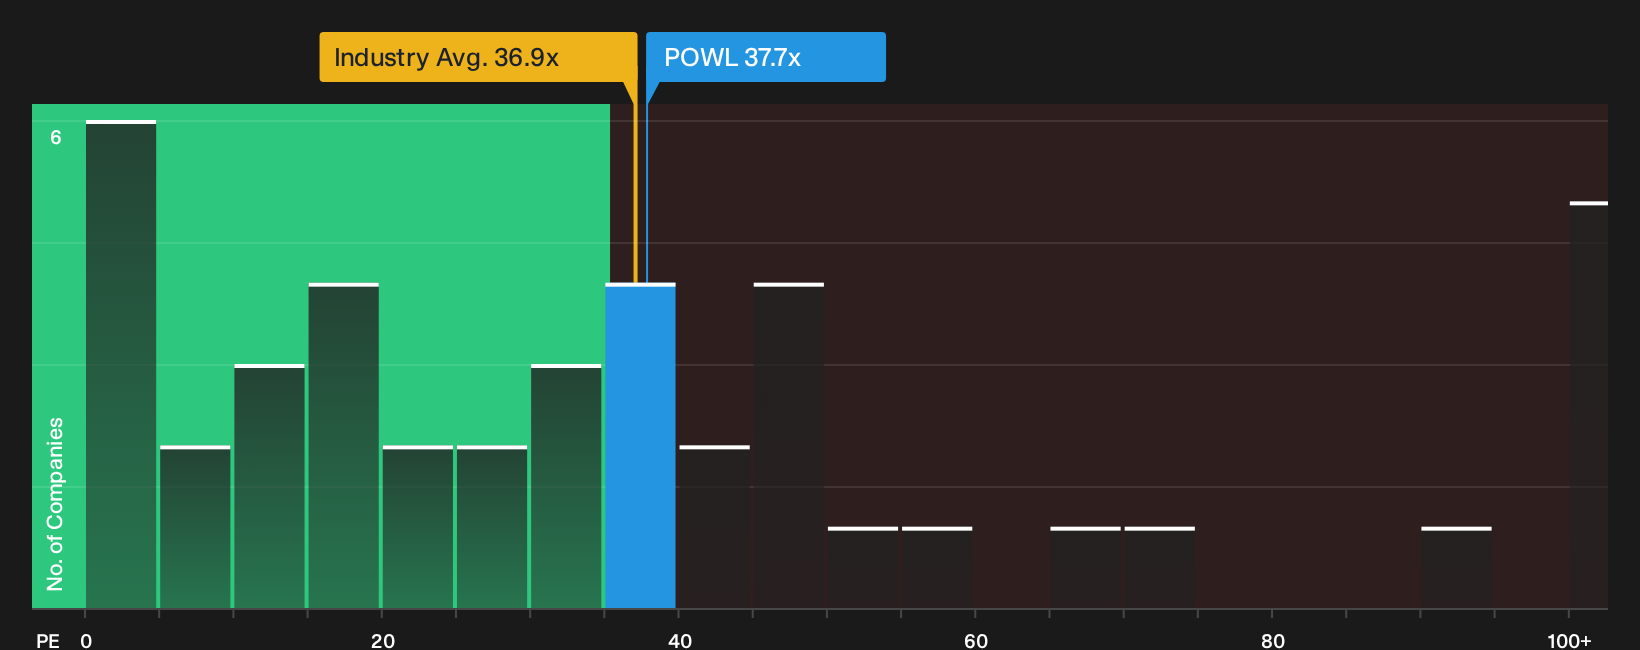
The story shifts when you look at Powell Industries through its current P/E. The shares trade on 37.7x earnings, which is richer than the US Electrical sector at 36.9x and well above a fair ratio of 30x. That kind of gap can turn optimism into valuation risk if expectations cool.
To see what the numbers say about this price, take a look at our valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
For context on how the current earnings multiple stacks up against peers visually, review the latest comparison in
Next Steps
Mixed signals around Powell Industries often trigger strong opinions, so consider acting promptly, review the underlying data for yourself, and weigh both sides in the 3 key rewards and 1 important warning sign.
Looking for more Powell Industries sized ideas?
If you stop with Powell Industries, you risk missing other opportunities that fit your style. Use the screener to hunt for your next move.
- Target resilient balance sheets and strong fundamentals by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a discount by filtering for companies in the 29 high quality undervalued stocks.
- Zero in on under followed opportunities by searching through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com