


Rigetti Computing has seen sharp swings in its share price over the past few years, which now puts the spotlight on a basic question for investors who care about downside protection. Is the current valuation of Rigetti stock meaningfully supported by the book value sitting on its balance sheet, especially when compared with the wider industry average?
- Over the past 3 years the share price has delivered a very large gain of about 7x, which raises the question of how much of that move is reflected in Rigetti's underlying net assets.
- Recent insider selling across several quantum computing companies, including Rigetti, may signal that management teams see a gap between market enthusiasm and the pace at which assets and commercial adoption can build on the balance sheet.
- The analysts covering Rigetti Computing have run their own numbers. See what analysts think Rigetti Computing's shares could be worth.
The issue now is whether the price investors are paying for Rigetti today can be reasonably grounded in its book value relative to the industry average.
To see how this same question about book value versus price plays out across other quantum computing stocks, review the 24 quantum computing stocks.
Is Rigetti Computing Getting Expensive on Book Value?
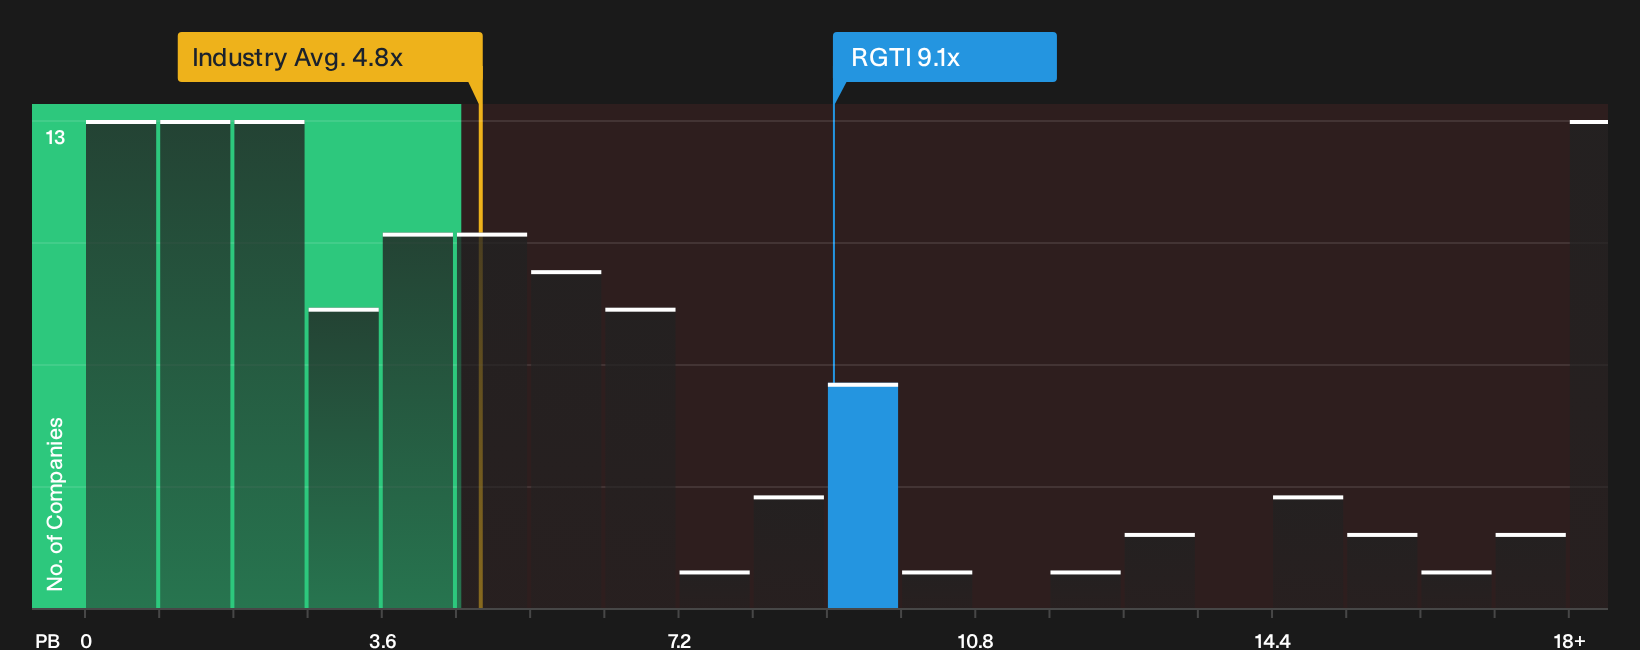
P/B is a useful gauge for Rigetti Computing because investors are effectively paying for hard assets and research capacity while waiting to see how commercial traction evolves. On this yardstick, Rigetti trades on a P/B of 9.1x, which is almost double the semiconductor industry average of 4.8x and only slightly below the peer group around 9.6x. That combination points to an overvalued reading against the broader chip sector, even though it is roughly aligned with other quantum specialists that also carry rich balance sheet premiums.
Recent insider selling across quantum computing stocks, including Rigetti, lands awkwardly against that valuation because it suggests some executives may see the current P/B as pricing in a lot of optimism already. For you as a shareholder or prospective buyer, the key question is whether the existing equity base and future capital needs genuinely justify paying such a high multiple to book value compared with established semiconductor businesses. Explore the numbers behind Rigetti Computing's P/B valuation.
The Rigetti Computing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Rigetti Computing pick up where the P/B puzzle leaves off and explain what kind of future in terms of growth, margins and earnings would need to occur for the valuation to appear stretched or conservative. While a single ratio or model produces one number, these scenarios unpack the path that number relies on so you can track how Rigetti Computing's actual progress compares over time on the Community page.
One of the top community narratives on Rigetti Computing: 49% undervalued
"Multi year government and defense related work, including the US$5.8 million three year AFRL contract for superconducting quantum networking and continued participation in DARPA QBI Phase A, ties Rigetti to long term public sector quantum programs…"
Discover why this Narrative puts Rigetti Computing at 49% undervalued.
One more Rigetti Computing check to weigh before you move on
Price ratios only tell part of the story, and Simply Wall St's broader review of Rigetti Computing has flagged specific concerns that investors may want to weigh alongside the valuation picture. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com