


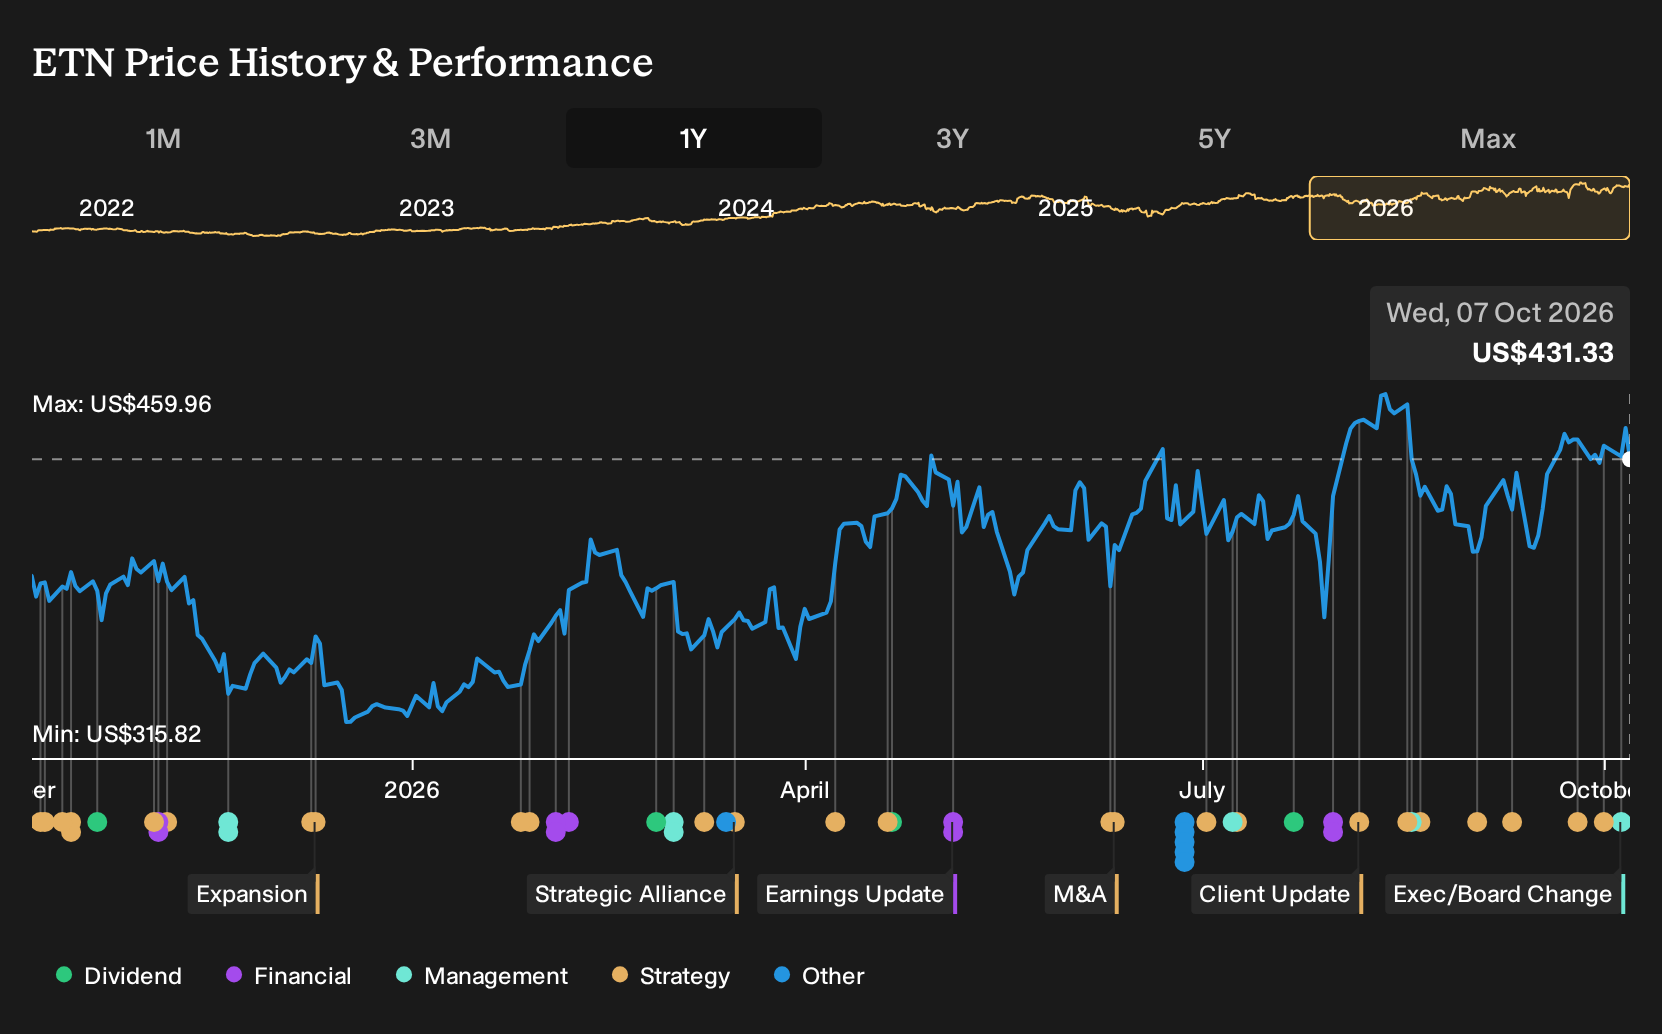
- Eaton expanded its Schrems, Austria plant with 5,000 m² of new space, integrating automated miniature circuit breaker lines and a connected manufacturing execution system for real time production, logistics and quality control across its European power management portfolio.
- The upgraded facility is intended to tighten traceability, support regulatory compliance and shorten lead times for customers that depend on highly available electrical power, especially in critical infrastructure across Europe.
- This Schrems capacity build out is a key element in Eaton’s current investment narrative, which is being evaluated alongside existing analyst earnings expectations.
Eaton Investment Narrative Recap
To own Eaton, you need to believe that its power management portfolio can keep benefiting from electrification, data centers and grid upgrades, while the weaker vehicle and legacy operations do not drag too hard on margins. The Schrems expansion fits that view, since it points to management leaning into electrical capacity and Industry 4.0 execution.
The most important short term swing factor remains clean execution on the electrical backlog and recent capacity projects, without further pressure on net margins that already sit at 12.8%, below last year’s 15.1%. The board level reshuffle in accounting looks incremental for now. It does not materially shift the core risk reward equation.
The executive change around Eaton’s principal accounting officer is the announcement that ties most closely to the Schrems news. A new Senior Vice President and Controller, Andrea Trabacchin, takes responsibility for financial reporting, while the former controller moves into a broader electrical finance role. That is where the capital and backlog are concentrating.
For you as a shareholder, the key question is whether a relatively new management bench, with average tenure of 1.6 years, can keep tight control of costs, debt and returns while the electrical and data center build out continues. Analysts already expect earnings to grow 18.1% a year. Any slip in controls or project execution could pressure that narrative.
Eaton Forecasts In Context
Eaton's narrative projects US$43.4b revenue and US$7.5b earnings by 2029. Analysts are assuming 13.0% yearly revenue growth, and this path implies roughly a 2x earnings increase from US$3.8b today.
Uncover why Eaton's fair value indicates an 11% potential upside to its current price, a discount that could narrow quickly if sentiment turns.
Exploring Other Perspectives
One alternate view focuses on labor constraints rather than backlogs. The most optimistic Eaton analysts were already baking in revenue of about US$46.3b and earnings of US$8.1b by 2029, before this Schrems expansion and accounting reshuffle. You can treat those forecasts as one end of a wide spectrum and explore where you feel comfortable.
Explore 7 other Eaton fair value estimates, including one that indicates there could be as much as 24% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Eaton research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Eaton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eaton's overall financial health at a glance.
Looking for more ideas beyond Eaton?
If Eaton has sharpened your focus on power infrastructure and resilient balance sheets, it can help to widen the lens and compare it with other opportunities that fit your style as an investor.
- For investors who care most about quality at a sensible entry point, scan our 29 high quality undervalued stocks that pair stronger fundamentals with what may be more modest market expectations.
- If income and resilience matter more to you than rapid expansion, sort through the 7 dividend fortresses to find companies that currently offer higher yields with an emphasis on stability.
- For a broader watchlist built around financial strength, filter the list of solid balance sheet and fundamentals (25 results) and focus on businesses where debt, cash and profitability look more robust on current numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com