


Why Gerresheimer’s Latest Earnings Shocked Investors
Gerresheimer (XTRA:GXI) moved into focus after its Q2 2026 earnings call highlighted a tougher start to the year, with first quarter sales of €474.94 million and a net loss of €98.32 million.
The loss per share widened to €2.85 compared with €0.37 a year earlier, while sales edged below the prior €478.64 million figure, raising fresh questions about how the business is currently being valued.
Recent trading tells a mixed story. Gerresheimer’s share price has risen 4.32% year to date, but the 1 year total shareholder return has fallen 22.34%. The 3 year and 5 year total shareholder returns have declined 71.15% and 62.8%, which points to fading longer term momentum despite a small rebound into the latest earnings shock.
Spot opportunities beyond Gerresheimer’s setback, and review a curated 184 high quality undervalued stocks that combines stronger recent returns with balance sheets that may better support the next leg of your portfolio.A 4.32% gain this year, set against steep 3- and 5-year declines, leaves Gerresheimer looking either early in a recovery or already priced for one. Which side of that debate do the current valuation markers support?
Most Popular Narrative: 6% Overvalued
Gerresheimer last closed at €29.00, which sits modestly above the most followed fair value estimate of €27.38 that is built on detailed earnings and cash flow assumptions.
The analysts have a consensus price target of €27.38 for Gerresheimer based on their expectations of its future earnings growth, profit margins and other risk factors. However, there is a degree of disagreement amongst analysts, with the most bullish reporting a price target of €46.0, and the most bearish reporting a price target of just €20.0.
See why 14 investors see Gerresheimer as 6% overvalued.
Result: Fair Value of €27.38 (OVERVALUED)
Still, the Gerresheimer story could change quickly if Bormioli integration costs bite harder than expected or if cash flow seasonality strains liquidity again.
Find out about the key risks to this Gerresheimer narrative.
Another View: Gerresheimer Looks Cheap On Sales
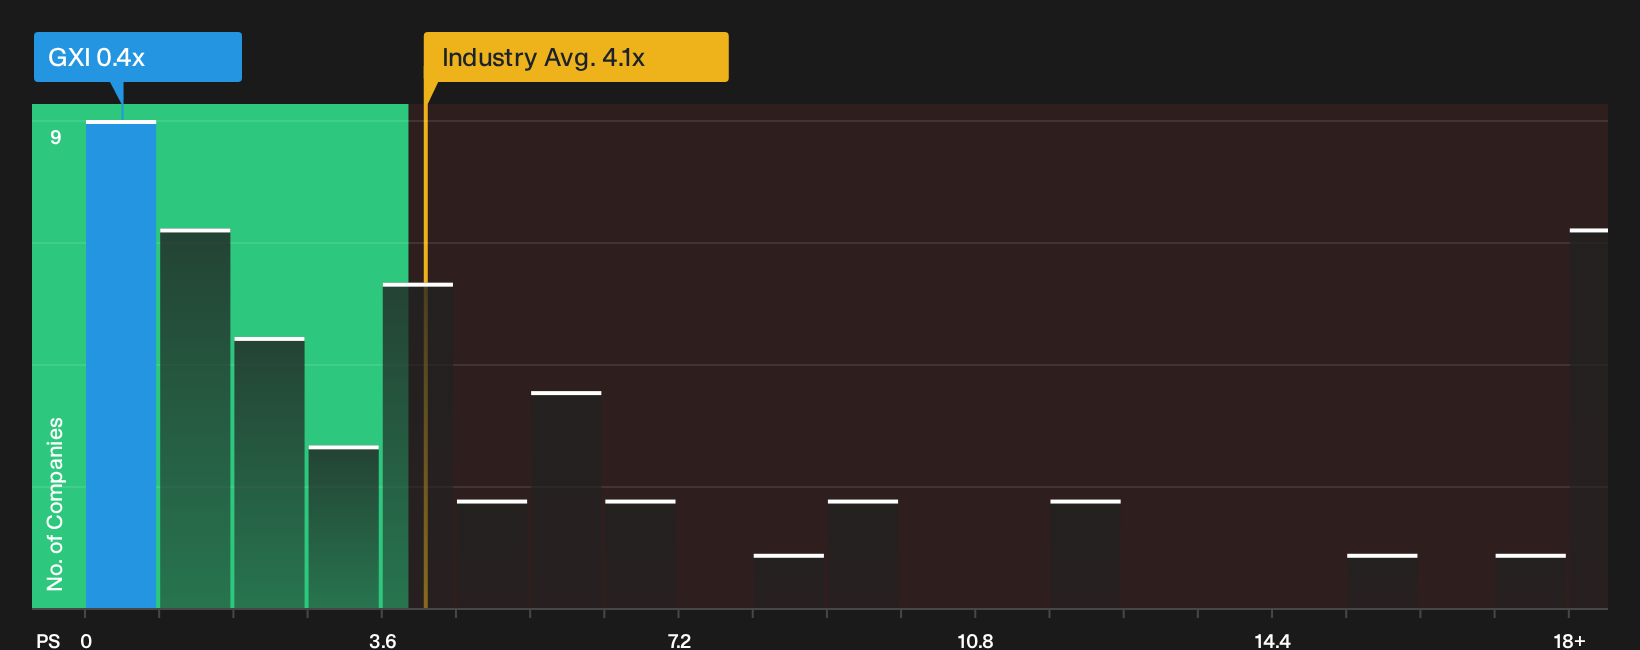
On the flip side, Gerresheimer screens as inexpensive when you look at P/S. The stock trades at roughly 0.4x sales, compared with about 4.1x for the wider European Life Sciences group and 8.1x for closer peers, while the fair ratio sits near 0.8x.
That gap points to a heavy discount against sector norms, even after factoring in weaker profitability and higher funding risk. The real question is whether that markdown reflects temporary problems or a longer lasting reset in what investors are willing to pay for Gerresheimer.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by the mix of pressure and potential around Gerresheimer right now. Act quickly, review the data for yourself, and weigh both sides with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Gerresheimer?
If Gerresheimer’s mixed signals leave you on the fence, broaden your watchlist now so you are not relying on a single recovery story.
- Target higher yield potential by scanning for established payers through the 169 dividend fortresses that may align better with your income goals.
- Hunt for sturdier balance sheets by reviewing the list of solid balance sheet and fundamentals (207 results) so fragile financing does not catch you off guard.
- Spot tomorrow’s potential leaders early by combing through the 619 high quality undiscovered gems before the crowd starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com