


Geopolitical instability in the Middle East has kept energy supply risks in focus, and that backdrop has drawn fresh attention to LandBridge (LB), a Houston based owner of Delaware Basin surface assets.
The stock has been choppy in the short term, with a 7 day share price return of 5.61% but a 30 day share price return that slipped 0.94%. At the same time, the 90 day share price return of 9.35% and year to date share price gain of 76.89% point to strong positive momentum that aligns with a 1 year total shareholder return of 59.49% on the back of growing attention on LandBridge as energy security stays in the headlines.
Scan geopolitically sensitive energy plays like LandBridge alongside a curated 43 power grid technology and infrastructure stocks that could also be in focus as markets reassess long term supply security.After a near 77% year to date run and a share price that now sits close to analyst targets, the real puzzle is whether LandBridge still offers valuation upside or if most of the easy gains are already behind it.
Most Popular Narrative: 2% Undervalued
On Simply Wall St's most followed view, LandBridge screens as slightly undervalued, with a fair value estimate of $87.43 against the last close at $85.72. This puts the market almost in line with that narrative but still leaves a small valuation gap on their numbers.
LandBridge's capital-light model and focus on long-term, fee-based contracts (for example, triple-net leases and surface use royalties now making up 94% of revenue) enhance free cash flow generation and lead to greater earnings resiliency, even in periods of commodity price weakness, positively affecting both EBITDA margins and cash flow stability.
See why 17 investors see LandBridge as 2% undervalued.
Result: Fair Value of $87.43 (UNDERVALUED)
Still, the LandBridge story can be knocked off course if Permian-focused concentration faces regulatory or water constraints, or if data center projects keep sliding to later years.
Find out about the key risks to this LandBridge narrative.
Another View On LandBridge’s Valuation
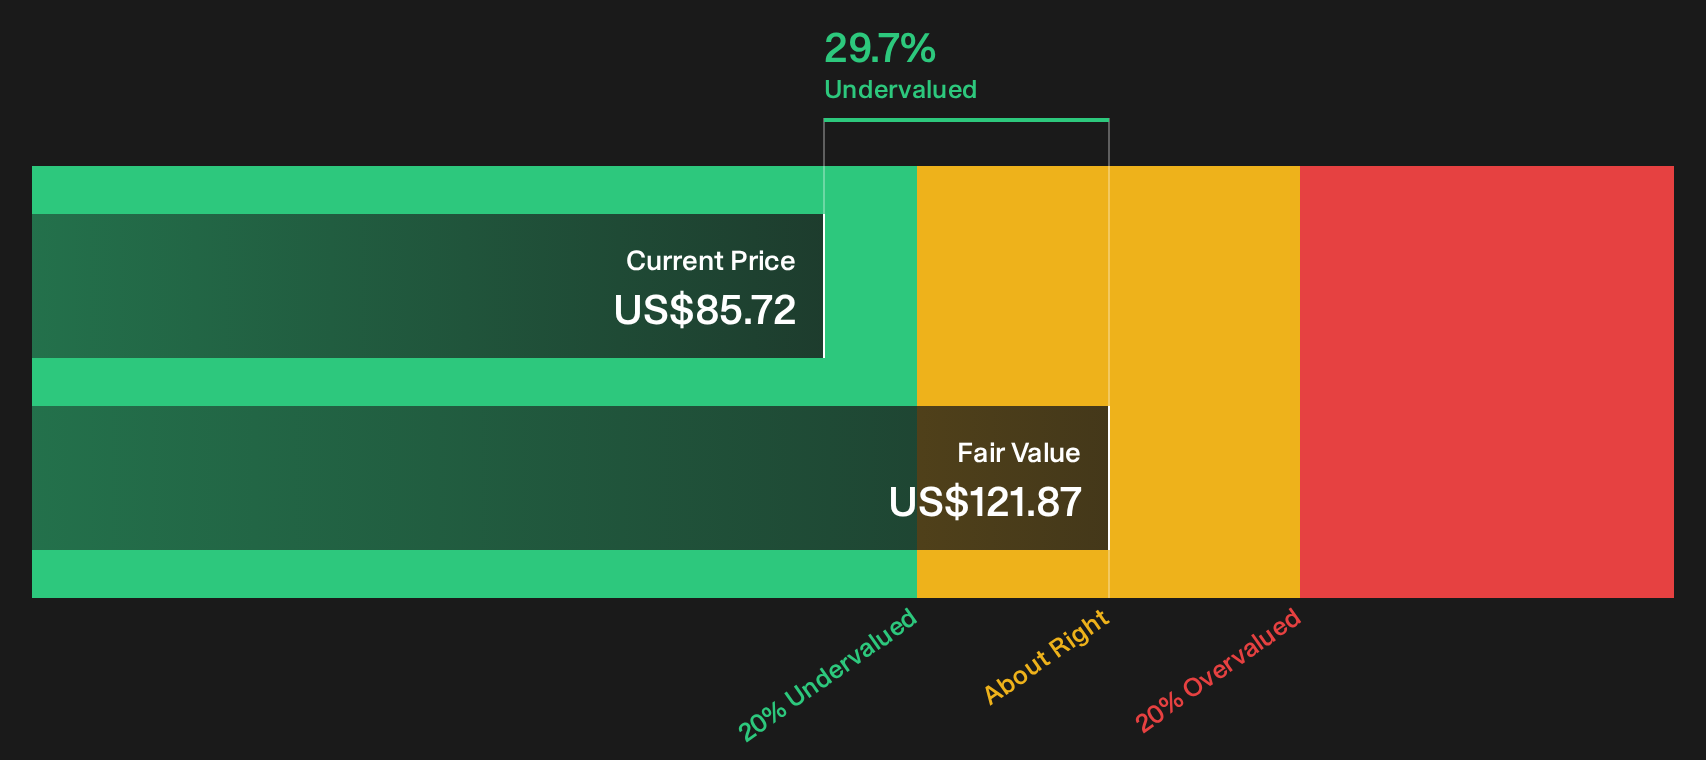
On the headline numbers, LandBridge screens as cheap against an $87.43 fair value estimate, with the Simply Wall St model flagging a 29.7% discount to an assessed future cash flow value of $121.87. Our DCF model is clearly more optimistic than the near inline analyst target, so which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
The LandBridge story has shown mixed signals so far. If you want to move quickly and reach your own verdict, start by weighing the 3 key rewards and 1 important warning sign.
Looking for more LandBridge sized opportunities?
If LandBridge is on your radar, do not stop there. Use the Simply Wall St screener to quickly surface fresh ideas that fit your style and risk comfort.
- Target resilient growers by scanning a curated 29 high quality undervalued stocks that combine quality fundamentals with prices that still sit below fair value estimates.
- Strengthen portfolio durability by focusing on a list of solid balance sheet and fundamentals (25 results) that can better withstand shocks and funding pressures.
- Get early to potential future leaders by reviewing a 20 high quality undiscovered gems that have strong fundamentals but limited market attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com