


- Monolithic Power Systems is drawing attention after being recognized for annual revenue growth, market share gains, robust earnings per share trends, and high returns on capital in its power management chip business.
- The premium valuation now attached to Monolithic Power Systems highlights how investors are focusing on its energy efficient power solutions as a core driver of the business story rather than short term trading sentiment.
- This article reviews how Monolithic Power Systems' premium valuation tied to efficient power chips influences the broader investment narrative today.
Scan beyond Monolithic Power Systems and shortlist other power and efficiency driven chip specialists with the hand picked 92 AI infrastructure stocks that aligns with this premium valuation story.
Monolithic Power Systems Investment Narrative Recap
For you to stay on board as a Monolithic Power Systems shareholder, you need to believe its energy efficient power chips can keep finding new high value sockets in AI data centers, automotive and other electronics. The recent recognition of revenue growth, market share gains and returns on capital mainly reinforces that core belief rather than changing it.
The bigger swing factor near term is how quickly demand absorbs the planned manufacturing capacity that supports revenue equivalents beyond US$6b. The sharp drop in net profit margin from 65.6% to 24.5% shows how sensitive the model is to investment and mix. Ongoing investigations and customer order concerns remain the clearest operational risk.
Recent attention on Monolithic Power Systems ties closely to its long term manufacturing partnership in Singapore and capacity plan that stretches past US$6b in annual revenue equivalents. That build out is not a side project. It sits at the center of the current premium P/E multiple and the story around data center and automotive exposure.
If that new footprint ramps smoothly, with silicon carbide, GaN and data center focused products filling the fabs as planned, the business could support its high returns on equity, which are forecast at 30.4% in three years. If utilization lags or legal issues slow customer wins, those same fixed costs could pressure free cash flow for longer.
Monolithic Power Systems' current analyst story points to revenues of US$6.9b and earnings of US$2.1b by 2029, based on an assumed 28.2% yearly revenue growth rate and an earnings increase of about US$1.3b from US$801.9m today.
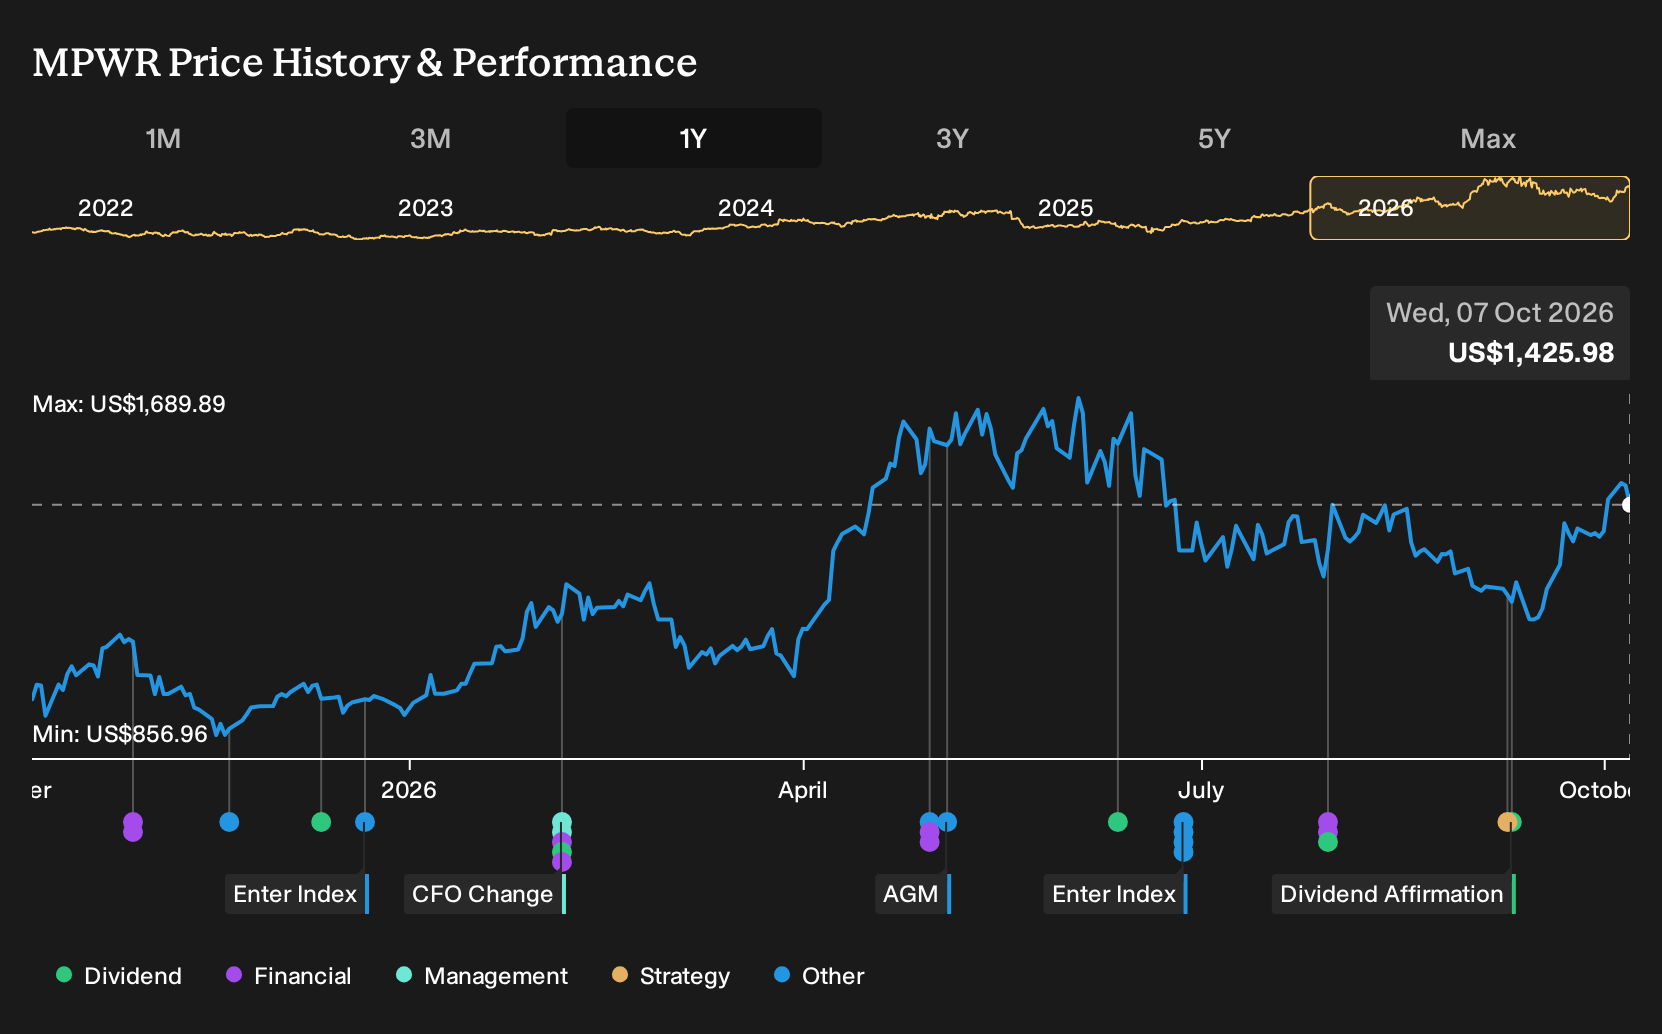
Uncover how Monolithic Power Systems' fair value indicates a 29% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
Some of the most optimistic analysts on Monolithic Power Systems lean hard into the AI data center catalyst. They were already sketching out revenues of about US$10.4b and earnings near US$2.4b by 2029, compared with the consensus US$6.9b and US$2.1b. That gap shows how widely opinions can differ, and why this new recognition of its power efficiency story might push those narratives to evolve. Readers should treat these forecasts as one angle and compare several viewpoints before deciding what feels reasonable.
Explore 4 other Monolithic Power Systems fair value estimates, including one that suggests as much as 47% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Monolithic Power Systems research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Monolithic Power Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Monolithic Power Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Monolithic Power Systems?
If the Monolithic Power Systems story has sharpened your focus on quality, cash generation and pricing power, it can be useful to scan a wider watchlist built around similar priorities. The Simply Wall St Screener lets you quickly filter for different traits so you are not relying on a single stock to carry your whole thesis.
- For investors hunting for resilient balance sheets and cleaner fundamentals, the list of solid balance sheet and fundamentals (25 results) can help surface companies that put financial strength ahead of hype.
- If your priority is to find shares that trade below their estimated worth with quality metrics to match, the 29 high quality undervalued stocks is a practical way to build a shortlist tailored to that goal.
- Income focused readers who want yield backed by substance rather than headline percentages can use the 8 dividend fortresses to spot payout profiles that may better align with long term objectives.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com