


ASML Holding (NasdaqGS:ASML) continues to draw attention after recent share price moves, with the stock closing at US$1,804.96. Investors are weighing strong multi year total returns against current growth and profitability figures.
Recent trading tells a mixed story for ASML Holding. The share price is down 1.59% over the last session but shows a 5.25% gain over 30 days. The year-to-date share price return of 55.09% sits alongside a 1-year total shareholder return of 83.75%, which points to momentum built over several years.
Scan how ASML Holding compares to other chip-related opportunities by reviewing the hand picked 92 AI infrastructure stocks that is already catching market attention.
For ASML Holding at US$1,804.96 after such strong multi year gains, the real tension is simple: do you lean in now, or wait and hope for a cheaper entry as the valuation picture comes into focus next?
Preferred P/E of 58.1x: Is It Justified For ASML Holding?
Valuation on ASML Holding right now hinges on a simple fact. The stock trades on a P/E of 58.1x, which is above both its estimated fair P/E of 40.7x and key semiconductor peers, so the current share price near $1,804.96 reflects a heavy earnings premium.
P/E is just the share price divided by earnings per share. For chip equipment makers like ASML Holding, it is often used as a shorthand for how much investors are willing to pay today for each dollar of current profits, relative to the sector. A higher P/E usually signals the market is baking in strong profit expansion or viewing the business model as particularly resilient.
That premium does not come from nowhere. ASML's net profit margin sits at 30.1%, slightly higher than last year, and earnings have grown 14.4% per year over the past 5 years with high quality earnings flagged. Forecasts call for earnings growth of 21.7% per year and revenue growth of 16.3% per year, both ahead of the broader US market, while Return on Equity is already an outstanding 48.7% and is expected to reach 60.6%. Those figures help explain why the market is willing to pay much more than the 40.7x fair P/E estimate, even though that fair ratio points to a level the valuation could move toward if expectations cool.
Peer comparisons sharpen that point. ASML Holding's 58.1x P/E sits above the US Semiconductor industry average of 53.3x and also above a peer group average of 52.6x, which means investors are paying a clear premium even relative to a sector already priced for strong growth.
Result: Price-to-Earnings of 58.1x (OVERVALUED)
Explore the SWS fair ratio for ASML Holding.
Still, ASML Holding faces real pressure if chip equipment spending cools or if export controls reduce demand from key regions like China and Taiwan.
Find out about the key risks to this ASML Holding narrative.
Another View On ASML Holding Using Our DCF Model
There is a very different read on ASML Holding when switching from the P/E lens to the SWS DCF model. On this approach, the current share price of $1,804.96 sits above an estimated future cash flow value of $954.89, which points to the stock trading at a premium instead of a discount.
That gap means investors today are paying far more than the DCF output for each dollar of projected cash generation, so the margin of safety looks thin and any disappointment in future cash flows could matter quickly. The question is simple for you as a shareholder or watcher: which signal do you trust more when the cash flow model indicates rich pricing?
Look into how the SWS DCF model arrives at its fair value.
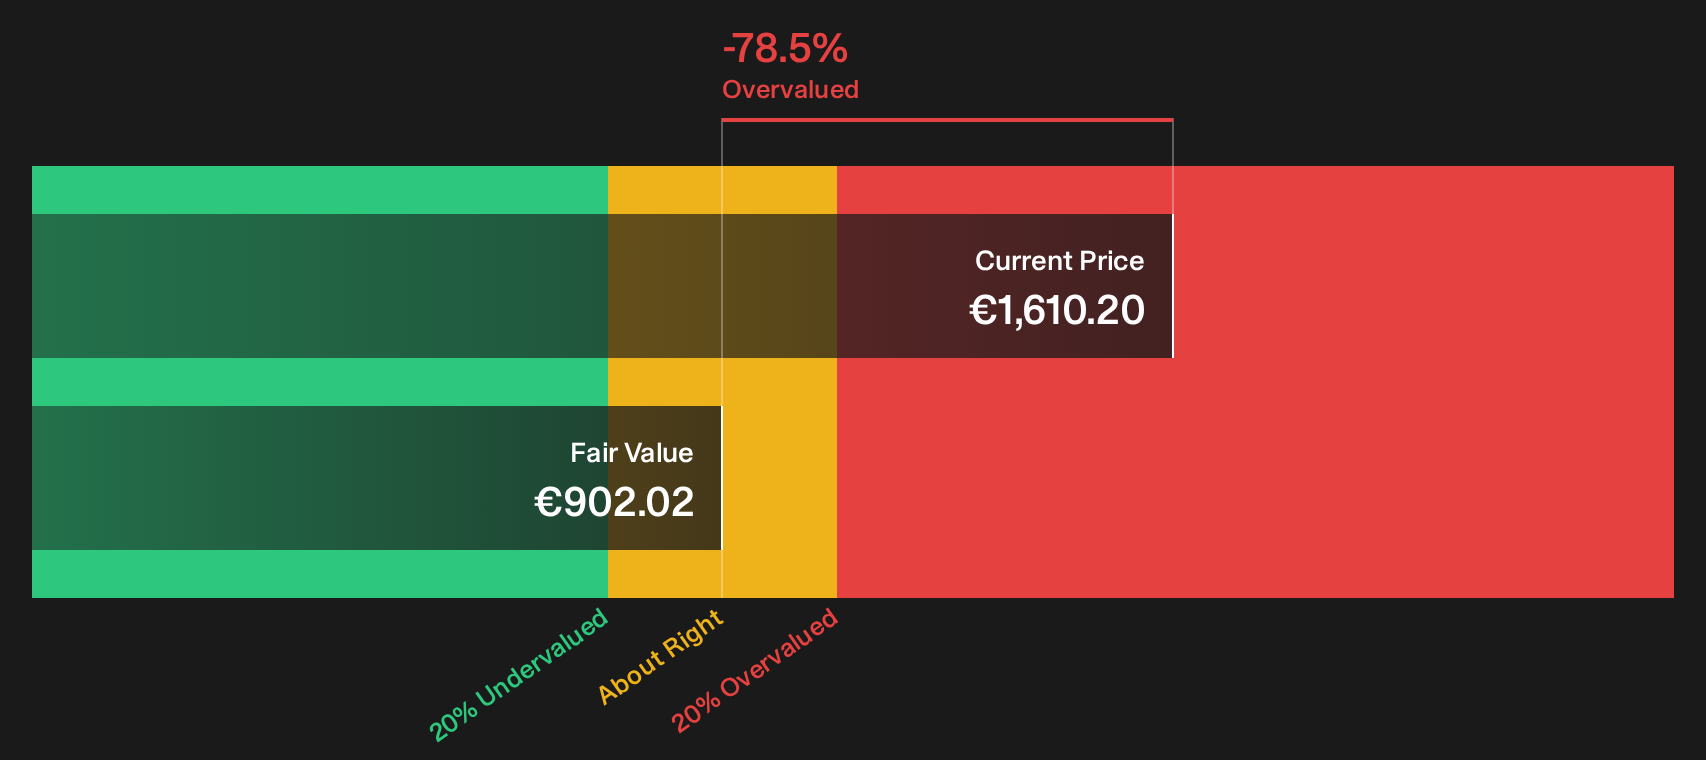
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ASML Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading through the numbers and mixed signals on ASML Holding, the next move is yours. This makes it a good moment to lean into the data rather than the headlines and form your own stance on what justifies the current premium. To see what optimism is already reflected in the outlook, review the 2 key rewards
Looking for more ASML Holding style investment ideas?
If the current setup around ASML Holding has you thinking hard about risk and reward, broaden your watchlist now and give yourself more options.
- Spot potential overreactions in smaller companies by scanning the 12 elite penny stocks with strong financials before the crowd turns its attention there.
- Target quality at a fair price and sort through the 29 high quality undervalued stocks that already pair fundamentals with more grounded expectations.
- Prioritise sleep-at-night stability by checking the 31 resilient stocks with low risk scores that rate well on resilience instead of only headline growth.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com