


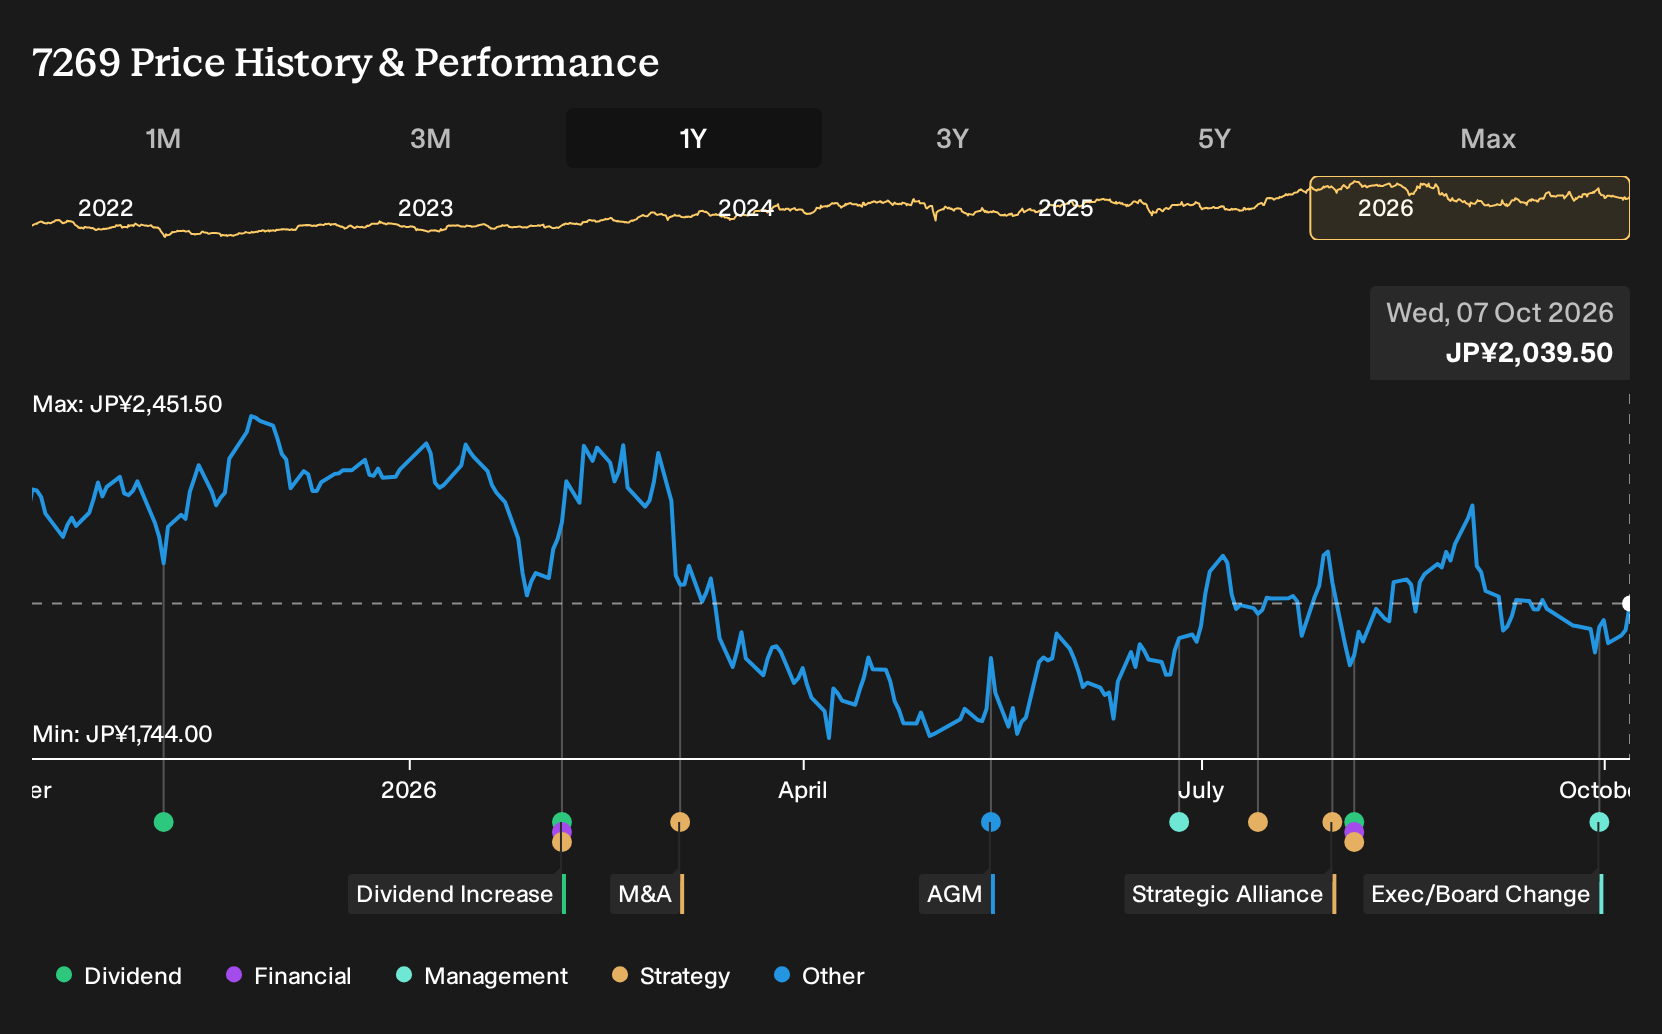
- Suzuki Motor reported that Mr. Kazunari Yamaguchi stepped down as Whole-time Director (Production) and risk management committee member on 30 September 2026. He remains on the board as a Non-executive Director, while Mr. Sarada Prasana Nayak became Head of Production and Production Engineering from 1 October 2026.
- The handover places day-to-day manufacturing planning, capacity decisions and plant efficiency for Suzuki Motor under a leader with extensive experience in large CAPEX programs, supplier development, new technologies and carbon neutral projects.
- We will examine how Suzuki Motor's broader investment narrative is influenced by this production leadership shift and change in operational responsibilities.
Compare how Suzuki Motor's production reset stacks up against peers by scanning list of solid balance sheet and fundamentals (23 results) that could also be shaping their next phase of factory investment and capacity planning.
What Is Suzuki Motor's Investment Narrative?
The big picture with Suzuki Motor is simple. You need to believe this manufacturer can keep turning a broad vehicle portfolio and sizeable global footprint into steady, high quality earnings while funding heavy factory spending without damaging returns. Recent results show earnings growth of 29% and revenue growth of 4.8%, with net profit margins at 7.9%. The share price is down 14.7% year to date, even though the stock trades on a P/E of 7.6x and carries a 2.5% dividend yield. This frames how the market currently prices those cash flows.
The boardroom move from Mr. Kazunari Yamaguchi to Mr. Sarada Prasana Nayak matters only if daily execution slips or large CAPEX is misjudged. Mr. Nayak’s background in multi plant projects, supplier localization and carbon neutral initiatives lines up directly with Suzuki Motor’s current capital intensive needs, from capacity expansion to smart factory efforts. In the short term, this looks more like continuity than disruption, although it lands at a time when forecasts already point to slower profit and revenue growth versus the wider JP market.
That said, one under discussed pressure point for Suzuki Motor sits where capital intensity, slower forecast earnings growth and board turnover all intersect with...
There's only one way to know the right time to buy, sell or hold Suzuki Motor. Head to Simply Wall St's company report for the latest analysis of Suzuki Motor's Fair Value.
Exploring Other Perspectives
The Simply Wall St Community currently includes 2 fair value views on Suzuki Motor, with estimates ranging from ¥2,072.68 to ¥2,556.47. That spread already shows how far apart private investors can be. When you factor in the fresh production leadership change, you get one more reason to compare several viewpoints before forming your own stance.
Explore another Suzuki Motor fair value estimate, including one that suggests it could be worth just ¥2073.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Suzuki Motor research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Suzuki Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Suzuki Motor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Suzuki Motor?
If the Suzuki Motor story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener can help you spot other opportunities that fit your style and risk tolerance.
- For investors who want quality and value to line up, review 15 high quality undervalued stocks that combine stronger fundamentals with a price that may not fully reflect them yet.
- If resilience matters most to you, sort through 22 resilient stocks with low risk scores that score well on financial strength and business stability.
- When you want to broaden your research beyond familiar tickers, scan 75 high quality undiscovered gems that pair solid financial profiles with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com