


Albertsons Companies (ACI) is in the middle of a leadership shakeup that puts its board and finance team in the spotlight just as investors look toward the upcoming Q2 earnings report.
The leadership refresh has not yet translated into stronger trading momentum for Albertsons Companies, with the share price at US$11.74 after a 1-day share price return of 2.26% but a 90-day share price return that is down 18.13% and a 1-year total shareholder return that is down 29.45%. This points to fading confidence as investors weigh store closures, margin pressure concerns and the upcoming Q2 update against the longer record of weaker total shareholder returns over 3 and 5 years.
Spot potential rebound candidates alongside Albertsons Companies by scanning our curated list of 29 high quality undervalued stocks with solid fundamentals and recent share price pressure.After that kind of slide, together with fresh leadership and store pruning, Albertsons Companies starts to look more about potential payoff than past disappointment. Does the current valuation still leave enough upside to justify the risk?
Most Popular Narrative: 17% Undervalued
At a last close of $11.74 versus a most followed fair value estimate of $14.19, Albertsons Companies screens as discounted on narrative models that lean heavily on earnings recovery and capital returns over the next few years.
Modernization through technology investments, such as automation, AI-driven inventory/pricing, and centralized buying, are streamlining operations, reducing labor and supply chain costs, and positioning the company for long-term margin expansion and improved net earnings. Increasing penetration of private label and own brands (now at 25.7% of sales with a push to reach 30%+), along with targeted value investments, are driving higher-margin sales, deepening brand loyalty, and contributing to gross margin stabilization over time.
See why 20 investors see Albertsons Companies as 17% undervalued.
The fair value narrative relies on a discount rate of 10.89%, relatively flat revenue around $83.7b and a profit margin assumption lifting from 0.1% today to 0.7% by 2029. It also leans on analysts expecting earnings to reach $621.1m with a future P/E of 12.2x, which is lower than the current 19.3x P/E for the US Consumer Retailing industry cited in the same narrative.
For this view to hold up, an investor has to accept several stacked assumptions. Earnings would need to scale meaningfully from the current $65.7m base, margins would have to improve despite recent pressure, and the share count would need to move lower, with the narrative pointing to a 7% annual reduction over the next three years.
There is also a clear trade off between this story and the recent share price record for Albertsons Companies. The stock has declined 29.45% on a 1 year total return basis and 43.3% over three years while the narrative still applies a higher future P/E multiple than before and trims the fair value only modestly, from $15.31 to $14.19, after guidance cuts and execution concerns.
Analyst targets also span a wide range, from $10.00 at the low end to $24.00 at the high end, and the statements data flags that estimates are not tightly clustered. That level of dispersion usually points to very different views on execution risk for the restructuring plan, the impact of store closures and the potential for margins to actually reach the 0.7% level in the model.
Result: Fair Value of $14.19 (UNDERVALUED)
Still, the narrative around Albertsons Companies can quickly unravel if execution stumbles on the ACI Edge restructuring, or if rising labor costs squeeze already thin margins.
Find out about the key risks to this Albertsons Companies narrative.
Another View On Albertsons Companies: Multiples Paint A Tougher Picture
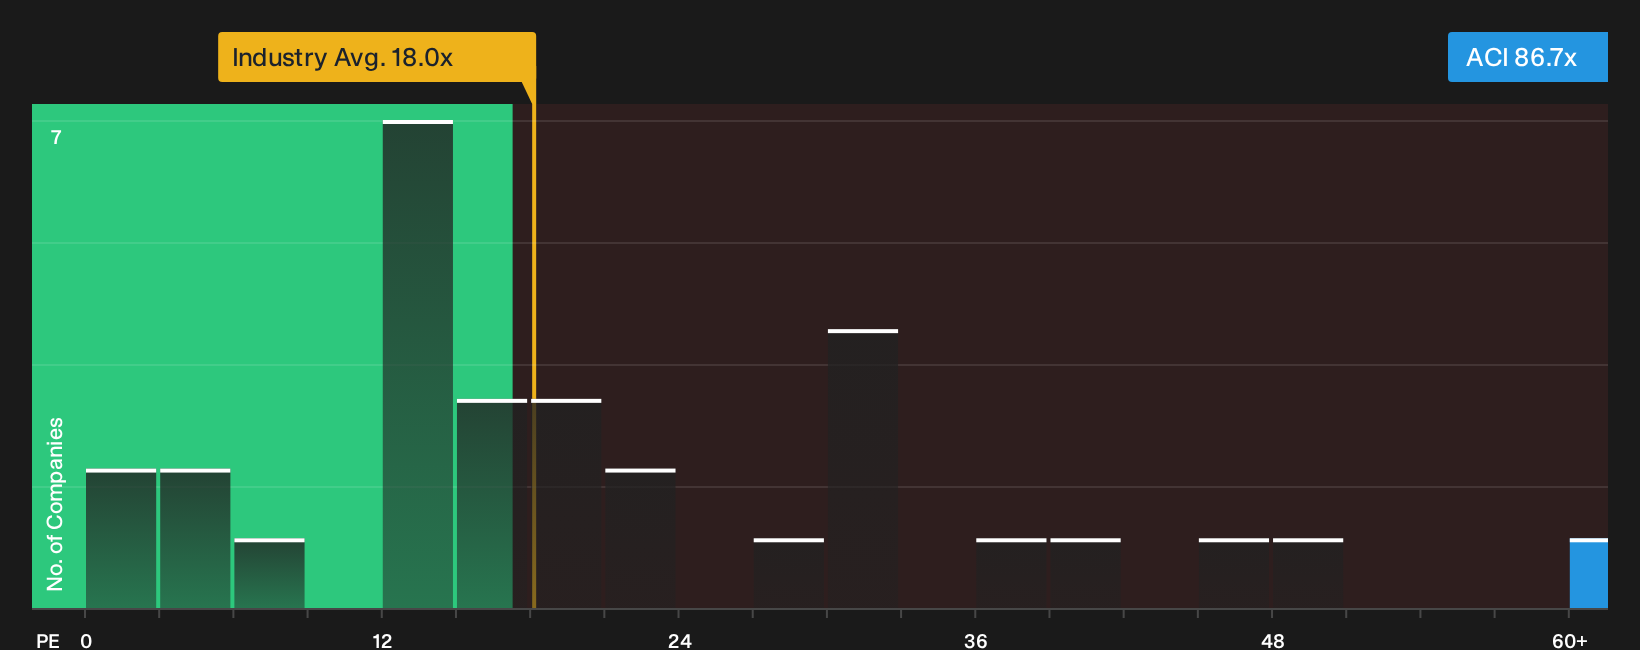
The earlier narrative leans on earnings recovery and a fair value of $14.19. On simple market ratios, Albertsons Companies tells a very different story. The stock trades on a P/E of 86.7x compared with 18x for the US Consumer Retailing industry and 17x for close peers.
The fair ratio for Albertsons Companies is 32x P/E, which is far below the current 86.7x level. That kind of gap points to meaningful downside risk if sentiment cools and the market drifts back toward what the regression model suggests is a more typical multiple. If earnings forecasts slip again, how comfortable does that premium still feel?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this review of Albertsons Companies is mixed, so move quickly, pull up the full data set, and weigh the 2 key rewards and 4 important warning signs.
Ready For More Investment Ideas Beyond Albertsons Companies?
Do not stop with Albertsons Companies. Broaden your watchlist now with fresh opportunities other investors may be overlooking, before momentum shifts and prices move away from you.
- Target resilient income by scanning companies screened as potential 8 dividend fortresses that aim to pair higher yields with balance sheet support.
- Hunt for mispriced potential using the curated 20 high quality undiscovered gems that focuses on quality fundamentals the wider market may have overlooked so far.
- Prioritise capital preservation first with the carefully filtered 31 resilient stocks with low risk scores that highlights businesses assessed to have more durable financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com