


SK hynix has delivered very strong returns in recent years, so the key issue now is whether the current share price is properly grounded in the earnings it produces.
- Over the past 5 years, SK hynix has logged a very large gain of about 19x, which puts real pressure on the question of how much profit the business can sustainably generate.
- The company’s fortunes are closely tied to the economics of memory and storage, so shifts in pricing power, production costs and capacity decisions can materially change how much earnings support the present market value.
- The analysts covering SK hynix have run their own numbers. See what analysts think SK hynix's shares could be worth.
For investors, the debate is whether SK hynix’s current earnings and the expectations embedded in them are enough to justify the latest valuation multiples.
If you want to stress test SK hynix’s valuation question against a wider field, compare it with companies in the 185 high quality undervalued stocks.
Is SK hynix Still Cheap on Earnings?
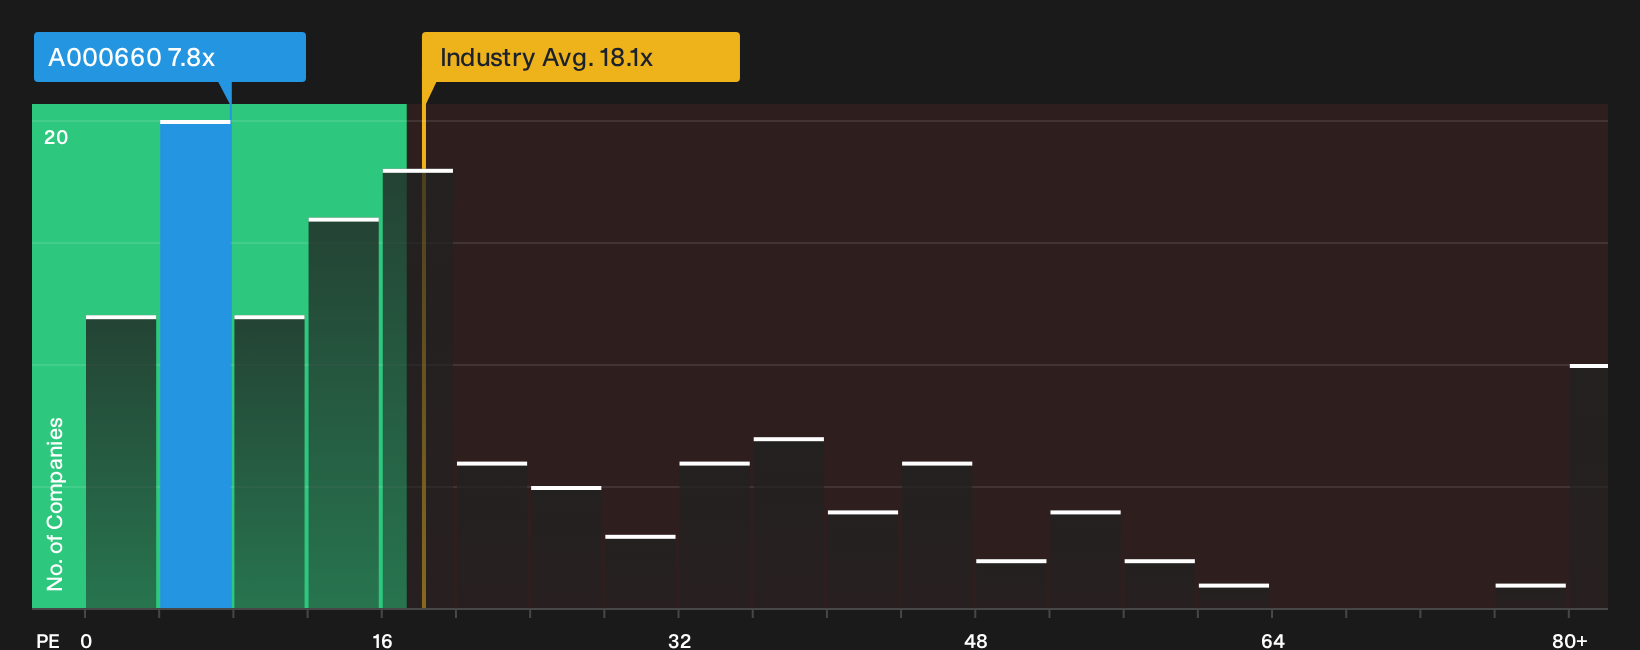
The P/E ratio fits SK hynix because earnings still anchor how investors frame returns on heavy chipmaking investment. On this measure, the stock trades on about 7.8x earnings, compared with roughly 14.7x for peers in its comparison group and around 18.1x for the wider semiconductor sector.
That gap is wide, and the fair-value model that blends SK hynix’s growth profile, profitability, size and risk suggests the shares trade below the multiple that would usually line up with those fundamentals. For you as a shareholder, the key question is whether current profits and cycle risk justify that discount or whether the market is underpricing the business relative to what its earnings power might support over time. Explore the numbers behind SK hynix's P/E valuation.
The SK hynix Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where SK hynix's valuation puzzle leaves off and explain which earnings, margin and growth paths would need to unfold for the stock to be worth materially more or less than today’s price on the Community page. Each scenario links a fair value estimate to a clear storyline about SK hynix's possible catalysts and key risks so you can monitor over time which version of events comes closer to reality.
Bulls and bears on SK hynix are looking at the same AI memory story but drawing very different conclusions about how much is already reflected in the price.
Bull case: 64% undervalued
"Expanded multiyear memory supply agreements that now include around 10 customers with deposit backed purchase commitments are giving SK hynix clearer volume visibility..."
Discover why this Narrative puts SK hynix at 64% undervalued.
Bear case: 12% overvalued
"Intensifying geopolitical tensions, including tightening US export controls on China and persistent trade frictions, could severely restrict SK hynix's access to key international markets..."
Explore why this Narrative puts SK hynix at 12% overvalued.
One more SK hynix factor worth checking before you move on
Before closing the file on SK hynix, it is worth asking who is actually steering this enterprise and how their pay packets line up with the risks you are taking. See who runs SK hynix and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com