


Oil is back on every front page, with Brent above $100 and WTI near $90 as supply routes through the Middle East look more fragile and stockpiles stay tight. That kind of squeeze can quickly reshuffle winners and laggards across global energy. If you care about how this shock ripples into your portfolio, keep reading. Three large integrated oil and gas stocks exposed to this story are up next.
The three stocks covered below are just a sample, with the full screen surfacing 18 more large integrated producers with equally compelling stories that are not detailed in this article. If you want to identify which of these giants best matches your own risk, income and size preferences, head straight to the Global Integrated Oil & Gas Producers screener to filter and analyze potential high conviction ideas.
Vietnam National Petroleum Group (HOSE:PLX)
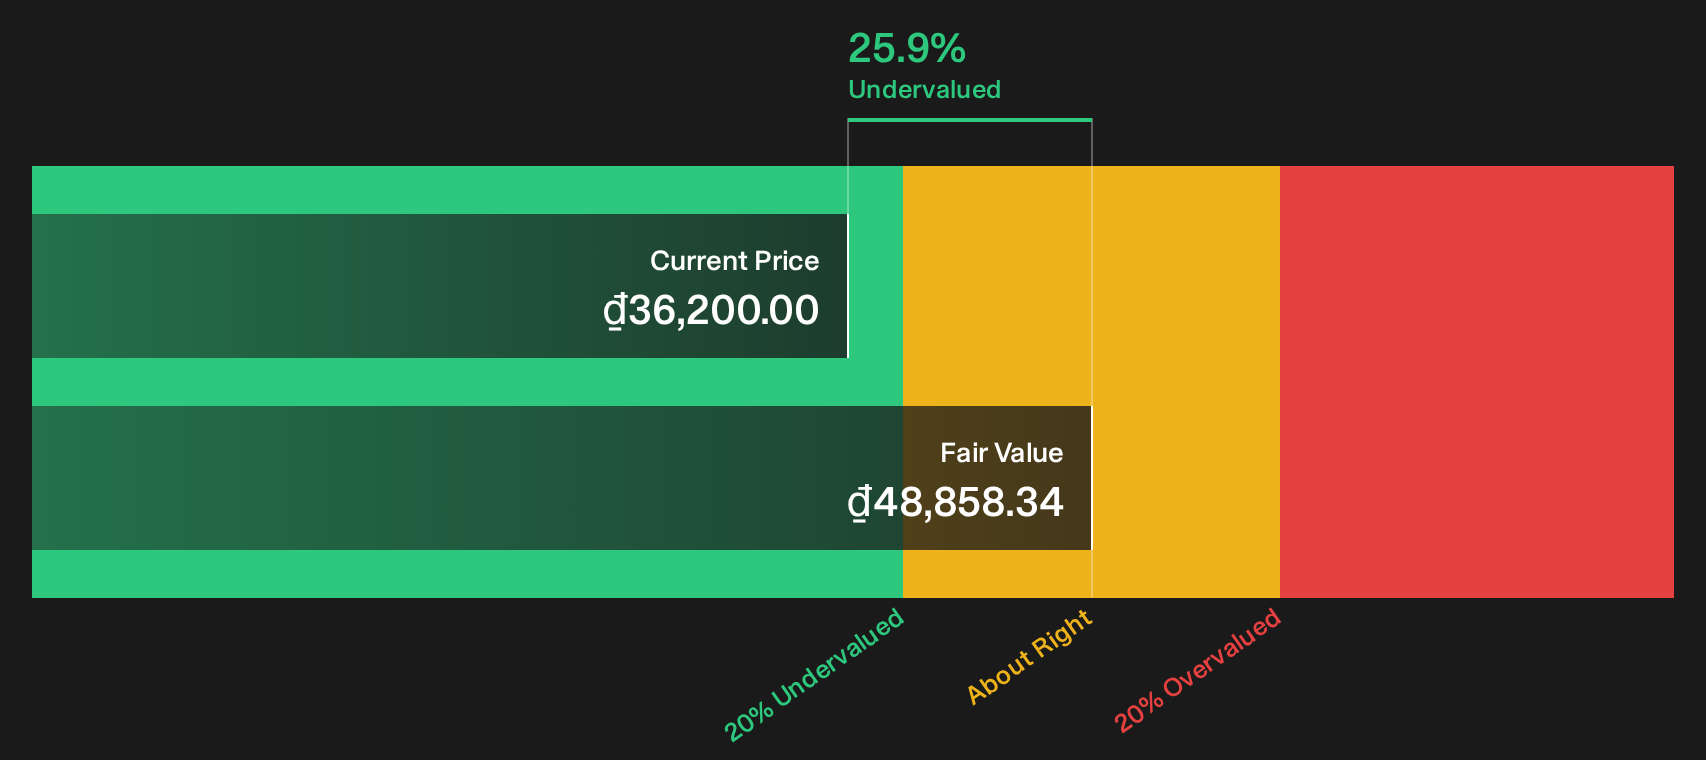
Vietnam National Petroleum Group is a heavyweight in the Global Integrated Oil & Gas Producers theme, importing, exporting and trading fuel while also handling LPG, lubricants, petrochemicals and transport services. Petroleum member companies contribute about ₫256.9 trillion and non petroleum units about ₫213.0 trillion in revenue, backing a roughly ₫45.0 trillion market cap.
Vietnam National Petroleum Group provides exposure to refined product pricing rather than crude production, with large petroleum trading units and petrochemical lines doing the heavy lifting. In this screener, it is positioned as a relatively clear way to focus on fuel margins, although a single shift in funding costs could matter far more than headline oil prices.
That funding sensitivity makes it worth scanning the Vietnam National Petroleum Group financial health report before oil volatility masks what is really driving Vietnam National Petroleum Group.
China Suntien Green Energy (SEHK:956)
China Suntien Green Energy gives you cleaner energy exposure inside a heavy fossil fuel screener, with a mix of wind farms, photovoltaic projects and a large gas distribution arm that looks more like traditional midstream. Around CN¥19.5b comes from natural gas and CN¥9.4b from wind and PV, backing a roughly HK$26.6b market value.
For a screen built around large integrated oil and gas producers, China Suntien Green Energy offers a different angle. You still get natural gas pipelines, LNG terminals and refueling stations that feel familiar to midstream investors, but they sit alongside sizeable wind and solar assets that lean into the energy transition story.
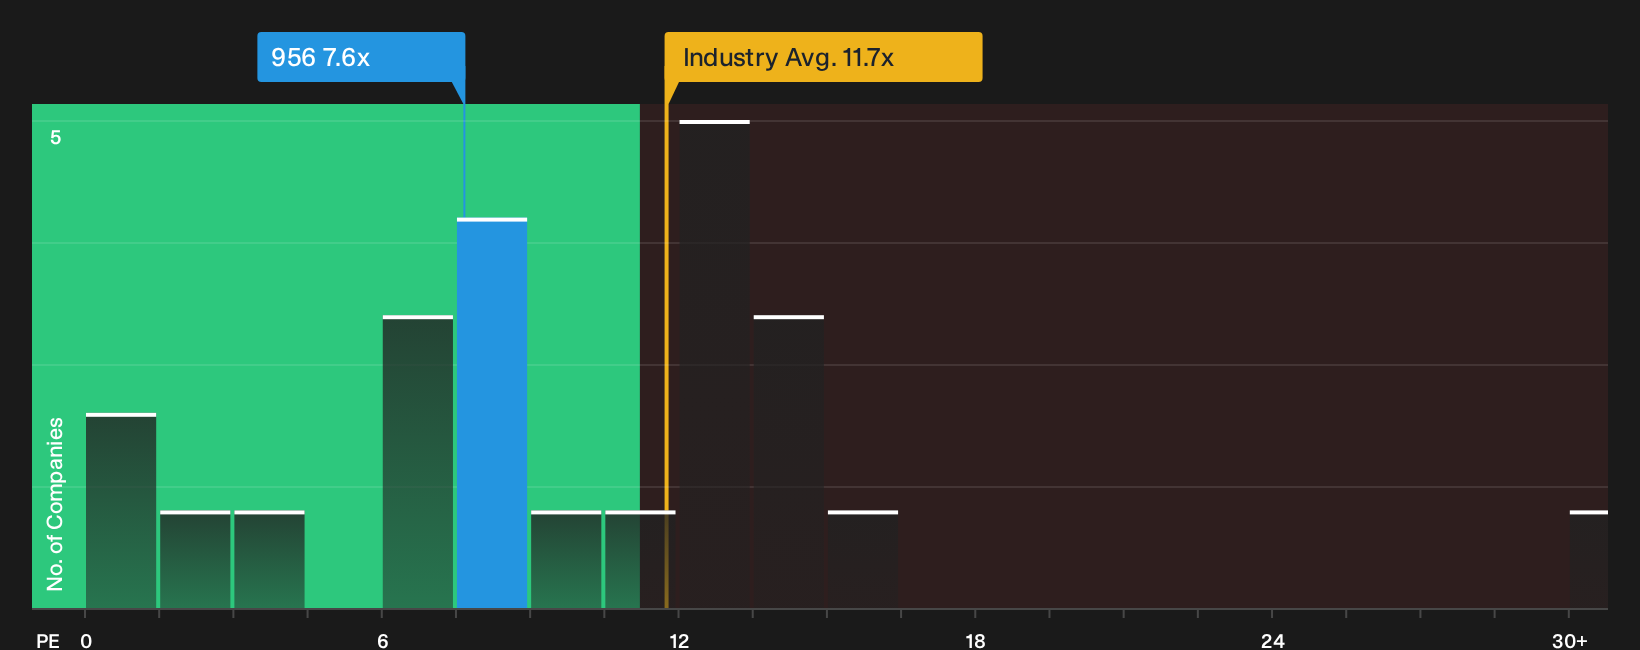
Rising oil prices and tighter seaborne crude flows put more attention on gas and power infrastructure. China Suntien Green Energy operates at scale in Mainland China. The stock trades on a P/E of 7.6x with a 7.09% dividend yield, which raises the question of what happens if one unseen pressure on cash generation persists longer than the market expects.
If that pressure matters to you, run an instant sense check with the 3 key rewards and 2 important warning signs (1 is major!) to see what the market might be overlooking.
Channel Infrastructure NZ (NZSE:CHI)
Channel Infrastructure NZ gives this integrated energy screen a pure infrastructure angle, with nationally important fuel terminals and pipelines linking directly to refined product flows rather than oil production itself. That is where throughput volumes, long contracts and a single country footprint start to matter.
Channel Infrastructure NZ earns about NZ$142.9 million from its infrastructure operations in New Zealand, including fuel import terminals, storage and pipelines, and has a market cap near NZ$1.5b.
"New and extended multi year storage contracts, including the Transmix contract and the nine year extension adding a total of about $170 million of contracted revenue, provide high visibility of cash flows and support sustained EBITDA and dividend capacity."
What happens if a single shift in customer demand changes how much of that infrastructure actually gets used over the next few years?
That demand risk is exactly where the story gets interesting, and the full narrative for Channel Infrastructure NZ shows how Channel Infrastructure NZ could keep cash flows resilient if volumes stall or accelerate.

Seeking Alternatives Before The Crowd?
Fresh themes can move quickly. Breakout sectors may be advancing before most investors even notice, while early pricing still matters. Scan these under the radar ideas now to explore potential opportunities at an earlier stage.
- Target resilient income streams by reviewing the 225 dividend fortresses before yields change as more investors focus on the same cash flow.
- Spot new AI momentum and track the 35 profitable AI stocks that aren't just burning cash while these operators are growing without relying on large, ongoing capital needs.
- Follow infrastructure-related opportunities and assess the 43 power grid technology and infrastructure stocks while upgrades, expansion and grid hardening remain less widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com