


Arm Holdings has delivered a huge multi year run. With the share price now well above where it listed, the real question for investors is whether that jump still lines up with the company’s book value.
- Over the past 3 years, Arm Holdings has returned about 438.4%, which puts a lot of pressure on its balance sheet metrics to support today’s valuation debate.
- Ongoing legal disputes with Qualcomm over royalties and licensing terms may influence how investors think about the durability of Arm’s future cash flows and the value currently sitting on its balance sheet.
- There is a second opinion on Arm Holdings worth weighing. See what analysts think Arm Holdings's shares could be worth.
For investors, the debate is whether Arm Holdings’ current share price can be squared with its book value when compared with the industry average.
If you want a broader starting point for ideas around Arm Holdings and other chip stocks, run the same book value question through 92 AI infrastructure stocks.
Is Arm Holdings Getting Expensive on Book Value?
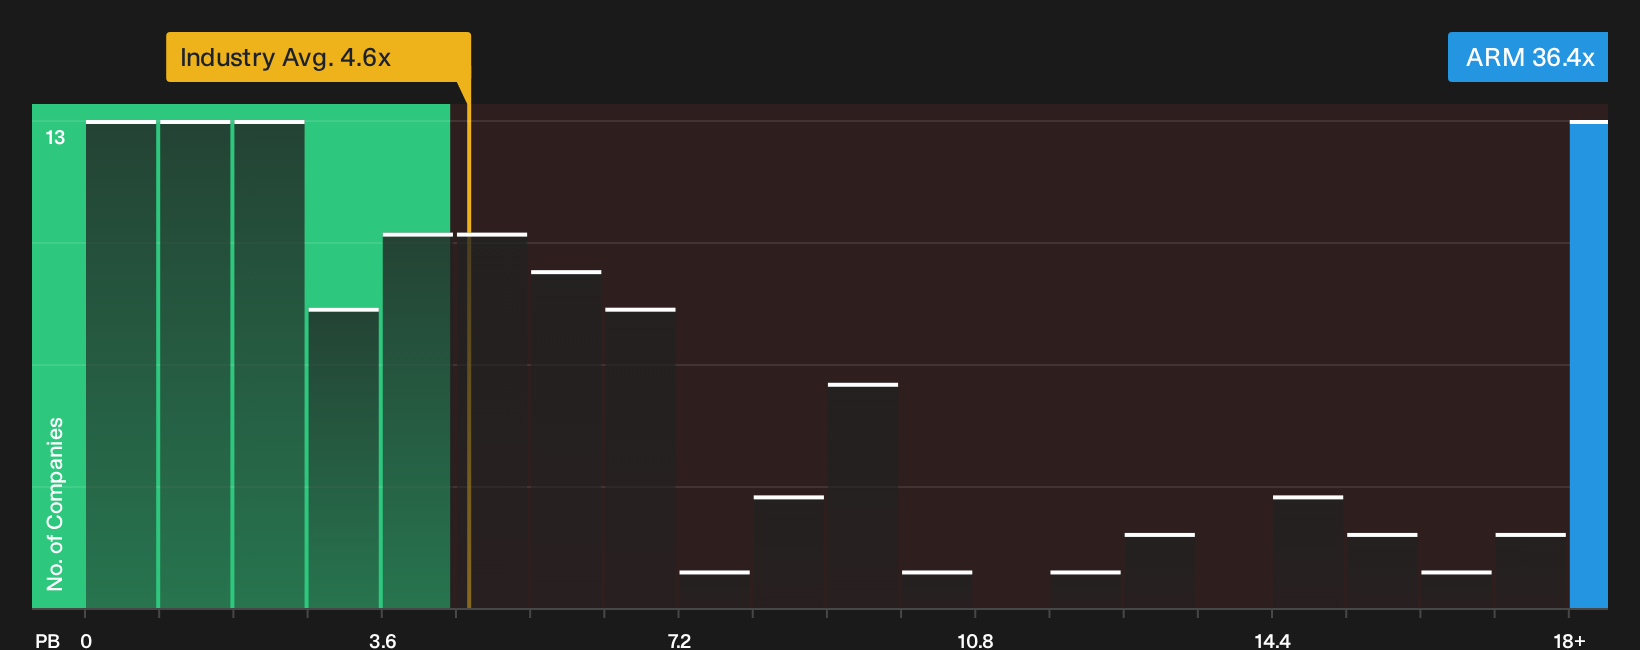
P/B suits Arm Holdings because the group is still heavily defined by its licensing assets and intellectual property base. On this metric, the stock trades on a P/B of about 36.4x, against an industry average near 4.6x and a peer group closer to 10.2x. That is a very wide premium for a semiconductor business whose balance sheet is already reflecting years of investment in chip designs and licensing rights.
Recent enthusiasm around AI demand and Arm’s move into manufacturing has lifted sentiment, yet the current P/B multiple still prices the stock far above typical sector levels despite the ongoing Qualcomm royalty dispute. For you as a shareholder or potential buyer, the key question is whether Arm’s future licensing power and cash generation can justify paying more than 3x the peer P/B, or whether the valuation is running ahead of what the existing equity base can support. Explore the numbers behind Arm Holdings's P/B valuation.
The Arm Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Arm Holdings pick up where that price to book puzzle leaves you. They spell out which future paths for growth, margins and earnings would need to hold for Arm Holdings' valuation to look meaningfully higher or lower than today. Each narrative treats fair value as a hypothesis about the business that can be revisited over time, so you can see how the story holds up as new information arrives.
The community is broadly constructive on Arm Holdings, yet one camp sees extra upside while the other thinks the current price already bakes in a lot.
Bull case: 32% undervalued
"If AGI CPU works, Arm can capture full chip-level revenue in the AI data-center market, which is a massive TAM expansion…"
Discover why this Narrative puts Arm Holdings at 32% undervalued.
Bear case: roughly fairly valued
"The current valuation depends on Arm Holdings continuing to deliver high royalty and licensing growth while sustaining strong operating margins…"
Explore why this Narrative puts Arm Holdings at roughly fairly valued.
One more Arm Holdings angle worth checking before you move on
Price to book tells you what the market is paying for Arm Holdings today. The next layer is seeing where professional forecasts think this business could be a few years from now. Explore where analysts expect Arm Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com