


- Centrus Energy recently signed a multi-year agreement to supply High-Assay Low-Enriched Uranium to Antares Nuclear and is progressing its licensed HALEU production facility in Ohio toward commercial scale.
- The combination of a contracted HALEU offtake partner and a licensed Western production site directly links Centrus Energy’s capital projects to visible demand for advanced nuclear fuel.
- We will now look at how this new HALEU supply agreement could reshape Centrus Energy's existing investment narrative and risk profile.
Scan beyond Centrus Energy and see which other nuclear fuel and infrastructure stocks are already on the radar in our curated 16 nuclear energy infrastructure stocks.
Centrus Energy Investment Narrative Recap
Centrus Energy is a bet on sustained demand for LEU and HALEU, along with its ability to turn technical capability at the American Centrifuge Plant into consistent, contract backed output. To stay comfortable as a shareholder, you need to believe that the current backlog, HALEU positioning, and strong cash balance can offset modest forecast revenue and earnings growth.
The key near term catalyst is clear progress in scaling licensed HALEU production and converting that into more long term offtake deals. The biggest risk is execution. Delays, higher costs, or slower utility contracting would matter more than this single Antares agreement, so the recent news mainly refines, rather than rewrites, that set up.
The upcoming presentation at the ROTH Critical Mass in Emerging Nuclear Technology Conference gives Centrus Energy a public stage to explain how the Antares HALEU contract fits alongside its US$3.6b backlog and plans for commercial scale output in Ohio. Investors will be listening for concrete detail on timelines, capital needs, and contract structures.
There is also a chance to hear how management views softer near term analyst forecasts, including expectations for slower revenue growth, margin pressure from 24% to 10.2%, and lower forecast returns on equity. Any additional colour on how the firm aims to use its US$833m cash position, secure funding support, and manage construction and staffing risk will be important context for the current catalyst and the downside scenario.
Centrus Energy's current analyst narrative points to revenues of US$477.1 million and earnings of US$34.3 million by 2029, with revenue described as remaining fairly flat and profit margins moving from 10.2% today to 7.2% over roughly the same period. That implies earnings today of US$48.5 million and an earnings decline of US$14.2 million by the 2029 forecast year.
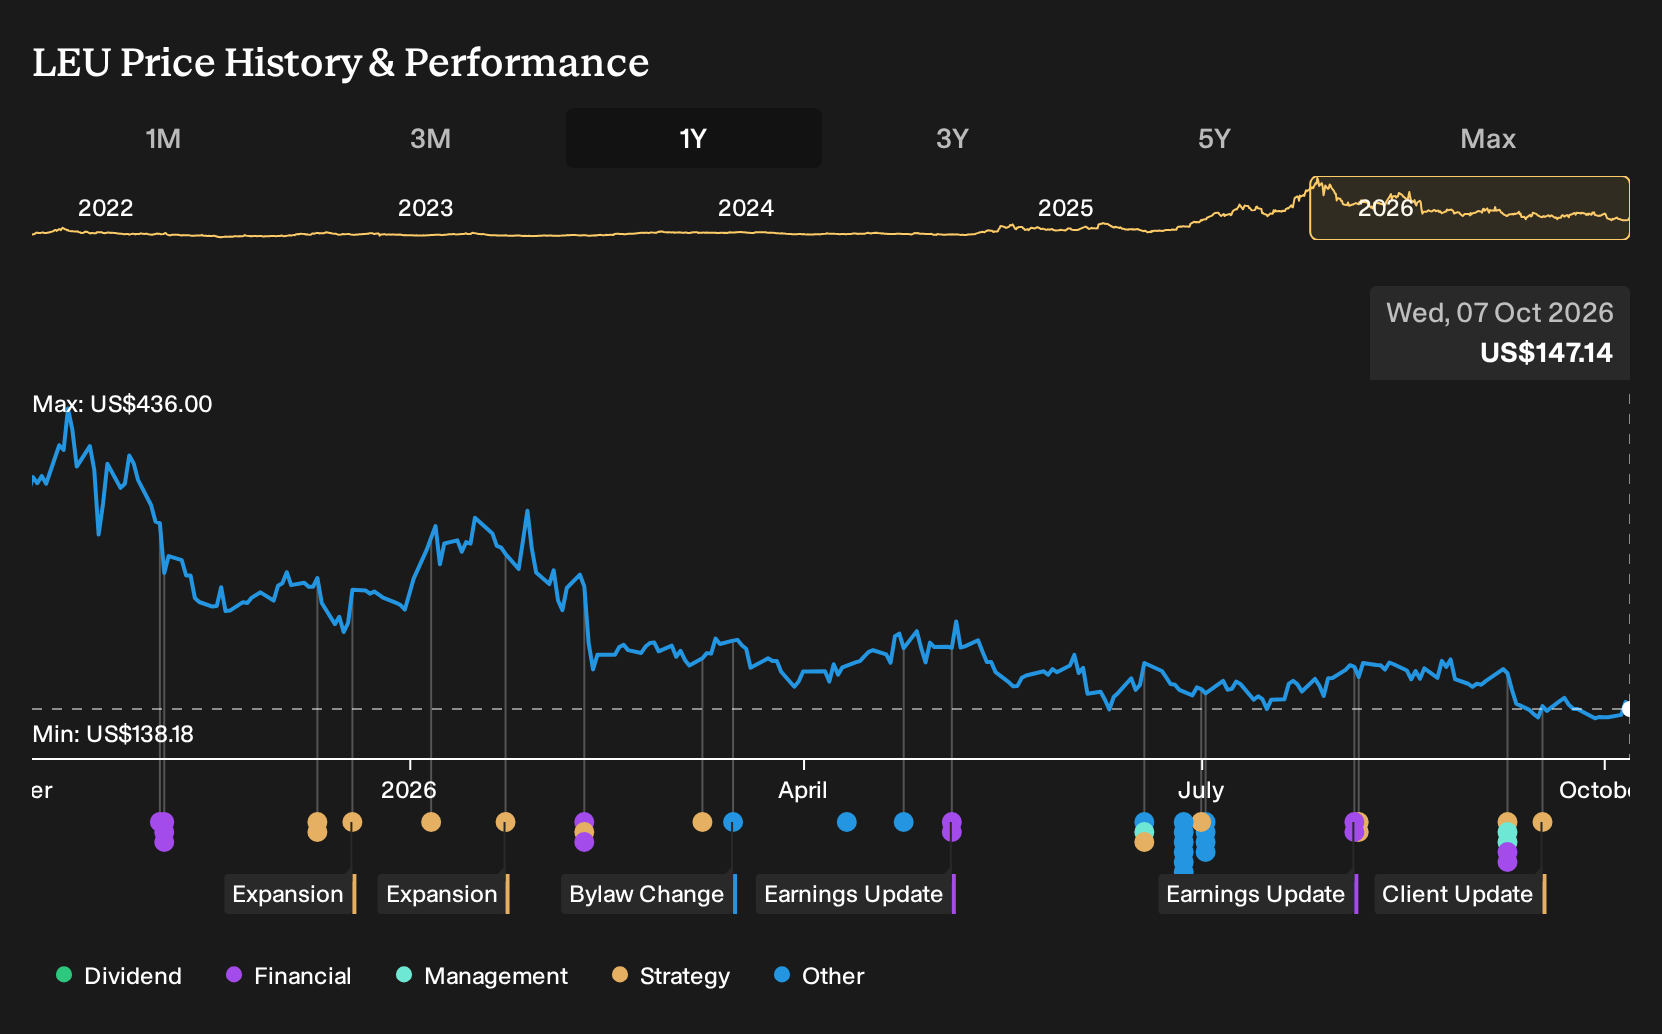
Discover why Centrus Energy's fair value indicates a 75% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
The lowest analysts focus on dilution risk. They argue Centrus Energy might grow its project pipeline while leaving each share with less of the pie. Their earlier forecasts pencilled in revenue of about US$126.6 million and earnings of US$25.5 million by 2029, far below consensus. As a result, the new Antares HALEU deal could eventually shift that story.
Explore 5 other Centrus Energy fair value estimates, including one that suggests it could be worth just $190.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Centrus Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Centrus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centrus Energy's overall financial health at a glance.
Looking for more Centrus Energy style investment ideas?
If Centrus Energy has sharpened your interest in nuclear fuel and related infrastructure, it can be useful to widen the lens and line it up against other opportunities on the Simply Wall St Screener.
Here are a few angles you can use to round out your watchlist.
- If resilience and lower volatility matter to you, start with a basket of companies that screen well on financial risk using our 31 resilient stocks with low risk scores.
- If balance sheet strength is your first filter, narrow the field to businesses with robust cash and debt profiles by running the list of solid balance sheet and fundamentals (25 results).
- If you want to fish where fewer investors are looking, focus on under-followed opportunities with solid fundamentals through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com