


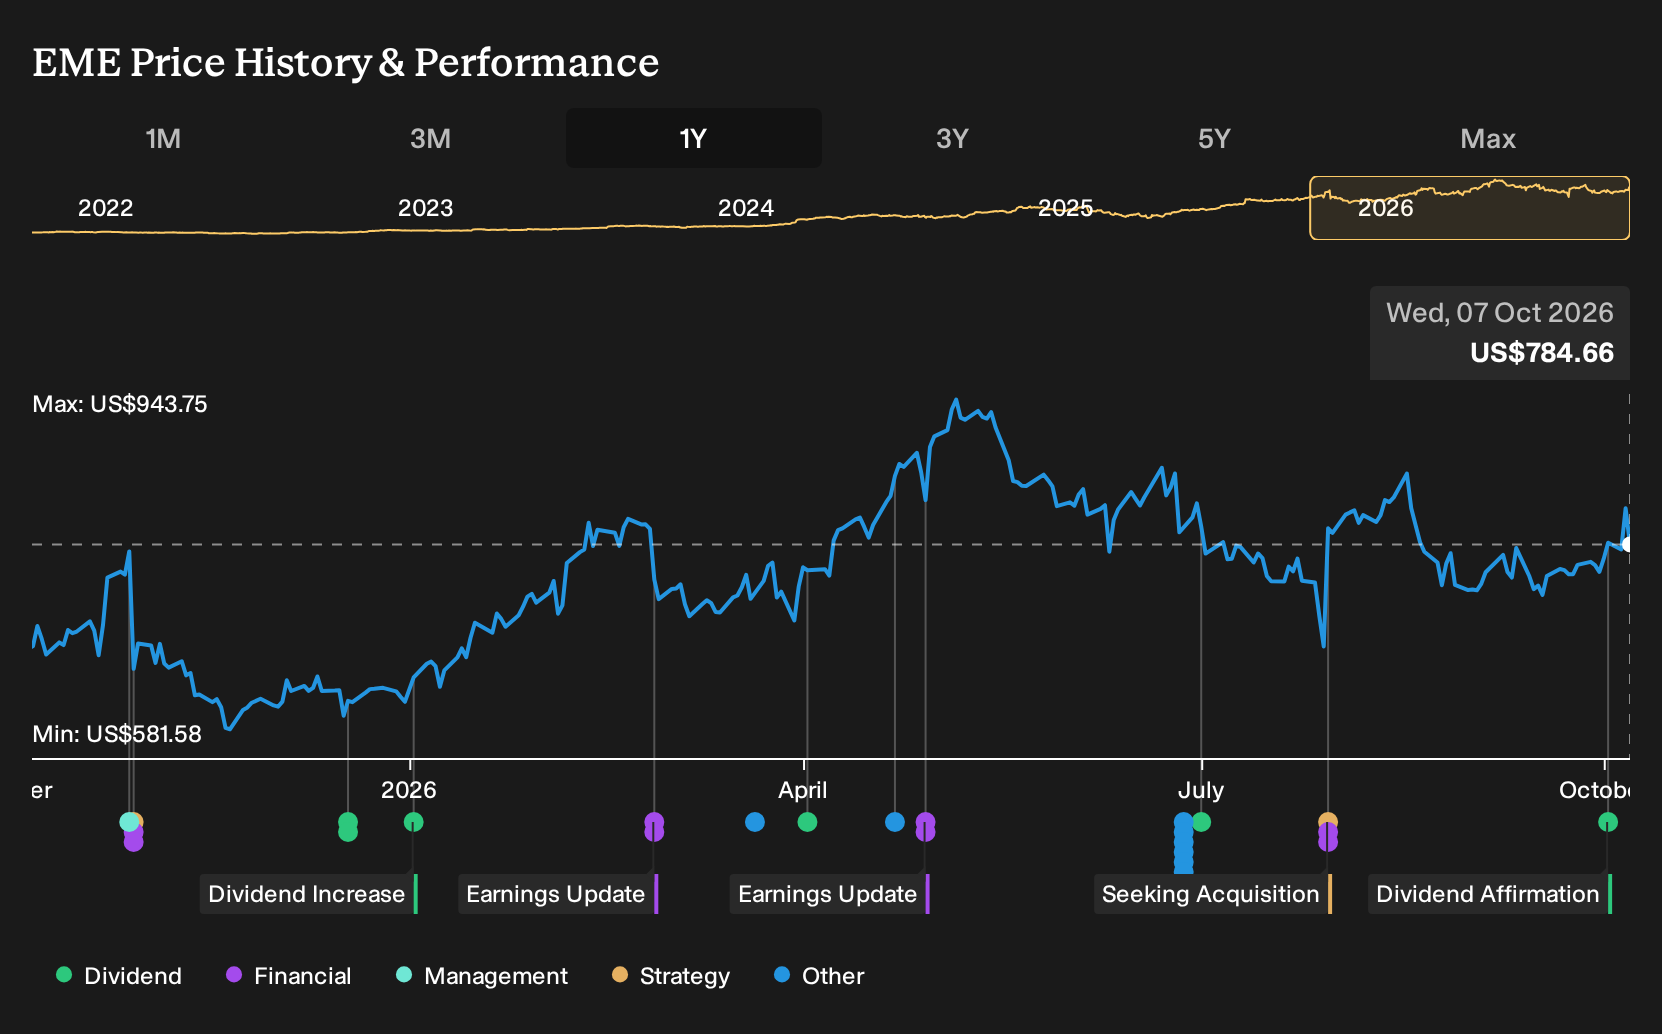
- EMCOR Group declared a regular quarterly cash dividend of US$0.40 per share, paid on October 30, 2026, to shareholders of record on October 15, 2026.
- Strong revenue expansion, faster earnings per share growth supported by buybacks, and rising returns on capital illustrate how EMCOR Group is using capital deployment and operations to reinforce its business momentum.
- We will now look at how EMCOR Group's rising returns on capital could influence the investment narrative around its recent dividend.
Scan how EMCOR Group's dividend story and capital efficiency compare with other contractors and infrastructure players by reviewing our hand picked 43 power grid technology and infrastructure stocks in one place.
EMCOR Group Investment Narrative Recap
For EMCOR Group, the core belief as a shareholder is that the record Remaining Performance Obligations, data center exposure, and recent acquisitions can be converted into steady earnings without eroding profitability. The recent US$0.40 dividend fits that picture as a routine use of cash, and it does not materially change project execution risk or upside from the current backlog.
The near term swing factor is whether EMCOR Group can keep margins resilient while labor costs, contract mix, and integration work stay complicated. The biggest operational risk remains pressure on Mechanical Construction margins from more prime roles and GMP or cost plus contracts if productivity tools and prefabrication do not offset higher costs.
The fresh quarterly dividend declaration is the most relevant development for this story. It signals that EMCOR Group continues to distribute some of its cash flow, even as it funds buybacks, prefabrication investments, and integration of acquired electrical contractors. For income focused holders, that matters less for yield and more as a signal of balance sheet comfort and consistency.
For catalyst driven investors, the dividend itself is secondary to whether EMCOR Group can keep translating its US$17.14b Remaining Performance Obligations into earnings while maintaining a reported Return on Equity of 35.3%. If labor pressures or contract mix compress margins, the dividend will not offset that risk, but it could highlight management confidence in ongoing cash generation.
What EMCOR Group's Forecasts Suggest About Earnings Power
EMCOR Group's current consensus framework points to revenues of US$25.3b and earnings of US$2.0b by 2029. This is underpinned by an assumed 10.9% yearly top line expansion and a shift from US$1.4b in earnings today, which implies an increase of about US$0.6b over the period.
Uncover why EMCOR Group's fair value points to a 32% potential upside to its current price, which could narrow quickly as expectations reset.
Exploring Other Perspectives
One bearish angle on EMCOR Group focuses on automation and prefabrication potentially capping long term demand for traditional services. The lowest analysts were already pencilling in 7.8% annual revenue growth and about US$23.3b of sales with US$1.7b of earnings by 2029. Those forecasts pre date this dividend news, so viewpoints could shift.
Explore 5 other EMCOR Group fair value estimates, including one that suggests it could be worth just $885.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your EMCOR Group research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for EMCOR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EMCOR Group's overall financial health at a glance.
Looking For More EMCOR Group Sized Ideas?
If EMCOR Group has sharpened your focus on execution, balance sheets, and reliable cash generation, use that same lens to scan a wider watchlist. The Simply Wall St Screener can help you quickly filter for businesses that match the kind of risk and return profile you want to research next.
- For investors who care most about quality at a reasonable entry point, start with a curated set of 29 high quality undervalued stocks that pair fundamentals with pricing that may warrant a closer look.
- If steady income is a priority, shift attention to companies in the 8 dividend fortresses that currently offer higher yields while still passing basic financial health checks.
- When capital protection comes first, scan the 31 resilient stocks with low risk scores and focus your research on businesses with balance sheets and risk profiles that may feel more comfortable through different market conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com