


Gorman-Rupp (GRC) has recently drawn attention after a sharp 3.9% one day decline, prompting investors to reassess what the recent pullback and longer term return profile might mean for the stock.
Set against a year-to-date share price return of 54.15% and a 1-year total shareholder return of 63.01%, Gorman-Rupp’s recent 6.54% three month share price pullback signals fading short term momentum, while longer term performance, including a 138.79% three year total shareholder return, remains strong.
Scan beyond Gorman-Rupp’s surge and pullback by lining up its performance against a curated group of 29 high quality undervalued stocks that also combine solid cash generation with resilient balance sheets.
Gorman-Rupp has delivered robust multi year returns, yet the recent pullback raises a sharper question. Is a solid pump manufacturer now trading on an attractive valuation, or has the price already baked in the quality?
Preferred Price-to-Earnings of 31.4x: Is it justified?
Gorman-Rupp now trades on a P/E of 31.4x, which sits above both its Machinery industry average and its own estimated fair ratio, even after the recent pullback from $74.21.
The P/E multiple compares what investors are currently paying for each dollar of earnings. For a manufacturer of pumps and pump systems like Gorman-Rupp, that figure often reflects expectations around earnings durability, order visibility, and how cyclical customers in water, wastewater, construction, and industrial markets might be.
Gorman-Rupp has grown earnings by 20.3% over the past year and by 22.1% per year over the past 5 years, and its earnings are forecast to grow 18.55% per year. That profile can help explain why the market is willing to pay a premium multiple today, although the current P/E of 31.4x is materially higher than the estimated fair P/E of 22x. The valuation work suggests the share price could move toward that level if expectations cool.
Compared to the broader US Machinery industry average P/E of 25x, Gorman-Rupp trades at a clearly richer valuation. The stock is priced at a premium to both its sector and the estimated fair ratio, which signals that investors are placing a higher value on its earnings strength and quality than on the typical peer.
Explore the SWS fair ratio for Gorman-Rupp.
Result: Price-to-Earnings of 31.4x (OVERVALUED)
Still, Gorman-Rupp’s premium 31.4x P/E could reset quickly if earnings forecasts soften or if demand from key industrial and construction customers cools.
Find out about the key risks to this Gorman-Rupp narrative.
Another View on Gorman-Rupp’s Value
The P/E premium suggests Gorman-Rupp appears expensive, but the SWS DCF model presents a different perspective. At $74.21, the shares are assessed as trading below an estimated future cash flow value of $115.85, which indicates potential undervaluation rather than excess pricing.
That kind of gap can reflect optimism embedded in near term earnings multiples while long run cash flow assumptions remain more conservative, or simply a market that has not fully repriced the stock. Which version of value you rely on more will shape how you interpret the recent pullback, either as a potential opportunity or a possible warning sign.
Look into how the SWS DCF model arrives at its fair value.
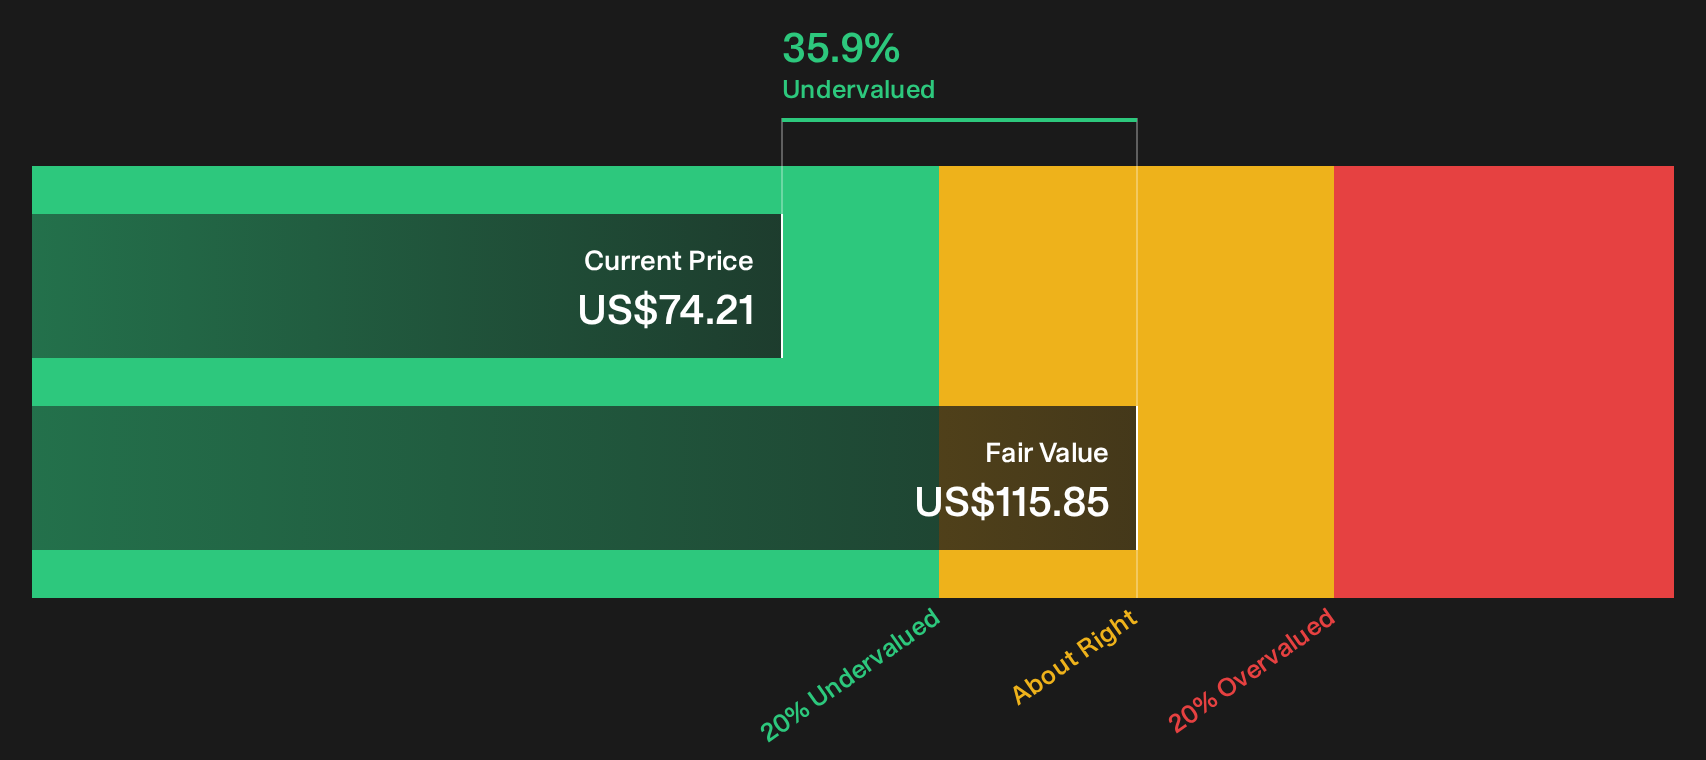
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Gorman-Rupp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a simple reset around Gorman-Rupp. If the mix of risks and rewards feels finely balanced, consider acting before sentiment moves on without you and weigh both sides through the 3 key rewards and 2 important warning signs
Looking for more Gorman-Rupp sized investment ideas?
If Gorman-Rupp has you thinking harder about price, quality, and timing, do not stop at a single ticker. Broaden your watchlist now and give yourself more options when market sentiment shifts.
- Target resilience first and stress test your portfolio using a 31 resilient stocks with low risk scores that focuses on businesses with more measured risk profiles.
- Hunt for mispriced quality and stack your watchlist with a 20 high quality undiscovered gems before the crowd starts paying closer attention.
- Reinforce income potential and focus on cash returns to shareholders with a 8 dividend fortresses that screens for higher yielding payers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com