


Permian Basin Royalty Trust (PBT) has drawn fresh attention after a recent price move left the units around $33.60, with performance over the past 3 months and year catching investor interest.
Recent trading suggests momentum around Permian Basin Royalty Trust is still intact. The latest 7 day share price return of 6.73% comes after a 90 day share price gain of 27.71%, while the 1 year total shareholder return of 100.34% points to strong longer term performance, even with a modest 30 day share price pullback of 1.70%.
Scan how Permian Basin Royalty Trust compares with other energy plays showing strong price action by reviewing the hand picked 29 high quality undervalued stocks.
Permian Basin Royalty Trust has surged, yet its intrinsic value estimate currently points to a slight premium instead of a discount. Is the recent enthusiasm running ahead of what the underlying royalties justify, or is it only slightly ahead?
Price-to-Earnings of 96.6x: Is it justified?
On simple valuation terms, Permian Basin Royalty Trust looks expensive. The trust trades at a P/E of 96.6x, which sits well above many investors' comfort zones when lining that figure up against a last close of $33.60.
The P/E ratio compares what you pay per unit today to the earnings the trust generates per unit over the last year. For a royalty vehicle like Permian Basin Royalty Trust, this matters because distributions and long term appeal are closely linked to the underlying earnings power that the royalties produce.
Recent data points do not point to a growth story backing that high multiple. Earnings have declined by 2.6% per year over the past 5 years, and profit fell 1.7% over the last year. That means the very high P/E is being applied to shrinking earnings rather than expanding profits.
The contrast to peers is also stark. PBT's P/E of 96.6x is far higher than both the US Oil and Gas industry average of 12.3x and the peer group average of 14.9x. On these comparisons, the market price places a much richer value on each dollar of profit than is typical across similar energy royalties and producers.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 96.6x
Still, the story around Permian Basin Royalty Trust can quickly shift if commodity prices weaken or if production from its underlying Texas assets trends lower.
Find out about the key risks to this Permian Basin Royalty Trust narrative.
Another view using the SWS DCF model
There is a sharp contrast once you shift from the simple P/E check to the SWS DCF model for Permian Basin Royalty Trust. At a unit price of $33.60, the trust sits well above an estimated future cash flow value of $7.98, which points to a materially overvalued setup on this framework.
That kind of gap matters in practice because it leaves less room for disappointment if royalty income softens or distribution expectations reset. It raises a practical question for unitholders: Is this a premium worth paying, or is it an entry level that calls for extra caution around future cash generation?
Look into how the SWS DCF model arrives at its fair value.
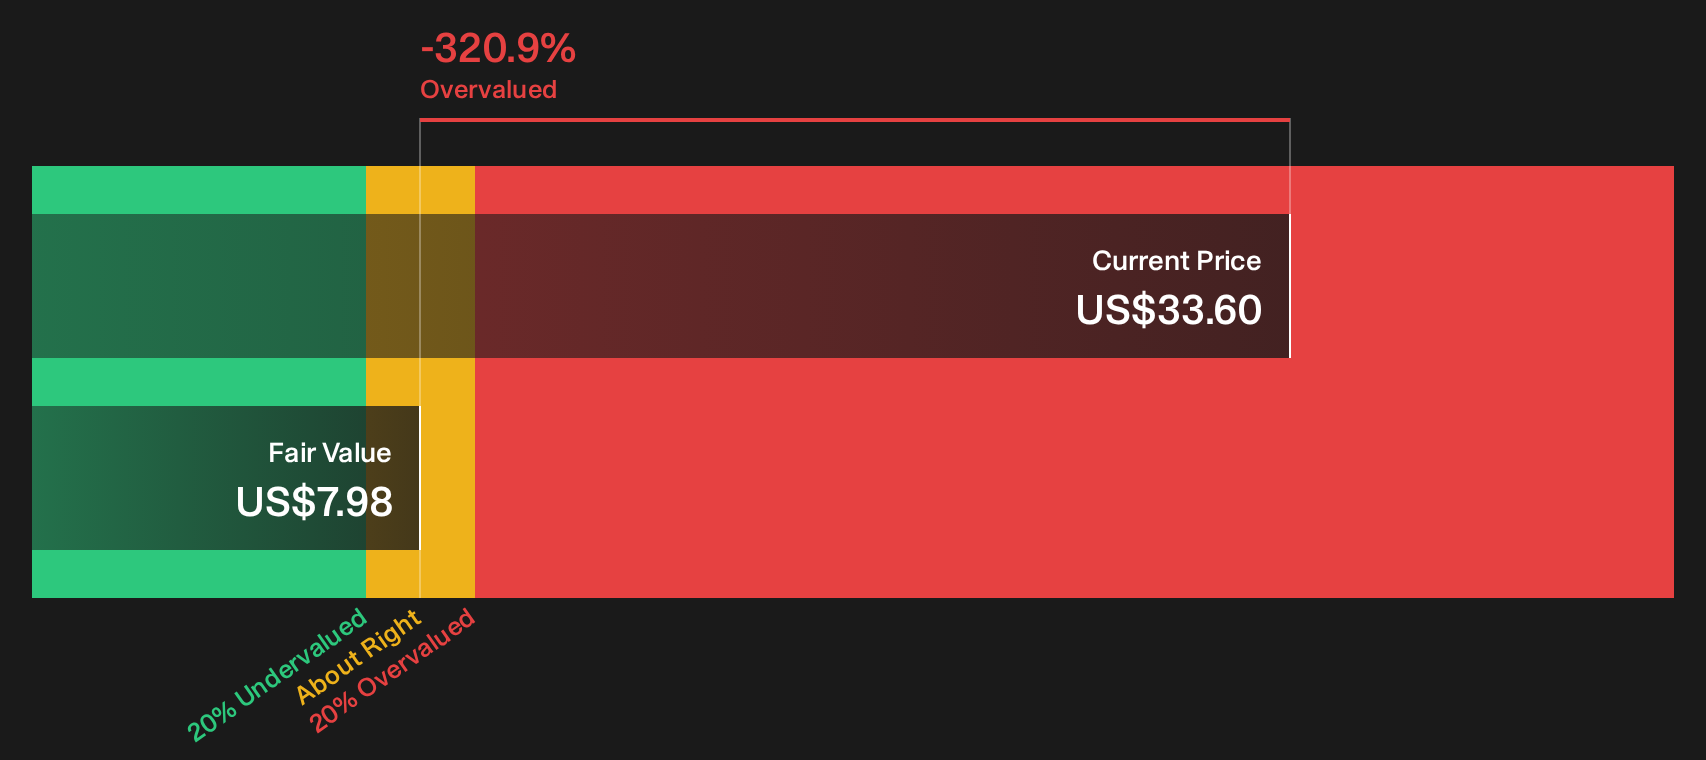
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Permian Basin Royalty Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the tone here feels too cautious or not cautious enough for Permian Basin Royalty Trust? Take a few minutes to review the figures, stress test your own assumptions, and then weigh them against the 1 important warning sign.
Looking for more investment ideas beyond Permian Basin Royalty Trust?
If Permian Basin Royalty Trust has you rethinking valuation, use the Simply Wall St screener to spot fresh opportunities before they move without you.
- Target income resilience by focusing on businesses built around steady cash returns using the 8 dividend fortresses.
- Prioritize capital protection first and growth second with a watchlist built from the 31 resilient stocks with low risk scores.
- Hunt for future leaders hiding in plain sight by scanning the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com