


Safety Insurance Group (SAFT) has drawn fresh attention after recent trading data showed sharp total returns over the past year and past 3 months, prompting investors to reassess this Boston based insurer’s profile.
Recent trading suggests momentum in Safety Insurance Group is building, with a 36.81% 90 day share price return and a 56.49% 1 year total shareholder return, even as the stock now changes hands at US$103.88 per share.
Scan how Safety Insurance Group’s surge compares with other insurers by reviewing a hand picked set of 31 resilient stocks with low risk scores that are moving on solid fundamentals.
After a run like Safety Insurance Group has just delivered, the temptation is to chase the move or wait on the sidelines for a pullback. The valuation work now matters most for deciding which path fits you.
Price-to-Earnings of 22x: Is it justified?
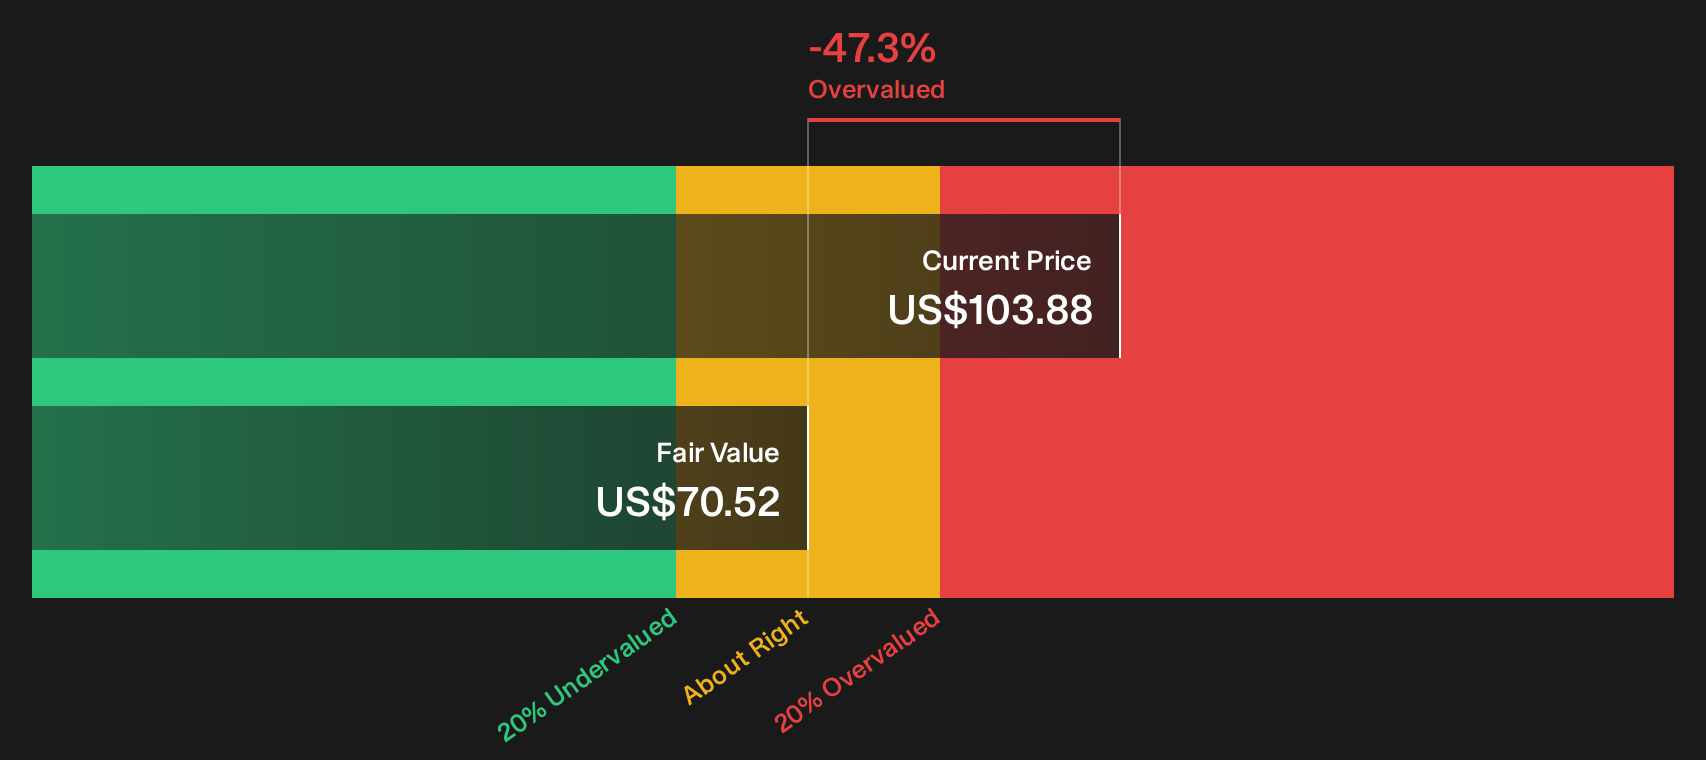
On simple numbers, Safety Insurance Group trades on a P/E of 22x, while our DCF work points to a future cash flow value of $70.52 against the current $103.88 share price. This suggests the market is paying a premium for this insurer.
The P/E ratio compares the current share price with earnings per share. For a business like Safety Insurance Group, which earns through underwriting and investment income, that multiple reflects what investors are willing to pay today for each dollar of current profits.
Context matters for that figure. SAFT's return on equity is described as low at 7.8%, earnings have declined by 12.1% per year over the past 5 years, and net profit margins have slipped from 7.1% to 5.4%. Against that backdrop, a 22x P/E means the market is assigning a much richer tag than the US Insurance industry average of 10.8x and even the peer average of 18.2x. This points to a clearly expensive valuation relative to both its sector and closer comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 22x (OVERVALUED)
Still, Safety Insurance Group depends heavily on the Massachusetts market and on underwriting discipline, so any pricing missteps or regulatory shifts could quickly challenge today’s rich multiple.
Find out about the key risks to this Safety Insurance Group narrative.
Another View Using Our DCF Model
There is a different message coming from the SWS DCF model. On that framework, Safety Insurance Group’s estimated future cash flow value of $70.52 sits well below the current $103.88 share price, which flags the stock as overvalued on this second yardstick too. If both earnings and cash flow signals are this stretched, what kind of scenario are buyers really banking on?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Safety Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment around Safety Insurance Group clearly split, now is the moment to review the underlying numbers yourself and decide where you land on the risk reward balance. To see both sides of that equation in one place, take a look at the 1 key reward and 2 important warning signs.
Looking for more ideas beyond Safety Insurance Group?
If Safety Insurance Group has sharpened your focus on valuations and risk, you can use that momentum to scan fresh opportunities that might better fit your goals today.
- Target reliable cash generators by reviewing a curated set of income focused plays through the 8 dividend fortresses.
- Hunt for potential mispriced opportunities by scanning the 29 high quality undervalued stocks built around quality fundamentals and valuation support.
- Strengthen your watchlist with financially resilient businesses by checking the list of solid balance sheet and fundamentals (25 results) that meet strict balance sheet and fundamentals criteria.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com