


Workday (WDAY) has put benefits and payroll in the spotlight after unveiling Workday Total Benefits, a new AI-driven benefits platform, along with fresh integrations with Experian, Checkr, Block and other ecosystem partners.
Workday’s latest benefits launch comes after a mixed period for investors, with the share price at US$184.26 and a 90 day share price return up 33.19%, but the 1 year total shareholder return down 22.66%. This signals short term momentum alongside weaker longer term outcomes.
Scan how Workday’s AI push compares with other software players by checking the curated 35 profitable AI stocks that aren't just burning cash that already back their tech stories with real earnings power.
For Workday, that sharp 90 day rebound against a weaker 1 year record raises a simple point. Are investors finally tracking the underlying AI and benefits build out, or are they just swinging with sentiment ahead of valuation work?
Most Popular Narrative: 66.5% Undervalued
On Simply Wall St, the most followed Workday narrative from John_Eric pegs fair value at $550.10 per share, compared with the latest close at $184.26, which frames the recent AI benefits push as one chapter in a much larger rerating story.
The multi-year path this points toward is incremental, not speculative. Existing customers expand into agent-based workflows on top of subscriptions they already pay for, backlog continues converting into recognized revenue at a predictable pace, and margin continues widening as the AI investment amortizes across a larger revenue base. The risk case, where agents replace rather than expand the relationship, remains possible, but nothing in this quarter's filing supports it happening yet.
See why 15 investors see Workday as 67% undervalued.
Result: Fair Value of $550.10 (UNDERVALUED)
Still, the Workday narrative could be knocked off course if AI agent adoption slows or if margin targets prove harder to sustain than recent filings suggest.
Find out about the key risks to this Workday narrative.
Another View On What Workday Is Worth
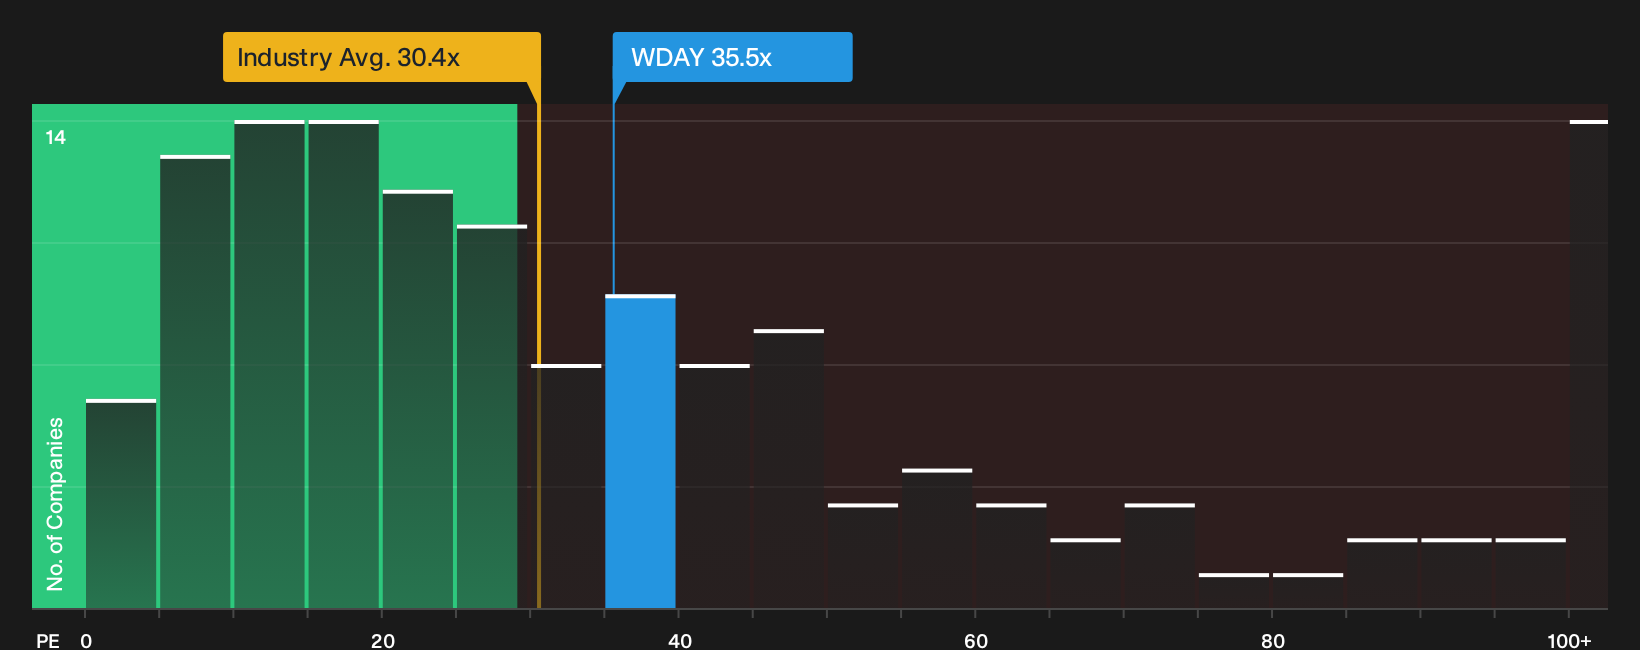
The first narrative leans heavily on cash flows and a detailed SWS DCF model that flags Workday as deeply undervalued. A simpler price check tells a cooler story. The stock trades on a P/E of 35.5x, richer than the US software industry at 30.4x and almost double peer averages around 17.5x, even though the fair ratio model suggests 37.1x is where the multiple could drift toward over time. That mix of discount to one fair value model and premium to current earnings benchmarks leaves a basic question: Are you more comfortable anchoring on cash generation or on what the market is currently willing to pay for similar businesses?
For readers who lean on earnings-based comparisons, the next step is to pressure test whether paying up on the current multiple feels justified by Workday’s profile, or if the gap to peers simply adds valuation risk that needs compensating conviction. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
That mix of optimism and doubt around Workday only matters if you use it as a prompt to test the numbers yourself and move quickly. To pressure test the upbeat angles in more detail, start with the 3 key rewards.
Ready For More Workday-Sized Opportunities?
If Workday has you thinking harder about valuation and AI, do not stop there. The real edge comes from lining up a full bench of ideas.
- Target potential mispricing early by scanning our 29 high quality undervalued stocks that pair solid fundamentals with room for sentiment to catch up.
- Build a steadier income stream by reviewing 8 dividend fortresses that combine higher yields with business models built around ongoing cash returns.
- Protect your downside first by starting with a 31 resilient stocks with low risk scores that screens for balance sheet strength and calmer risk scores before excitement.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com