


- ALK-Abelló expanded its long-running contract manufacturing agreement with Catalent, securing long-term access to Zydis technology and an increase in annual SLIT tablet capacity to an expected 1.1 billion tablets from the early 2030s, backed by around DKK 500 million of capitalised prepayments.
- The group also lifted its 2026 outlook, now guiding for 16 to 17% revenue growth in local currencies and an EBIT margin around 27%, underscoring how tablet demand is feeding through to both scale and operating leverage.
- We will now see how ALK-Abelló's upgraded 2026 revenue and EBIT margin outlook feeds into the broader investment narrative around tablets.
ALK-Abelló Investment Narrative Recap
To own ALK-Abelló, you need to believe the tablet franchise can keep gaining share across allergy segments while newer launches, such as neffy and future food allergy products, gradually broaden the earnings base. The upgraded 2026 outlook, with 16% to 17% revenue growth in local currencies and an EBIT margin around 27%, reinforces that thesis in the near term.
The key short-term catalyst is continued uptake of allergy tablets and adrenaline nasal sprays across regions, which is what current guidance leans on. The biggest risk remains concentration in a relatively narrow set of therapies. Any slower adoption, new competing treatment classes, or pricing pressure could challenge both growth and margin ambitions.
The expanded Catalent agreement is the event that really matters for this story. It locks in Zydis access for ALK-Abelló's existing and potential future tablets, including peanut and tree nut programs, and lifts annual SLIT tablet capacity toward 1.1 billion units from the early 2030s, underpinned by about DKK 500 million of capitalised prepayments.
For you as an investor, that ties directly into catalysts around pediatric respiratory tablets and possible food allergy launches. The deal reduces long-term supply risk and supports scale benefits, while the capitalised payments and future manufacturing cost profile need to be watched closely to see whether execution keeps EBIT margins in line with the 2026 outlook and longer-term targets.
ALK-Abelló's current analyst narrative points to DKK 9.6b in revenue and DKK 2.0b in earnings by 2029, built on assumed yearly top line expansion of 13.6% and an increase in profit from DKK 1.3b today to that 2029 consensus. This implies roughly a 1.5x step up in earnings over the period.
Uncover why ALK-Abelló's fair value indicates a 36% potential upside to its current price that could narrow quickly.
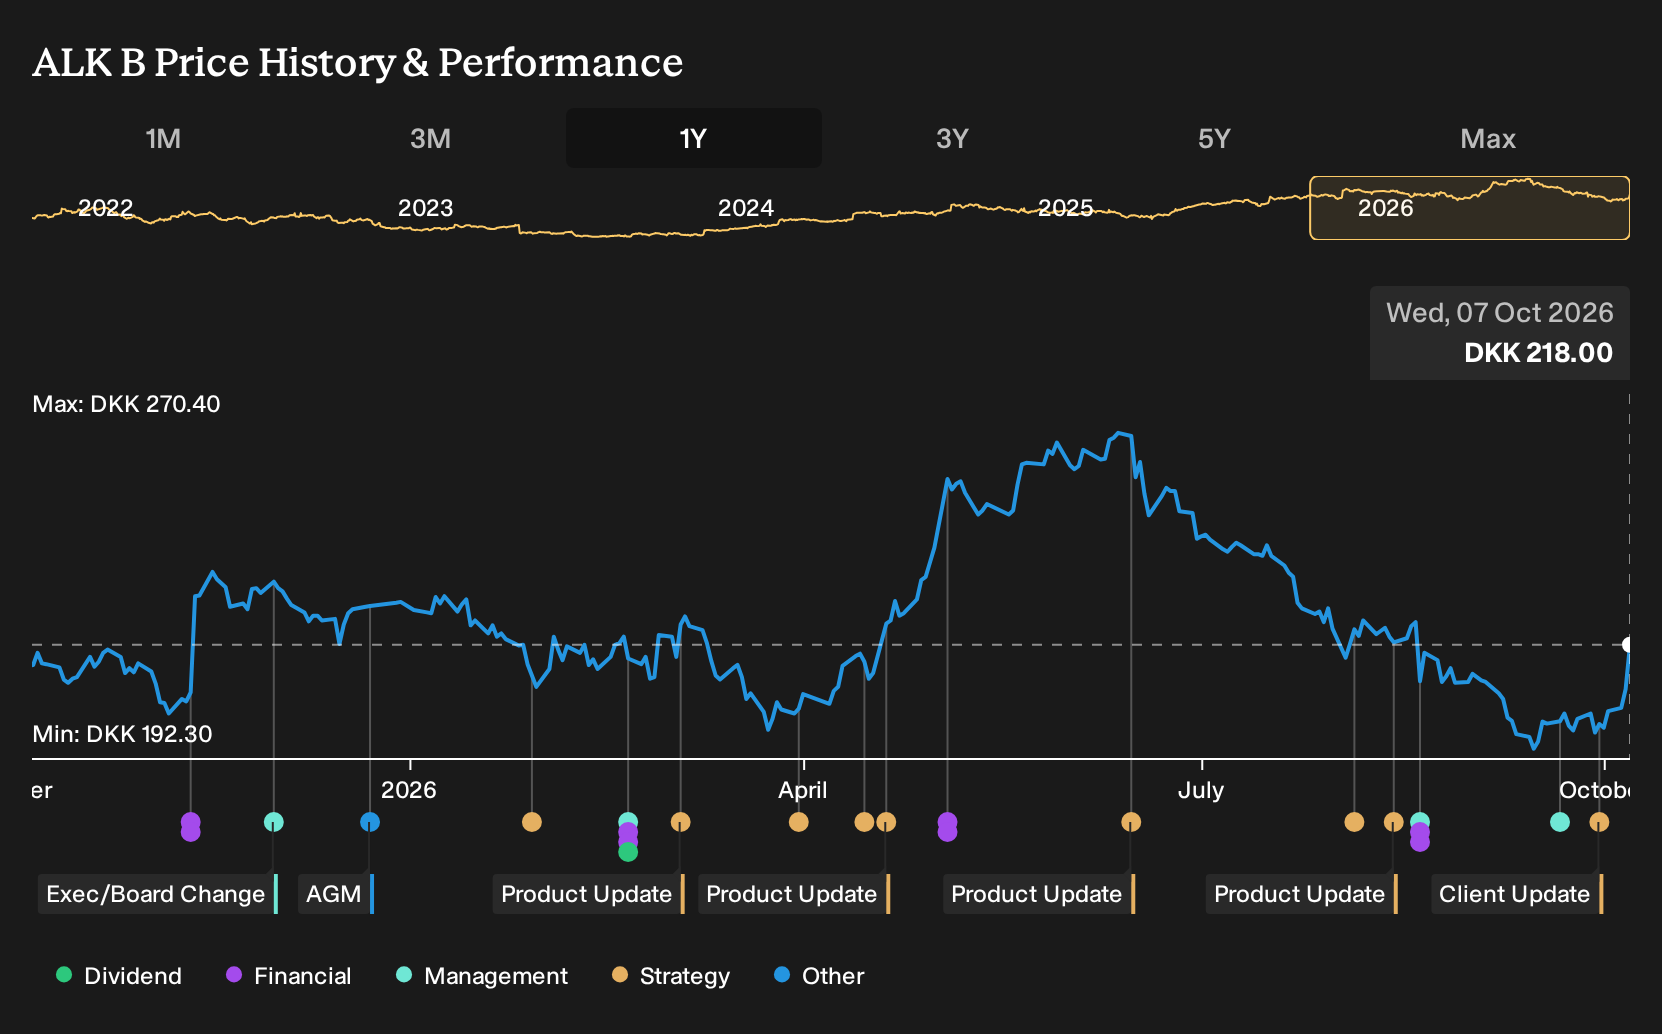
Exploring Other Perspectives
One alternate angle on ALK-Abelló focuses on tablet manufacturing risk. The most cautious analysts worried that heavy capacity and R&D spending could squeeze EBIT, so they were only pencilling in DKK 9.8b of revenue and DKK 1.9b of earnings by 2029. Those forecasts came before this capacity announcement, so their story may shift.
Explore 3 other ALK-Abelló fair value estimates, including one that suggests as much as 21% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ALK-Abelló research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for ALK-Abelló. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ALK-Abelló's overall financial health at a glance.
Looking for more ALK-Abelló-sized ideas?
Once you have formed a view on ALK-Abelló, it can help to line that thesis up against a wider watchlist of potential opportunities using the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, start by scanning a focused set of candidates that screen as 184 high quality undervalued stocks.
- If steady income matters to your plan, look at companies that show up as 224 dividend fortresses and see which payouts might fit your risk tolerance.
- For a more defensive watchlist, filter for businesses that qualify as a 225 resilient stocks with low risk scores and compare their profiles to ALK-Abelló's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com