


ICF International’s new SoCalREN work orders
ICF International (ICFI) just picked up two new multiyear work orders tied to Southern California Regional Energy Network public sector efficiency programs, with a combined ceiling value of about $70 million.
The contracts expand ICF International’s role under Los Angeles County’s Energy Support Services Master Agreement and add more visibility to its energy efficiency implementation pipeline heading into late 2026.
ICF International’s latest SoCalREN work extends a year in which the share price is up 8.53% over 90 days but down 5.85% over the last month, while total shareholder return has declined 9.87% over one year and 35.50% across three years, pointing to improving short term momentum against a weaker long term record.
Scan beyond ICF International and compare it with a curated set of peers executing on energy, infrastructure, and resilience themes using the 43 power grid technology and infrastructure stocks
ICF International now has fresh contract visibility, but a share price that is still below where it traded a few years ago. Does that tilt the risk reward toward buyers, or toward patience as valuation comes into focus next?
Most Popular Narrative: 23% Undervalued
ICF International’s most followed narrative points to a fair value of $107.25 per share compared with the last close at $82.85. This frames these new SoCalREN wins as part of a wider rerating story rather than a one off contract bump.
Ongoing operating leverage from mix shift toward nonfederal clients, where commercial, state and local, and international revenues grew 14.2% in 2025 and rose to about 61% of Q2 2026 revenue, combined with efficiency programs and greater use of AI and automation in both delivery and back office processes, aligns with ICF International's aim for 10 to 20 basis points of annual adjusted EBITDA margin expansion and supports the earnings and cash flow profile.
See why 1 investors see ICF International as 23% undervalued.
Result: Fair Value of $107.25 (UNDERVALUED)
Still, ICF International’s story can break if federal contract funding keeps sliding or if that US$9.3b pipeline fails to convert into stronger bookings.
Find out about the key risks to this ICF International narrative.
Another View: What ICF International’s P/E Is Really Saying
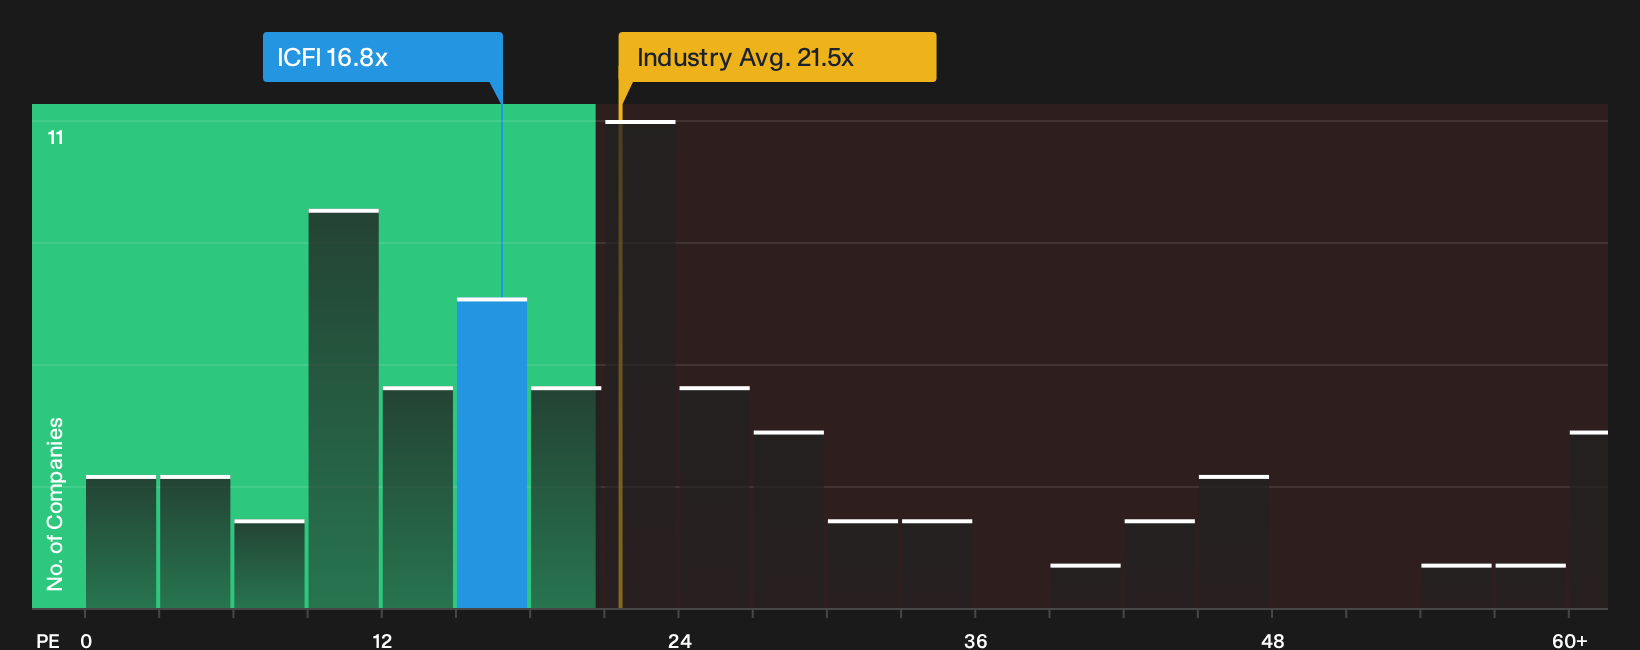
Our fair value work points to upside for ICF International, yet the simple P/E check sends a different signal. The shares trade on 16.8x earnings, almost identical to a fair ratio of 16.7x. This implies limited room for error even though the multiple sits well below the peer average of 29.4x and the broader US Professional Services mark of 21.5x. If the story wobbles, could that valuation gap to peers shrink instead of close?
For a closer look at how this earnings multiple stacks up against the underlying business, including risks if sentiment cools or heats up, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading this, do you feel the ICF International story is leaning more optimistic or cautious right now, and does that match your own view of the data? To pressure test that sentiment and see what the optimism is anchored to, take a closer look at the 2 key rewards.
Looking for more ICF International investment ideas?
ICF International can be one building block, but your portfolio works harder when you line it up against fresh ideas filtered by clear, disciplined rules.
- Target mispriced quality and pressure test your watchlist against a 29 high quality undervalued stocks focused on strong fundamentals and attractive entry points.
- Strengthen your income stream by scanning a focused group of reliable payers using the 8 dividend fortresses while yields and balance sheets still look appealing.
- Sleep easier by stress testing your holdings against a 31 resilient stocks with low risk scores that highlights resilient businesses built to handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com