


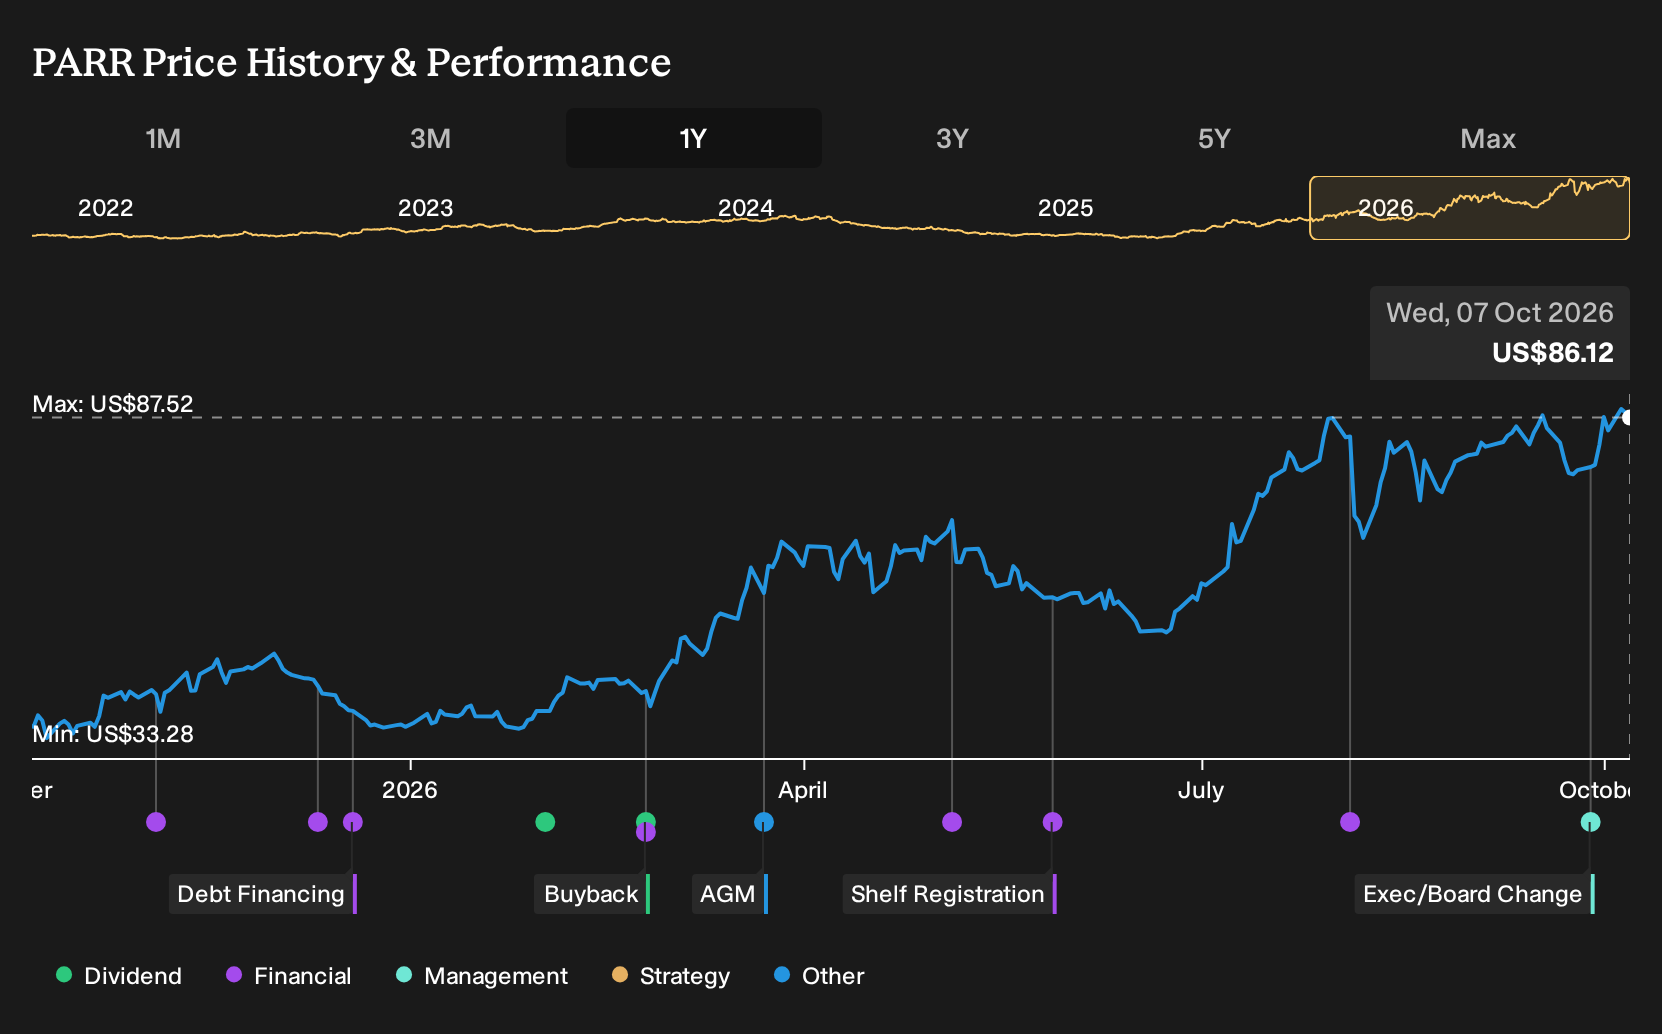
- Par Pacific Holdings appointed Jerry Stumbo as Executive Vice President, Refining and Logistics, in late September 2026, following his leadership of Valero's large and complex Port Arthur refinery and prior roles across multiple US refining assets.
- Stumbo's track record managing high throughput, complex facilities and major capital projects, including renewable fuel investments, aligns closely with Par Pacific Holdings' focus on refining margins, reliability and renewable diesel execution.
- Investors can now assess how Par Pacific Holdings' investment narrative may be influenced by Stumbo's leadership in refining and logistics.
Scan how Par Pacific Holdings’ leadership change compares with peers by focusing on high throughput refiners and infrastructure players in our curated 43 power grid technology and infrastructure stocks
Par Pacific Holdings Investment Narrative Recap
Owning Par Pacific Holdings means you need to be comfortable with a refining-led story that leans on tight Pacific Basin markets, high distillate and jet yields, and a growing renewable diesel contribution from Hawaii. The near term swing factor is still refining capture and asset reliability. The Stumbo hire looks additive to execution but does not on its own change that central thesis.
The key risk remains operational. Older assets in regions like Montana and Hawaii can see outages, cost spikes, or weather and regulatory shocks that quickly erode margin capture. Rising cash taxes as NOLs are consumed after 2026 also matter. Leadership depth in refining and logistics helps, but does not remove these structural pressures.
The most relevant recent data point around this leadership move is the description of strong refining conditions and solid margin capture for Par Pacific Holdings, supported by firm fuel demand and tight inventories. That backdrop has been helping the refining, retail, and logistics mix generate meaningful earnings and cash, while midstream adds steadier fee based contribution.
Viewed against that context, bringing in an executive who has run a 435,000 barrel per day complex refinery and overseen renewable diesel projects aligns directly with current catalysts. The story still turns on running refineries hard, keeping capture high, and steadily ramping Hawaii Renewables. Execution there influences how the market weighs forecast earnings declines against the low P/E and high recent return on equity.
What The New Leadership Sits On Top Of: The Current Analyst Setup
Par Pacific Holdings' leadership move comes at a time when analysts are already framing the financial outlook as a revenue and earnings taper rather than an open ended growth arc. Forecasts in the latest consensus work off an expectation that revenue will decline by 7.2% each year over the next 3 years and that profit margins will step down from 9.9% today to 7.7% by 2029.
On earnings, the same analyst group is working with US$856.9 million in earnings today and modeling that to fall to US$530.0 million by 2029. That implies an earnings reduction of about US$326.9 million across the period, even before any additional upside or downside from execution under the new refining and logistics leadership is considered.
Valuation assumptions apply those operating estimates using a simple multiple framework. Analysts are effectively asking investors to consider a scenario where by 2029 Par Pacific Holdings could be earning US$530.0 million on US$6.9b of revenue and trading on a P/E of 9.9x, compared with about 4.9x today and against a broader US Oil and Gas sector reference multiple of 12.3x.
Par Pacific Holdings' current analyst narrative centers on projected revenue of US$6.9b and earnings of US$530.0 million by 2029. This setup incorporates a modeled annual revenue decrease of 7.2% and an earnings reduction of about US$326.9 million from US$856.9 million today.
Uncover why Par Pacific Holdings' fair value is effectively aligned with its current price.
Exploring Other Perspectives
One alternate view focuses on tax pressure rather than refinery execution. The most cautious analysts were already working with a steeper 9.5% annual revenue decline and earnings of about US$571.9 million by 2029, before this Par Pacific Holdings leadership change. That group paints a harsher story and reminds you that opinions can differ widely. This new hire could eventually shift those narratives, so it can help to compare several angles before you decide how the story fits your own expectations.
Explore 3 other Par Pacific Holdings fair value estimates, including one that suggests it could be worth just $85.86.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Par Pacific Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Par Pacific Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Par Pacific Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Par Pacific Holdings?
Once you have a handle on Par Pacific Holdings, it can help to widen the lens and see how other businesses stack up on quality, value, and resilience using the Simply Wall St Screener.
- If you care most about financial strength and staying power, start with a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions without leaning heavily on new capital.
- For readers hunting for mispriced quality, there is a 29 high quality undervalued stocks that combines stronger cash flows with more conservative leverage.
- If steady income is a priority, use a 8 dividend fortresses that focuses on higher yielding payouts supported by underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com