


Why Schrödinger Stock Is Back On Investors' Radar
Schrödinger (SDGR) has drawn fresh attention after helping form Tectora, a biotech focused on immunology and inflammation therapies that just secured $55 million in Series A funding.
Recent trading tells a mixed story. Schrödinger’s share price is down 5.57% over the last day and 12.11% over the past week. However, the 30-day share price return of 35.84% and 90-day gain of 62.54% show momentum has been building, while the 1-year total shareholder return of 31.71% contrasts with a 5-year total shareholder return that is still down 49.46%.
See how Schrödinger’s story compares with other high-growth opportunities by reviewing our curated list of 20 high quality undiscovered gems in similar cutting-edge fields.
Schrödinger’s sharp swing, with short term weakness on top of a strong multi month run, raises a simple puzzle. Are traders just resetting sentiment around the Tectora news, or has the underlying business story genuinely shifted, and is that change already in the price?
Most Popular Narrative: 31% Overvalued
Schrödinger last closed at $27.29, while the most followed narrative pegs fair value at $20.88. The story being told in models is more cautious than the market price suggests and leans hard on a small set of big drivers.
Strong pipeline advancement and early clinical success, such as positive Phase I data for SGR-1505, positions the company to secure additional milestone payments, royalties, and out-licensing deals, creating potential for substantial long-term revenue growth and more predictable future cash flows.
See why 27 investors see Schrödinger as 31% overvalued.
Result: Fair Value of $20.88 (OVERVALUED)
Still, the story can break if software growth leans too heavily on existing clients, or if pressure on gross margins from predictive toxicology spending persists longer than expected.
Find out about the key risks to this Schrödinger narrative.
Another View On Schrödinger’s Valuation
Analyst models point to fair value around $20.88 and describe Schrödinger as 31% overvalued. The SWS DCF model tells a very different story. On that framework, the shares trade around $27.29 compared with an estimated future cash flow value of $41.87, which screens as undervalued.
This gap between earnings based pricing and cash flow based valuation raises a simple question for investors: which risk matters more, paying up for uncertain profitability or underpaying if the long term cash generation actually turns up as modeled?
Look into how the SWS DCF model arrives at its fair value.
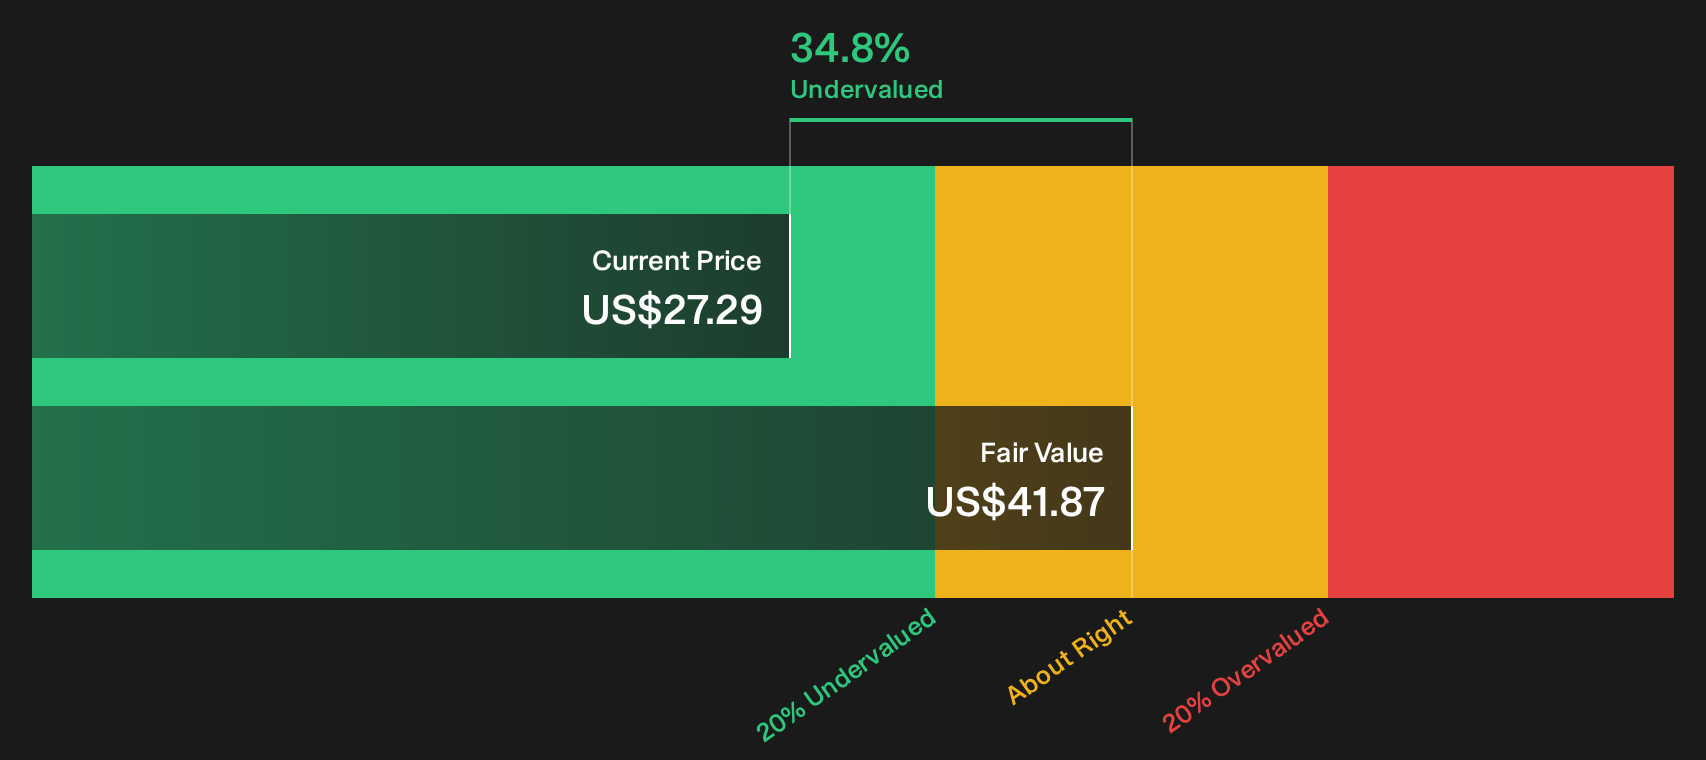
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Schrödinger for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Schrödinger can pull you in both directions. Move fast, review the full picture, and weigh the 1 key reward and 3 important warning signs.
Looking For More Ideas Beyond Schrödinger?
You have seen how one stock story can twist quickly. Do not stop here. Use the same tools to spot other opportunities before the crowd notices.
- Target steadier compounding by scanning a curated mix of quality companies that trade below their estimated worth through our 29 high quality undervalued stocks.
- Strengthen your income stream by lining up potential high-yield payers using the hand picked group of 8 dividend fortresses.
- Dial down risk while staying invested by focusing on resilient businesses through the carefully filtered 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com