


The Zhitong Finance App learned that according to the latest foundry supply tracking report released by Counterpoint Research, the global foundry 2.0 market revenue increased 25% year-on-year and 11% month-on-month to reach 96.6 billion US dollars in the second quarter of 2026. The market growth rate increased compared to the previous quarter, mainly driven by the continued growing demand for AI GPUs and the expansion of AI infrastructure, including customized ASICs, server CPUs, network chips, and power management ICs.
Brady Wang, Deputy Director of Counterpoint Research, said, “As pure wafer foundry, non-storage IDM, and OSAT vendors all achieve double-digit revenue growth, the impact of the AI investment cycle has spread to all parts of the industry's value chain. Although TSMC remains a major beneficiary of the AI demand cycle, mature process foundries, non-storage IDM, and OSAT vendors are also facing more growth opportunities. As AI processors increase in size and design complexity, advanced packaging remains a major constraint.”
Counterpoint Research predicts that TSMC's CoWoS supply and demand gap will remain around 20% in 2026, and as its internal production capacity expands to 185,000 wafers per month (KWPM), the gap will narrow to about 10% in 2027. Extended testing times and increased testing steps are driving OSAT vendors to gradually become strategic second-tier suppliers in the AI semiconductor ecosystem.
Pure wafer foundry market continues to grow
In the second quarter of 2026, the overall pure wafer foundry industry's revenue increased 29% year over year to $54.9 billion. Among them, TSMC's revenue increased 34% year-on-year and 12% month-on-month to reach US$40.2 billion, accounting for about 42% of the total foundry 2.0 market, up from 38% in 2025.
Despite being affected by a higher base, TSMC's revenue growth rate slowed from 41% in the first quarter of 2026, but its month-on-month growth trend is still relatively steady. Counterpoint Research predicts that TSMC's revenue will increase by about 43% for the full year 2026. This means that revenue will increase by nearly 50% year-on-year in the second half of 2026, and its performance will depend on whether mass production of the N2 process climbs, rising wafer prices, and whether the expansion of CoWoS production capacity progresses as planned.
The tight production capacity of CoOS has limited the shipment of AI products, prompting TSMC to increase back-end investment, while customers are simultaneously constructing alternative packaging solutions. Although this will not change TSMC's leading position among customers' advanced products, manufacturing capacity in the field of advanced/mature processes and packaging is undergoing structural reconfiguration.
Foundry 2.0 market revenue share, second quarter 2026
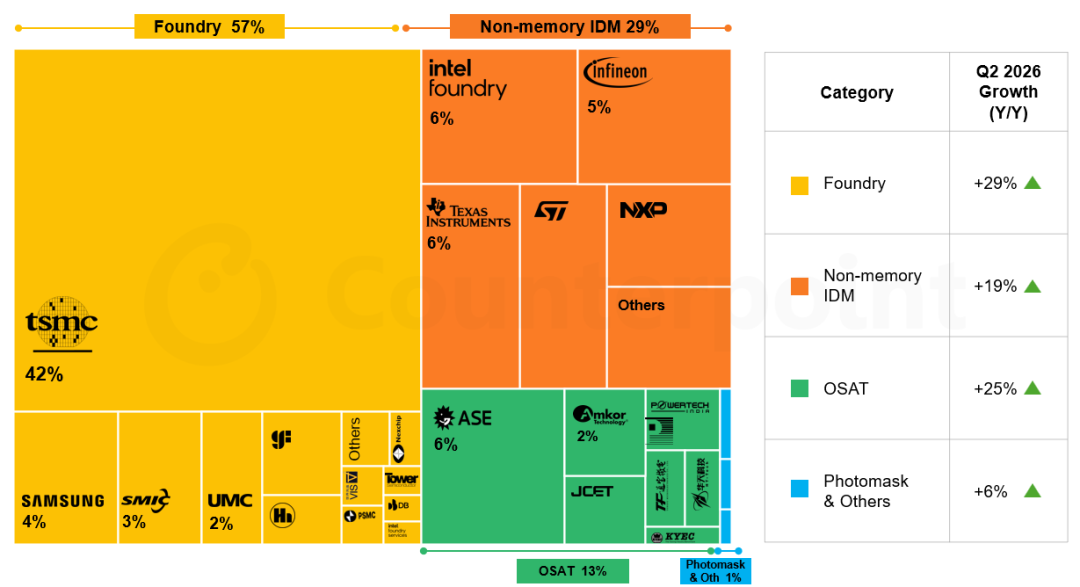
Source: Counterpoint Research Foundry Tracking Report, Q2 2026
The revenue of pure wafer foundries other than TSMC increased 18% year over year, up from 9% in the first quarter of 2026. Among them, SMIC performed strongly, growing 36% year over year. SMIC is benefiting from growing demand for AI chips in mainland China. It is expected that its N+2 production capacity will remain tight in 2026, and the capacity utilization rate will remain high. Meanwhile, Huahong and Nexchip (Nexchip)'s revenue increased 17% and 21%, respectively.
The performance of second-tier foundries in Taiwan, China is divided. UMC (UMC) and Vanguard (Vanguard) revenue increased 9% and 20% year over year, respectively, and increased 13% and 9%, respectively, mainly driven by demand for power management ICs (PMICs), MCUs, and other peripheral chips, which led to an increase in capacity utilization. However, the tight supply and demand for mature processes is mainly concentrated in AI-related application fields such as PMIC and silicon intermediates. Instead of a general supply shortage in the entire industry, demand in the consumer market is still weak.
While continuing to optimize manufacturing capacity through advanced process capacity allocation, the world's advanced technology is taking on more demand for silicon interposers (interposers), while UMC (UMC) is benefiting from improved demand in the PMIC and silicon photonics (silicon photonics) fields. GlobalFoundries (GlobalFoundries)'s revenue growth rate is relatively moderate, and weak demand for automobiles and smartphones is offsetting the growth of its communications infrastructure and data center business, which is mainly driven by demand for silicon photonics and silicon-germanium needed for AI optical interconnection.
William Li, senior analyst at Counterpoint Research, said, “As customers seek diverse sources of supply, Samsung and Intel Foundry are also benefiting. Thanks to demand for the SF4/SF5 process and rising wafer prices, Samsung maintained a market share of around 4% in the second quarter of 2026, ranking second; at the same time, Intel's EMIB-T package has been used by Google for the next generation of TPUs. However, at present, neither of these suppliers can completely replace TSMC's comprehensive advantages in advanced process scale, yield, and package execution capabilities.”
Non-storage IDM benefits from industrial market recovery and AI power demand
In the second quarter of 2026, the overall revenue of non-storage IDM vendors increased 19% year over year. Among them, Intel Foundry grew 31% year over year, followed by STMicroelectronics (STMicroelectronics), up 26%; Texas Instruments (Texas Instruments) up 23%; NXP (NXP) grew 19%; and Infineon (Infineon) grew 15%. Part of the increase comes from a lower comparative base, as such vendors are still in the inventory adjustment phase in the first half of 2025.
Counterpoint Research predicts that the recovery trend of non-storage IDM vendors will continue until the second half of 2026, mainly benefiting from the increase in AI data center rack-level power density and the shift to higher voltage power supply architectures, thereby driving demand for PMIC, MOSFETs, and silicon carbide (SiC) /gallium nitride (GaN) devices. However, if costs cannot be transferred to downstream customers, rising foundry and packaging costs could put pressure on IDM vendor margins.
Advanced packaging pushes OSAT to become an important part of the AI supply chain
In the second quarter of 2026, the OSAT industry maintained its growth trend. Revenue increased 22% year over year and 12% month over month to reach US$12.6 billion. Market growth is mainly driven by AI processor demand for advanced packaging, wafer probing (wafer probing), and finished product testing. ASE's revenue increased 24% year over year, and Amkor (Amkor) increased 26% year over year. Other OSAT vendors also achieved year-over-year growth of more than 20% in the second quarter.
In the foundry 2.0 market, Sun Moon Light is second only to TSMC in size. It has gradually become the second supplier after TSMC in the field of advanced packaging, while its full-process solution business has also grown. Anjiao is expanding its 2.5D package production capacity; Powertech (Powertech) is seeking more opportunities in the CPU packaging field and developing panel-level packaging technology. Despite the trend of diversification in back-end packaging and testing, most advanced AI computing chip wafers are still manufactured by TSMC, so its market position is still stable.
As chip complexity continues to increase, the importance of final testing and burn-in testing (burn-in testing) becomes increasingly prominent. However, there are differences in testing requirements for different architectures, which means that testing cycles for different products will not grow at the same time, and suppliers need to customize and optimize for different architectures. Therefore, in addition to existing production capacity, yield stability and process integration capabilities are gradually becoming important competitive advantages for OSAT manufacturers.
Outlook: Back-end production capacity and computing diversification will affect market trends in the second half of 2026
As AI demand expands from GPUs to customized ASICs, server CPUs, and power components, Counterpoint Research expects the foundry 2.0 market to maintain double-digit year-on-year growth in the second half of 2026. Advanced packaging, substrates, and test capacity will remain key constraints to AI deployments.
At the same time, the growth of agentic AI (agentic AI) workloads is also driving up the demand for CPUs per AI rack, further increasing the need for advanced process wafers and CPU packages. The main risks facing the market include CoWoS and substrate production capacity bottlenecks, the cost transmission of rising wafer and packaging costs, continued weakness in consumer market demand, and trade policy uncertainty.
William Li further stated, “AI demand is no longer limited to a single product. As GPUs, custom ASICs, server CPUs, and power chips compete for limited wafer, package, and test capacity, growth opportunities are expanding from TSMC to mature process foundries, IDM, and OSAT vendors. In the second half of 2026, suppliers that can guarantee large-scale packaging and testing production capacity are expected to receive more demand from additional investment in AI.”
After 2026: Trillion-dollar packaging bottlenecks reshape the foundry 2.0 market pattern
Looking at the long term, packaging rather than logical process miniaturization is becoming an important field of industrial competition. Counterpoint Research estimates that over 130 million GPUs and AI ASICs will be shipped within the next five years, with on-compute memory (on-compute memory) using advanced packaging technology, thus generating nearly $2 trillion in computing-related revenue.
Achieving this goal requires breaking through three intertwined bottlenecks: Memory Wall (Memory Wall), Performance Wall (Performance Wall), and Copper Wall (Copper Wall). HBM relies on CoWoS silicon intermediates, and the resulting cost, yield, and capacity limitations are driving the market to explore more alternatives.
Intel is combining EMIB bridge packaging with ZAM and XBM memory architectures to form packaging solutions other than TSMC CoOS. Qualcomm's High Bandwidth Computing (HBC) stacks LPDDR memory on logical chips to bypass the 2.5D silicon interlayer, and its first products are expected to launch in mid-2027. Nvidia's NVHBM technology further expands its application in custom accelerator projects by moving the memory controller to a custom HBM base film designed by Nvidia and produced on demand by the memory manufacturer.
For the Foundry 2.0 ecosystem, value is gradually shifting to logically-based components such as bare chips, bridge structures, and substrates. This brings new opportunities for wafer foundries that can combine advanced logic processes with packaging production capacity, and for OSAT and substrate suppliers that can achieve large-scale certification of these new architectures.
Neil Shah, vice president of research at Counterpoint Research, said, “In the next phase of AI infrastructure construction, chip packaging will be no less important than wafer manufacturing. As memory gets closer to computing, the integrated manufacturing, packaging, and testing model represented by Foundry 2.0 has gradually evolved from a concept to an actual way of operating the industry. Foundry and OSAT that can now lock in basic die, bridge structures, and substrate production capacity for the 2027-2028 architecture will have a better position in the nearly $2 trillion AI computing market opportunity.”