


As global markets navigate a complex landscape of mixed economic signals, including cooling job growth and persistent inflation pressures, investors are increasingly focused on sectors showing resilience and potential for expansion. In this environment, growth companies with high insider ownership can be particularly appealing as they often indicate strong alignment between management and shareholder interests.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Meitu (SEHK:1357) | 23% | 26.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Fulin Precision (SZSE:300432) | 10.8% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
We're going to check out a few of the best picks from our screener tool.
Zhende Medical (SHSE:603301)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Zhende Medical Co., Ltd. focuses on the research, development, production, and sale of medical care and protective equipment both in China and internationally, with a market cap of CN¥19.84 billion.
Operations: Zhende Medical generates its revenue from the development, production, and distribution of medical care and protective equipment across domestic and international markets.
Insider Ownership: 10.5%
Revenue Growth Forecast: 17.7% p.a.
Zhende Medical's earnings are forecast to grow significantly, outpacing the Chinese market with a projected annual growth of 39.5%. Despite slower revenue growth at 17.7% annually, it remains above the market average. Recent earnings showed improvement, with net income rising to CNY 143.78 million for H1 2026 from CNY 127.76 million a year prior. Insider trading activity over the past three months is minimal, indicating stable insider sentiment towards future prospects.
- Dive into the specifics of Zhende Medical here with our thorough growth forecast report.
- Our comprehensive valuation report raises the possibility that Zhende Medical is priced higher than what may be justified by its financials.

Beijing HyperStrong Technology (SHSE:688411)
Simply Wall St Growth Rating: ★★★★★★
Overview: Beijing HyperStrong Technology Co., Ltd. designs, develops, integrates, and operates energy storage power stations both in China and internationally, with a market cap of CN¥28.98 billion.
Operations: Revenue Segments (in millions of CN¥):
Insider Ownership: 22.3%
Revenue Growth Forecast: 28.7% p.a.
Beijing HyperStrong Technology is trading at a substantial discount to its estimated fair value, suggesting potential upside. The company is experiencing robust growth, with earnings projected to increase significantly by 47.8% annually and revenue expected to rise by 28.7% per year, outpacing the Chinese market. Recent inclusion in major indices like the FTSE All-World Index highlights its growing prominence. However, its dividend yield of 0.97% is not well covered by free cash flows.
- Take a closer look at Beijing HyperStrong Technology's potential here in our earnings growth report.
- Our expertly prepared valuation report Beijing HyperStrong Technology implies its share price may be lower than expected.
Visional (TSE:4194)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Visional, Inc., along with its subsidiaries, offers human resources platform solutions in Japan and has a market cap of approximately ¥369.78 billion.
Operations: The company's revenue is primarily derived from its HR Tech segment, which generated ¥94.09 billion, and its Incubation segment, which contributed ¥5.52 billion.
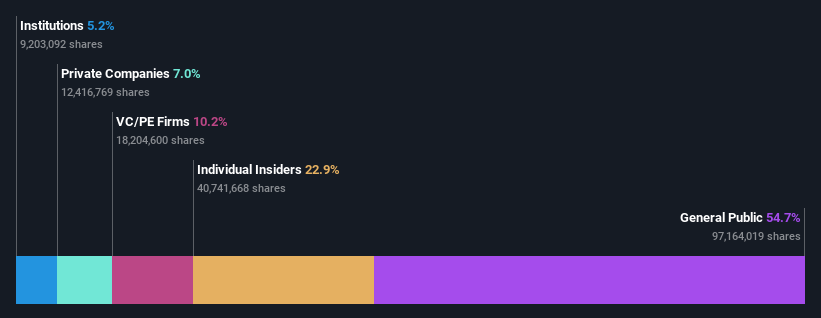
Insider Ownership: 35.1%
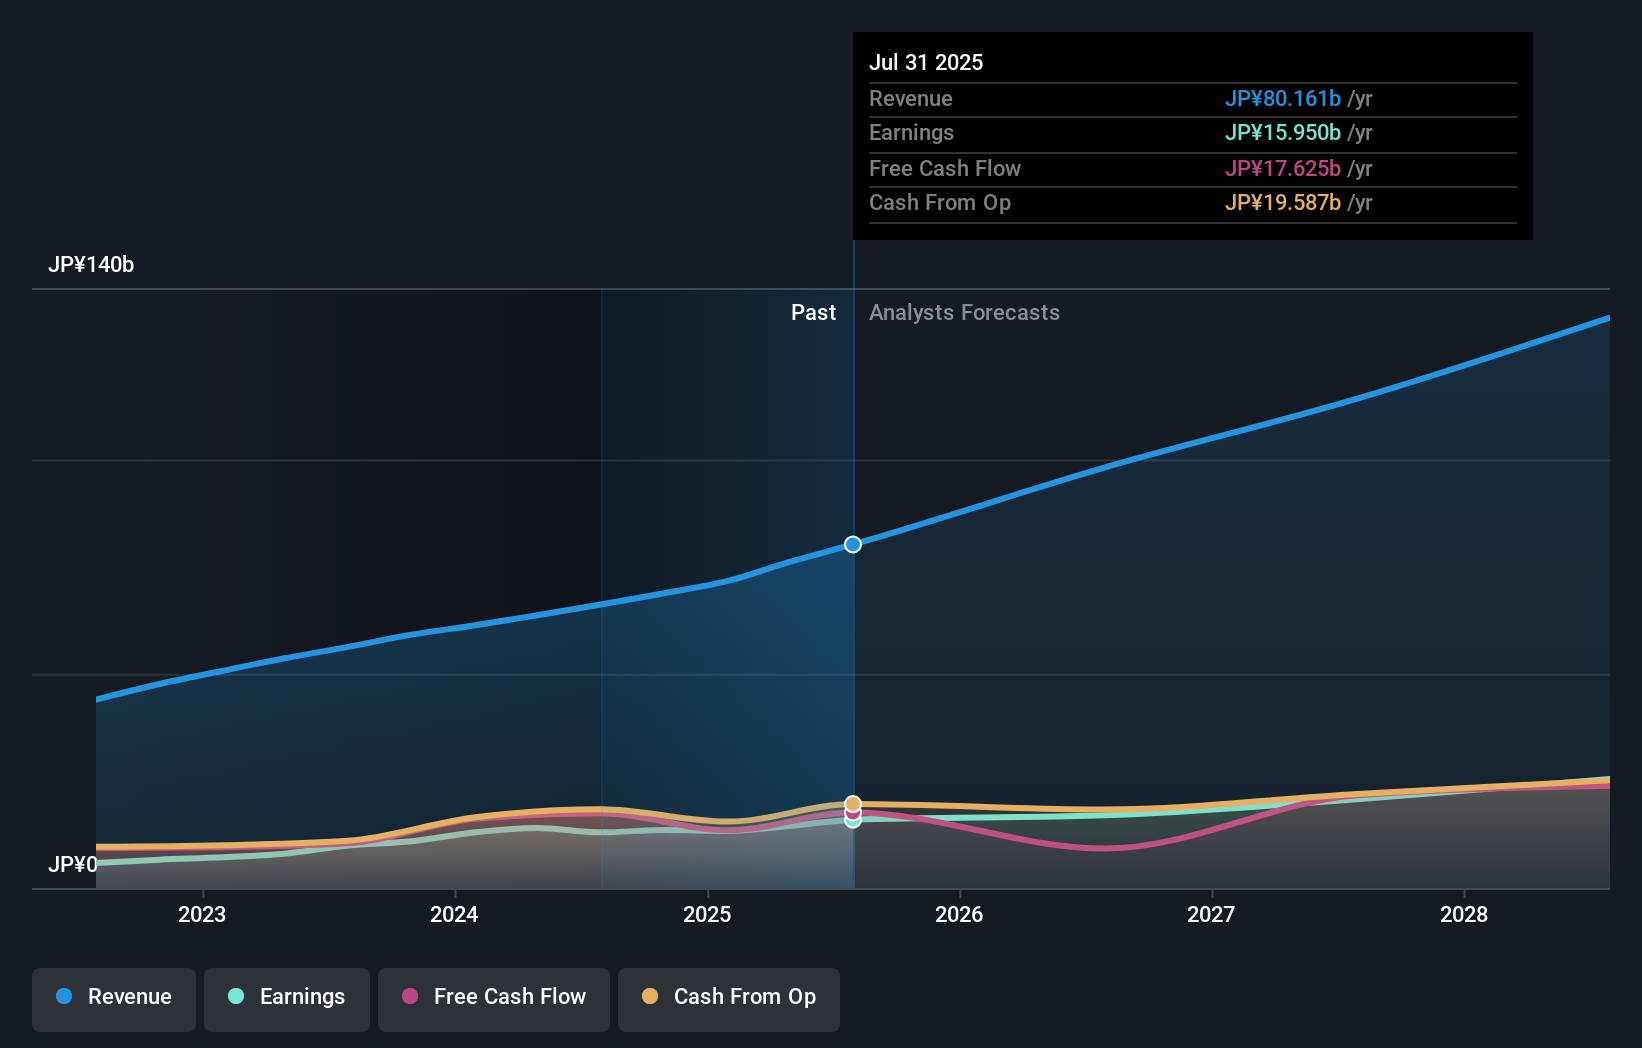
Revenue Growth Forecast: 13% p.a.
Visional, Inc. is trading significantly below its estimated fair value, indicating potential undervaluation. The company reported a notable increase in sales and net income for the year ending July 2026, with revenue growing to ¥99.3 billion from ¥80.16 billion the previous year. Earnings are projected to grow at 9.5% annually, surpassing Japan's market average growth rate of 9.5%. Recent board decisions aim to clarify business purposes and accommodate diversification efforts, potentially supporting future growth strategies.
- Click here to discover the nuances of Visional with our detailed analytical future growth report.
- The valuation report we've compiled suggests that Visional's current price could be inflated.
Next Steps
- Delve into our full catalog of 707 Fast Growing Global Companies With High Insider Ownership here.
- Interested In Other Possibilities? Rare earth metals are the new gold rush. Find out which 33 stocks are leading the charge.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com