


As the global markets navigate through a period of mixed economic signals, small-cap stocks have become a focal point for investors seeking opportunities amid persistent inflation and fluctuating interest rates. With the S&P 600 and Russell 2000 indices showing varied performances, identifying small-cap companies with strong fundamentals and insider buying can offer potential value in an uncertain market environment.
Top 10 Undervalued Small Caps With Insider Buying Globally
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Q Technology (Group) | 3.5x | 0.2x | 43.71% | ★★★★★☆ |
| Timbercreek Financial | 16.6x | 9.6x | 38.29% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 7.0x | 0.9x | 38.47% | ★★★★★☆ |
| Transcontinental | 2.5x | 0.2x | -98.98% | ★★★★☆☆ |
| Diversified Royalty | 25.5x | 10.1x | 45.85% | ★★★★☆☆ |
| Franchise Brands | 26.6x | 2.0x | 48.49% | ★★★★☆☆ |
| Sagicor Financial | 6.6x | 0.5x | -69.94% | ★★★★☆☆ |
| Yellow Pages | 8.5x | 0.8x | 28.84% | ★★★☆☆☆ |
| Centurion | 17.2x | 3.3x | 15.65% | ★★★☆☆☆ |
| AB Dynamics | NA | 1.8x | 20.43% | ★★★☆☆☆ |
Let's explore several standout options from the results in the screener.
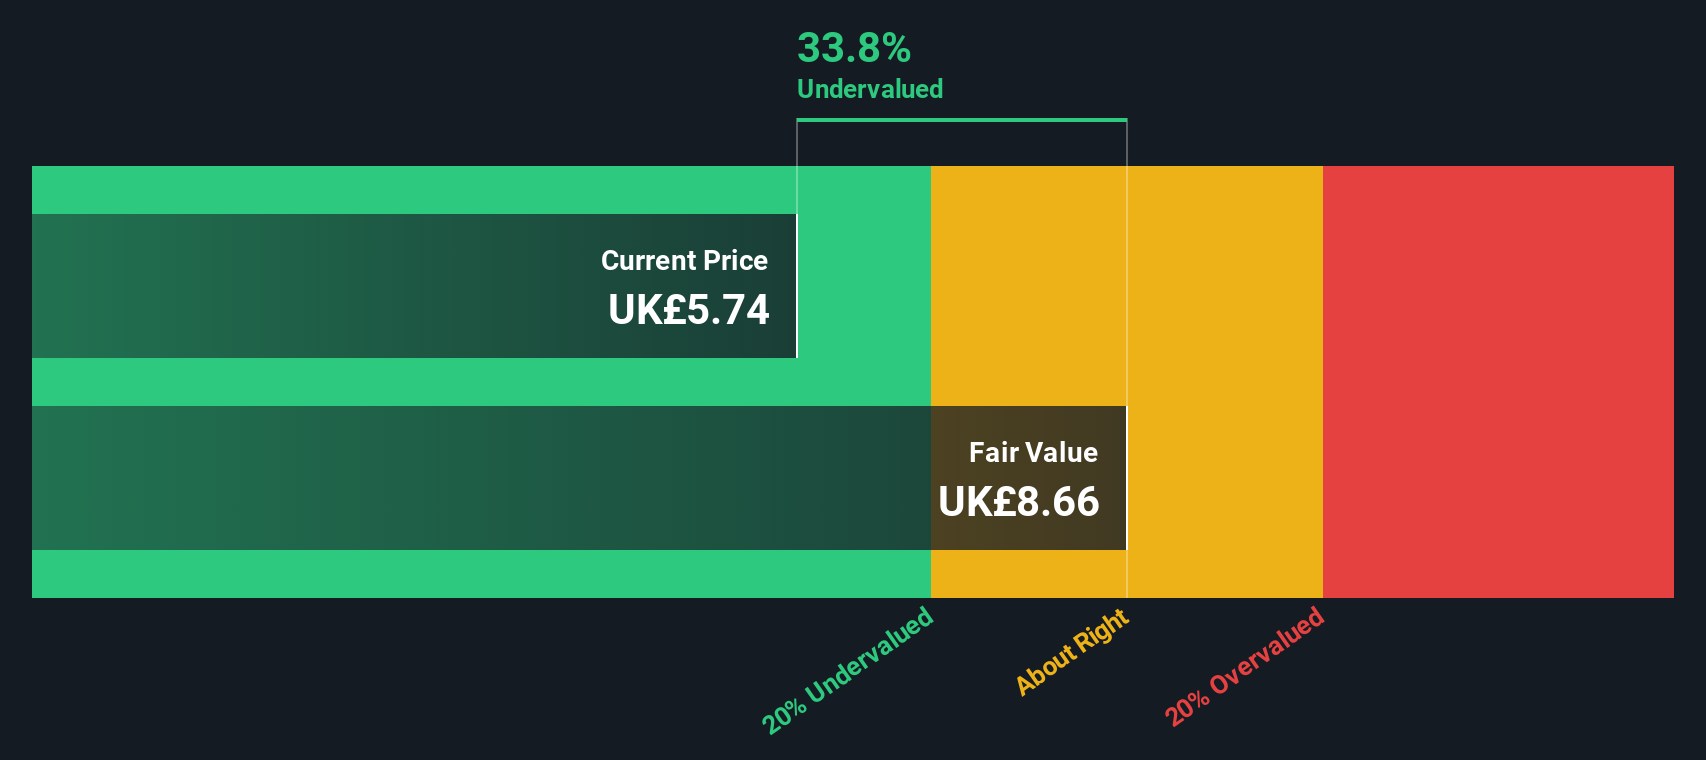
Vp (LSE:VP.)
Simply Wall St Value Rating: ★★★★★☆
Overview: Vp is a UK-based equipment rental specialist providing services across various sectors, with a market cap of approximately £0.33 billion.
Operations: The company generates revenue primarily from the UK market, contributing £293.51 million, with additional income from international operations amounting to £71.19 million. The net income margin has shown fluctuations over recent periods, reaching a high of 10.72% in March 2022 before declining to -1.52% by March 2026. Operating expenses and non-operating expenses have consistently impacted net profitability, with significant variations observed in non-operating costs over time.
PE: -37.3x
Vp plc, a small cap company, has been experiencing notable insider confidence with share purchases occurring over the past year. With its earnings projected to grow 55.8% annually, Vp is positioned for potential expansion despite relying solely on external borrowing for funding. Recent board changes bring seasoned leaders like Corinne Ripoche and Ross Paterson, enhancing strategic governance. The declared final dividend of 28 pence per share underscores management's commitment to shareholder returns amidst financial challenges.
- Unlock comprehensive insights into our analysis of Vp stock in this valuation report.
Review our historical performance report to gain insights into Vp's's past performance.
Nivika Fastigheter (OM:NIVI B)
Simply Wall St Value Rating: ★★★☆☆☆
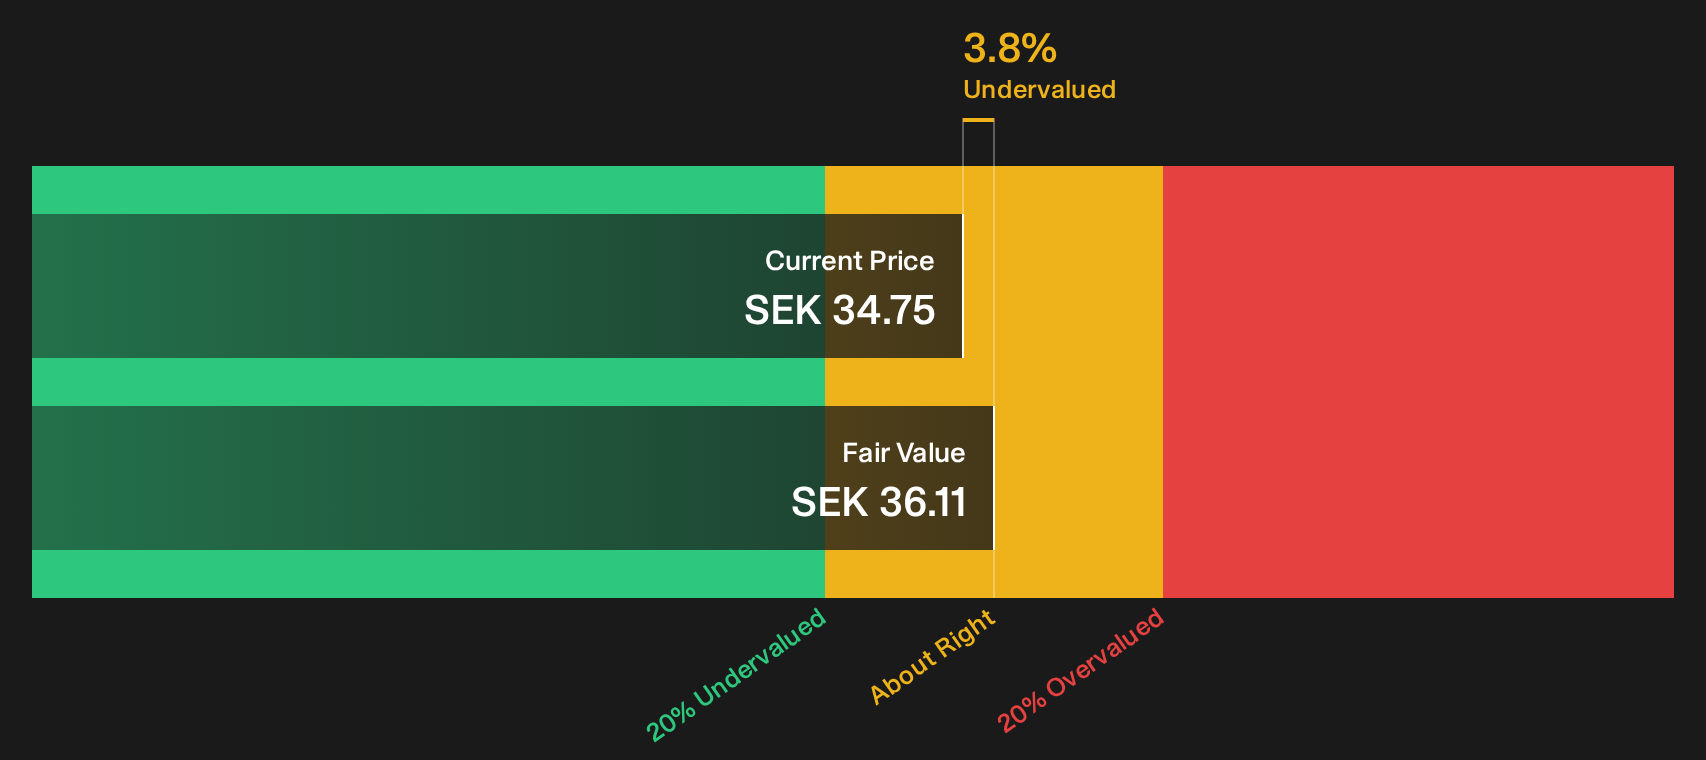
Overview: Nivika Fastigheter is a real estate company focused on rental properties, with a market capitalization of SEK 3.45 billion.
Operations: The company generates revenue primarily from its real estate rental segment, reporting a gross profit margin of 72.25% as of the latest period. Over time, non-operating expenses have significantly impacted net income margins, which have fluctuated widely and recently turned negative before recovering to positive territory. Operating expenses are a consistent component of the cost structure, with general and administrative expenses being a notable part.
PE: 8.1x
Nivika Fastigheter, a smaller company in the property sector, has recently expanded its portfolio by acquiring properties valued at SEK 66 million, adding 7,500 square meters of leasable space. This move enhances their cash flow and occupancy rates. Insider confidence is evident with Tim Floderus purchasing 100,000 shares for approximately SEK 3.8 million in August 2026. Despite earnings forecasts indicating a decline over the next three years, recent financial performance shows increased revenue and net income compared to last year.
- Delve into the full analysis valuation report here for a deeper understanding of Nivika Fastigheter.
Evaluate Nivika Fastigheter's historical performance by accessing our past performance report.
Nayax (TASE:NYAX)
Simply Wall St Value Rating: ★★★☆☆☆
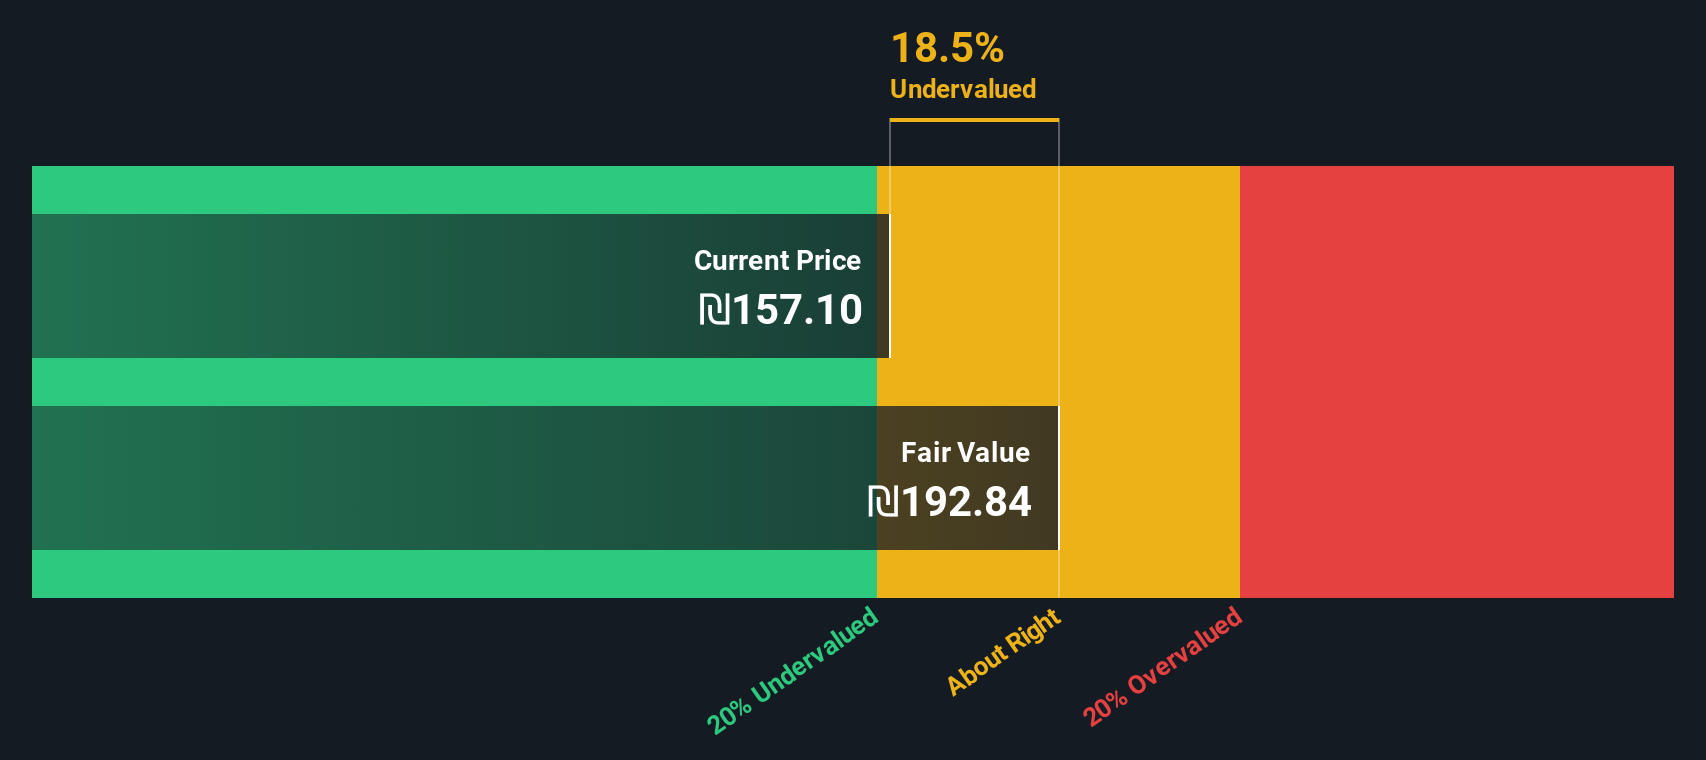
Overview: Nayax specializes in providing cashless payment solutions and management systems for unattended retail environments, with a market cap of $1.13 billion.
Operations: The company's revenue is derived from its Internet Software and Services segment, with a recent revenue of $453.18 million. Over the analyzed periods, the gross profit margin has shown variability, reaching 48.23% in September 2025 before slightly decreasing to 47.80% by June 2026. Operating expenses are significant, with General & Administrative expenses being a major component within this category.
PE: 220.0x
Nayax, a player in the payment solutions space, is exploring growth through strategic partnerships and acquisitions. Recent collaborations with Allied Electronics and Getnet aim to expand its footprint in the US fuel retail market and Latin American automated commerce sectors. Despite a volatile share price recently, insider confidence is evident with purchases over the past year. The company's focus on integrating payment technology into new verticals like mass transit and laundry suggests potential for future expansion.
- Click to explore a detailed breakdown of our findings in Nayax's valuation report.
Understand Nayax's track record by examining our Past report.
Summing It All Up
- Discover the full array of 126 Undervalued Global Small Caps With Insider Buying right here.
- Got skin in the game with these stocks? Elevate how you manage them by using Simply Wall St's portfolio, where intuitive tools await to help optimize your investment outcomes.
- Take control of your financial future using Simply Wall St, offering free, in-depth knowledge of international markets to every investor.
Seeking Other Investments?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com