


Why earnings worries are back in focus for Celsius Holdings (CELH)
Fresh analyst previews flag an expected year over year earnings decline and softer quarterly sales for Celsius Holdings (CELH), putting short term profitability and brand recovery under the microscope for investors.
Recent pressure on Celsius Holdings shares has been steady rather than sudden, with the 30-day share price return down 12.2% and the year to date share price return down 43.6%, while the 1-year total shareholder return has fallen 57.2%. This points to fading momentum as investors reassess short term earnings risk against the longer term brand story.
Scan beyond Celsius Holdings and compare this sell off story with consumer names on our hand picked list of 29 high quality undervalued stocks.
Celsius Holdings now trades at a steep discount to both analyst targets and one estimate of fair value after a sharp reset in expectations. Is this caution about earnings and brand repair sensible, or has pricing swung too far?
Most Popular Narrative: 43% Undervalued
The prevailing narrative prices Celsius Holdings at a fair value of $47.37 per share versus the last close at $26.92, framing a wide valuation gap that bulls link to brand strength, acquisitions and distribution reach.
I believe Celsius Holdings stock can reach a price of $47.00 per share (+42%) over the next two months, with potential to reach $71.00 per share within the next few years. This will be driven by continued earnings and revenue gains, international expansion, and the long-term integration of Alani Nu and Rockstar, which were both recent acquisitions.
See why 11 investors see Celsius Holdings as 43% undervalued.
According to Bullish4YaMotha, this story leans heavily on Celsius Holdings becoming a broader beverage platform rather than a single energy drink badge. The narrative points to a portfolio that now includes CELSIUS ESSENTIALS, CELSIUS Hydration, Alani Nu and Rockstar, supported by wide distribution through supermarkets, convenience outlets, gyms and e-commerce across North America, Europe and Asia-Pacific.
The valuation view behind that fair value level labels the stock as undervalued and ties it to expected earnings expansion, international roll out and brand integration benefits. It also sits alongside Simply Wall St's DCF output, which places Celsius Holdings' future cash flow value at $61.28 per share, noticeably above the current share price of $26.92 and above the user narrative fair value.
Short term earnings pressure, a reduced net profit margin of 2.1% versus 5.8% last year and a large one off loss of $480.5m sit awkwardly next to that optimistic script. At the same time, the narrative lines up with modelled expectations of significant annual profit growth of about 29.5% and a share price trading 56.1% below one estimate of intrinsic value from the SWS DCF model.
Result: Fair Value of $47.37 (UNDERVALUED)
Still, Celsius Holdings faces real pressure if earnings keep lagging revenue or if brand integration around Alani Nu and Rockstar takes longer than bullish forecasts assume.
Find out about the key risks to this Celsius Holdings narrative.
Another view on Celsius Holdings valuation
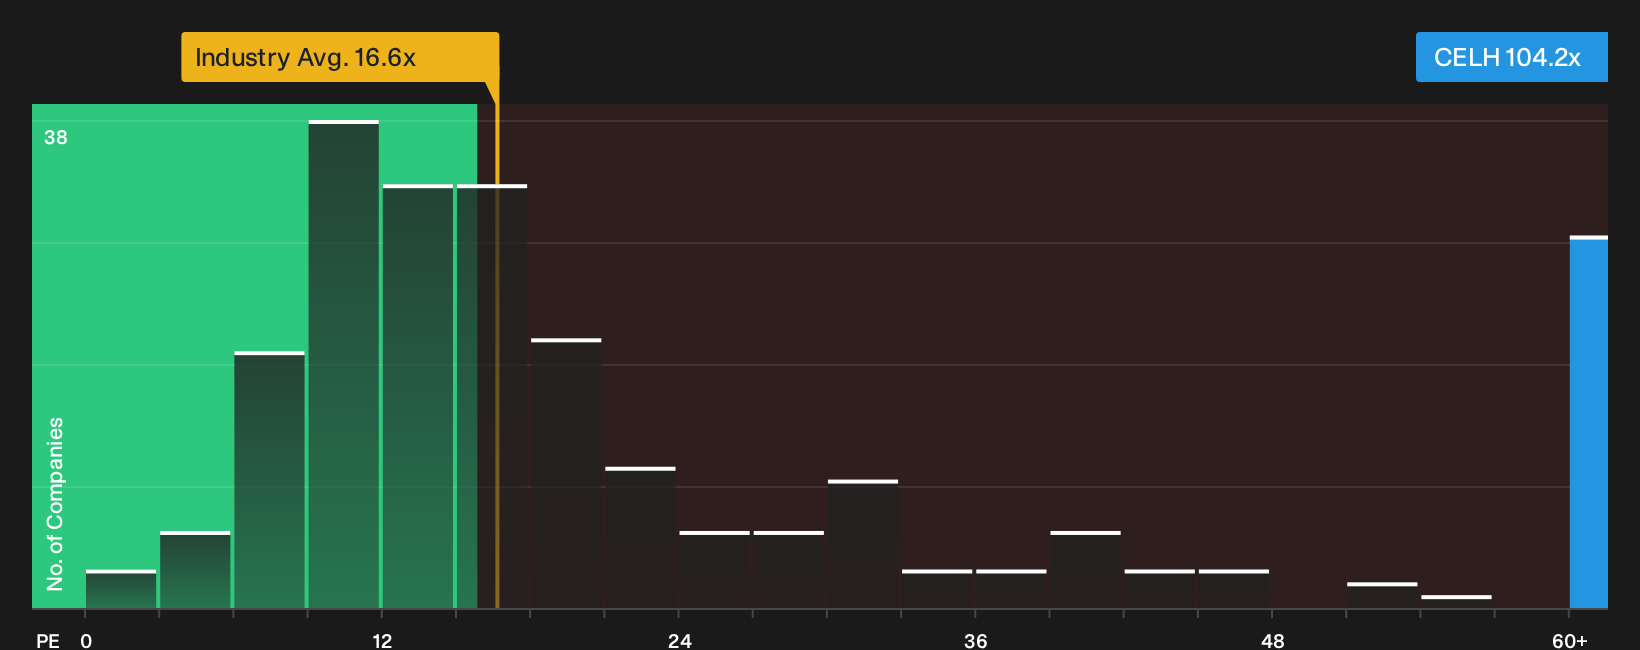
On earnings multiples, Celsius Holdings looks far less forgiving. The stock trades on a P/E of 104.2x compared with a global beverage sector average of 16.6x and a peer group at 31.9x, while the fair ratio is 28.6x, which flags meaningful valuation risk if sentiment cools.
That kind of gap suggests investors are paying up heavily for the Celsius Holdings story, even with earnings forecasts pointing higher. The live question is whether profit delivery can keep justifying such a premium before the market leans closer to that fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty here points to a split verdict on Celsius Holdings, so move fast, dig into the underlying figures, and pressure test both sides of the story using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Celsius Holdings?
If Celsius Holdings has you rethinking where risk and reward line up, use a focused stock screener to quickly surface other situations that better match your criteria.
- Spot potential turnaround stories early by scanning the 12 elite penny stocks with strong financials that already show stronger financial underpinnings than most tiny tickers.
- Prioritise resilience by filtering for a 31 resilient stocks with low risk scores that combines steadier fundamentals with lower overall risk scores.
- Hunt for tomorrow's leaders by running a 20 high quality undiscovered gems screened for quality metrics that many investors have not yet acted on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com