


- Cigna Healthcare has launched Health Sense, a personalized support model that connects customer health, benefit and cost data to help people act earlier, use coverage more effectively and support treatment decisions alongside their clinicians.
- The program uses Cigna Group's existing myCigna platform, clinical teams and advanced reasoning tools, linking oncology and cardiometabolic care journeys with benefit design and pharmacy coverage in a single, integrated experience.
- We will look at how Cigna Group's investment narrative is influenced by Health Sense's integrated data model for complex care management.
Cigna Group Investment Narrative Recap
To own Cigna Group, you need to believe its blend of Cigna Healthcare and Evernorth can keep medical cost trends in check while holding on to employer and PBM clients. Health Sense fits that story but does not change the near term swing factors. The key near term catalyst remains execution on the PBM Signature model and the 2027 selling season.
The biggest risk still sits in margin pressure at Evernorth and affordability strain in commercial plans, especially as Cigna exits the ACA exchanges and absorbs stranded overhead. Health Sense may support long term cost discipline, yet the quantitative impact and timing on consolidated earnings remain uncertain today.
The Health Sense launch matters most alongside Cigna Group’s broader AI and data programs that have already reduced avoidable inpatient stays and lowered costs per engaged customer. Health Sense extends that logic into oncology and cardiometabolic care, tying together claims, pharmacy coverage and benefit design inside myCigna rather than a separate app.
For catalysts, this kind of integrated data layer could support Cigna Healthcare’s ability to manage high single digit cost trends and help Evernorth demonstrate the value of its clinical programs to employers. Execution risk is real, from data integration to clinician adoption, and the rollout timing from 2027 means investors still rely on existing specialty and PBM earnings drivers in the interim.
Cigna Group's current analyst playbook points to revenues of US$324.7b and earnings of US$7.8b by 2029, which lines up with a 4.8% yearly revenue growth rate and an earnings step up of about US$1.4b from US$6.4b today.
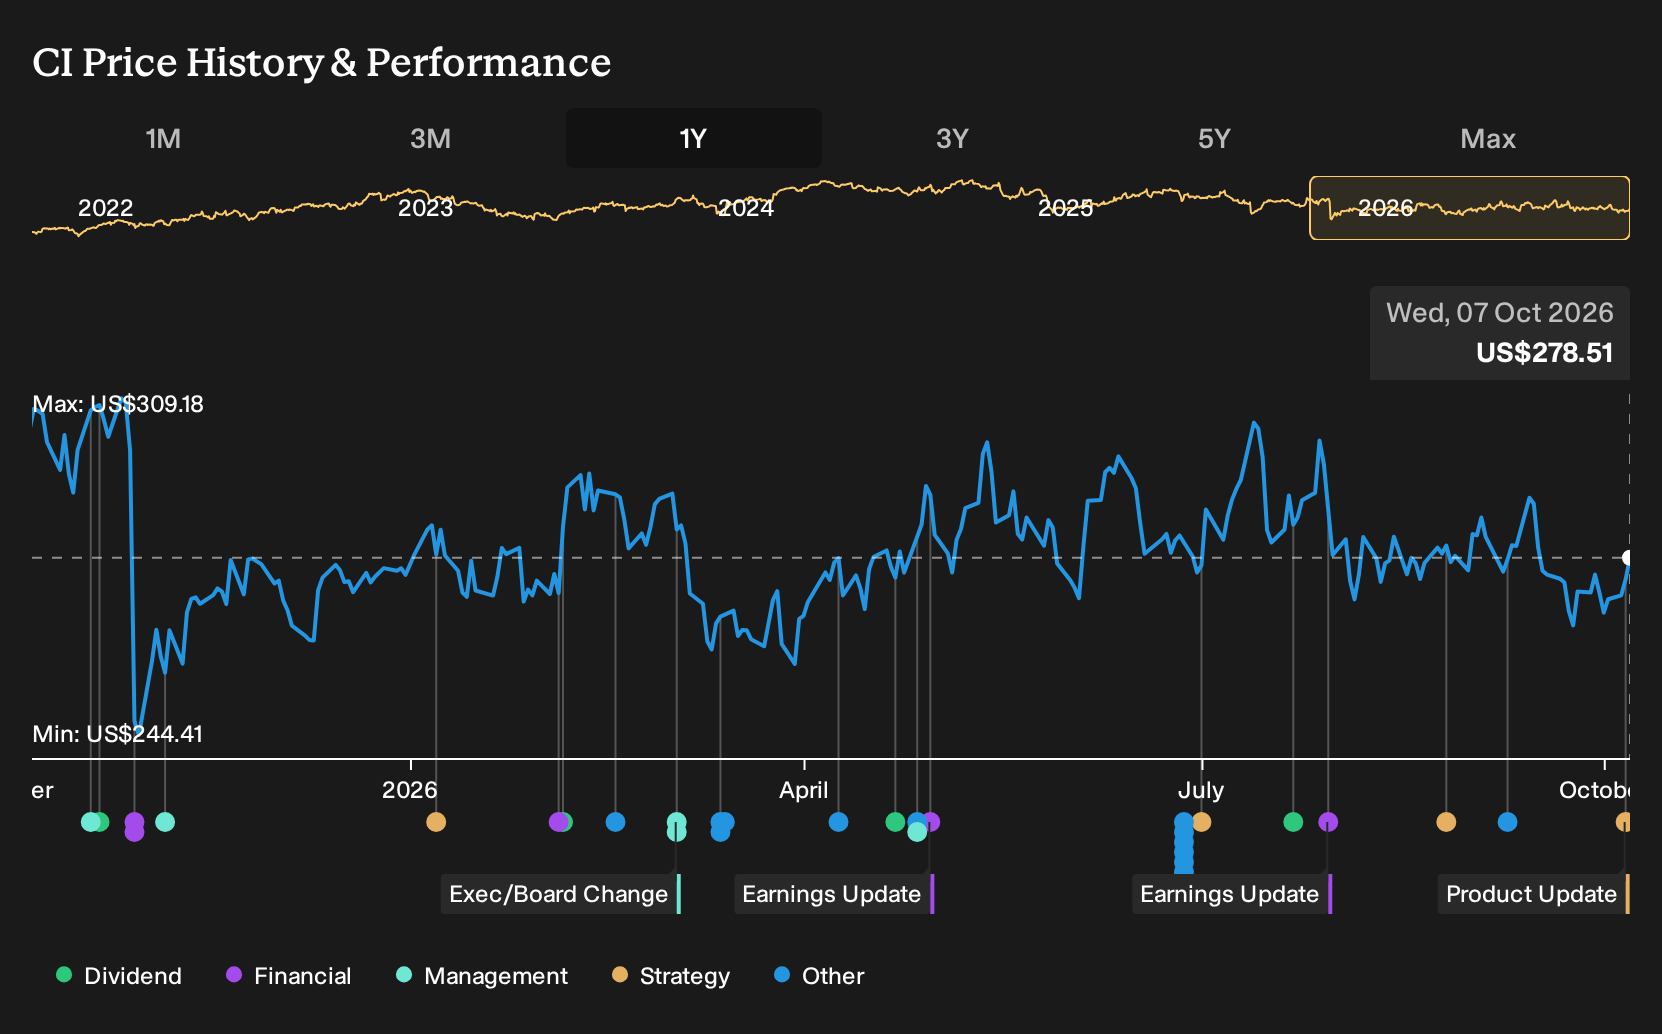
Uncover how Cigna Group's fair value indicates a 22% potential upside to its current price before the gap between price and value closes.
Exploring Other Perspectives
Six fair value estimates from the Simply Wall St Community span roughly US$310 at the low end to more than US$900 at the top, so retail opinions on Cigna Group are clearly all over the map. Those views now collide with real execution questions around Evernorth margins, ACA exit drag and whether AI programs like Health Sense can offset cost pressure. Expect disagreement and use these contrasting viewpoints as a prompt to explore several alternative angles before deciding how Cigna Group fits into your own portfolio thesis.
Explore 5 other Cigna Group fair value estimates, including one that suggests potential upside of up to 234% from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cigna Group research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Cigna Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cigna Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Cigna Group?
If Cigna Group has sharpened your focus on healthcare and data driven models, it can help to widen the lens and compare it with other listed businesses that share some of the same themes or risk profiles. The Simply Wall St Screener lets you do that quickly by filtering for fundamentals that match the kind of balance sheet strength, income profile or upside potential you want to target next.
- For investors who want potential upside with stricter entry criteria, start with a curated pool of 20 high quality undiscovered gems that already clear quality and fundamentals checks.
- If capital preservation is your first filter, narrow your universe to 31 resilient stocks with low risk scores that score well on financial resilience and risk factors.
- For readers building a watchlist around financial strength and durability, use the Screener to zero in on a list of solid balance sheet and fundamentals (25 results) that might sit alongside or compete with Cigna Group in a portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com