


If you had backed SSAB on 7 October 2025, you would have been weighing bullish green-steel ambitions against warnings about stalled decarbonization projects and stubborn global overcapacity. Holding SSAB over the past year would have returned 51.8%, including dividends. With fresh headlines on fossil-free power lines for Luleå, greener Oxelösund capacity and new defense-grade steel powders now on the table, how much of that original dilemma would still look balanced today?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
This theme extends beyond SSAB. See which of 43 power grid technology and infrastructure stocks may still merit a closer look.
The Two Stories SSAB Investors Had In Front Of Them
The shares cost SEK63.7 at the start of the period, and anyone looking at SSAB then had to choose between two very different but credible stories.
On the upside, the bull Narrative put Fair Value at SEK68.58. That view leaned on SSAB’s push into fossil free steel through HYBRIT and SSAB Zero, with analysts building in revenue growth of 2.1% a year and profit margins rising from 4.5% to 6.7%.
The bear Narrative anchored Fair Value at SEK52. It focused on delays in decarbonization projects such as the Luleå mini mill and on global overcapacity, with assumed revenue flat and margins only edging from 4.5% to 4.6%.
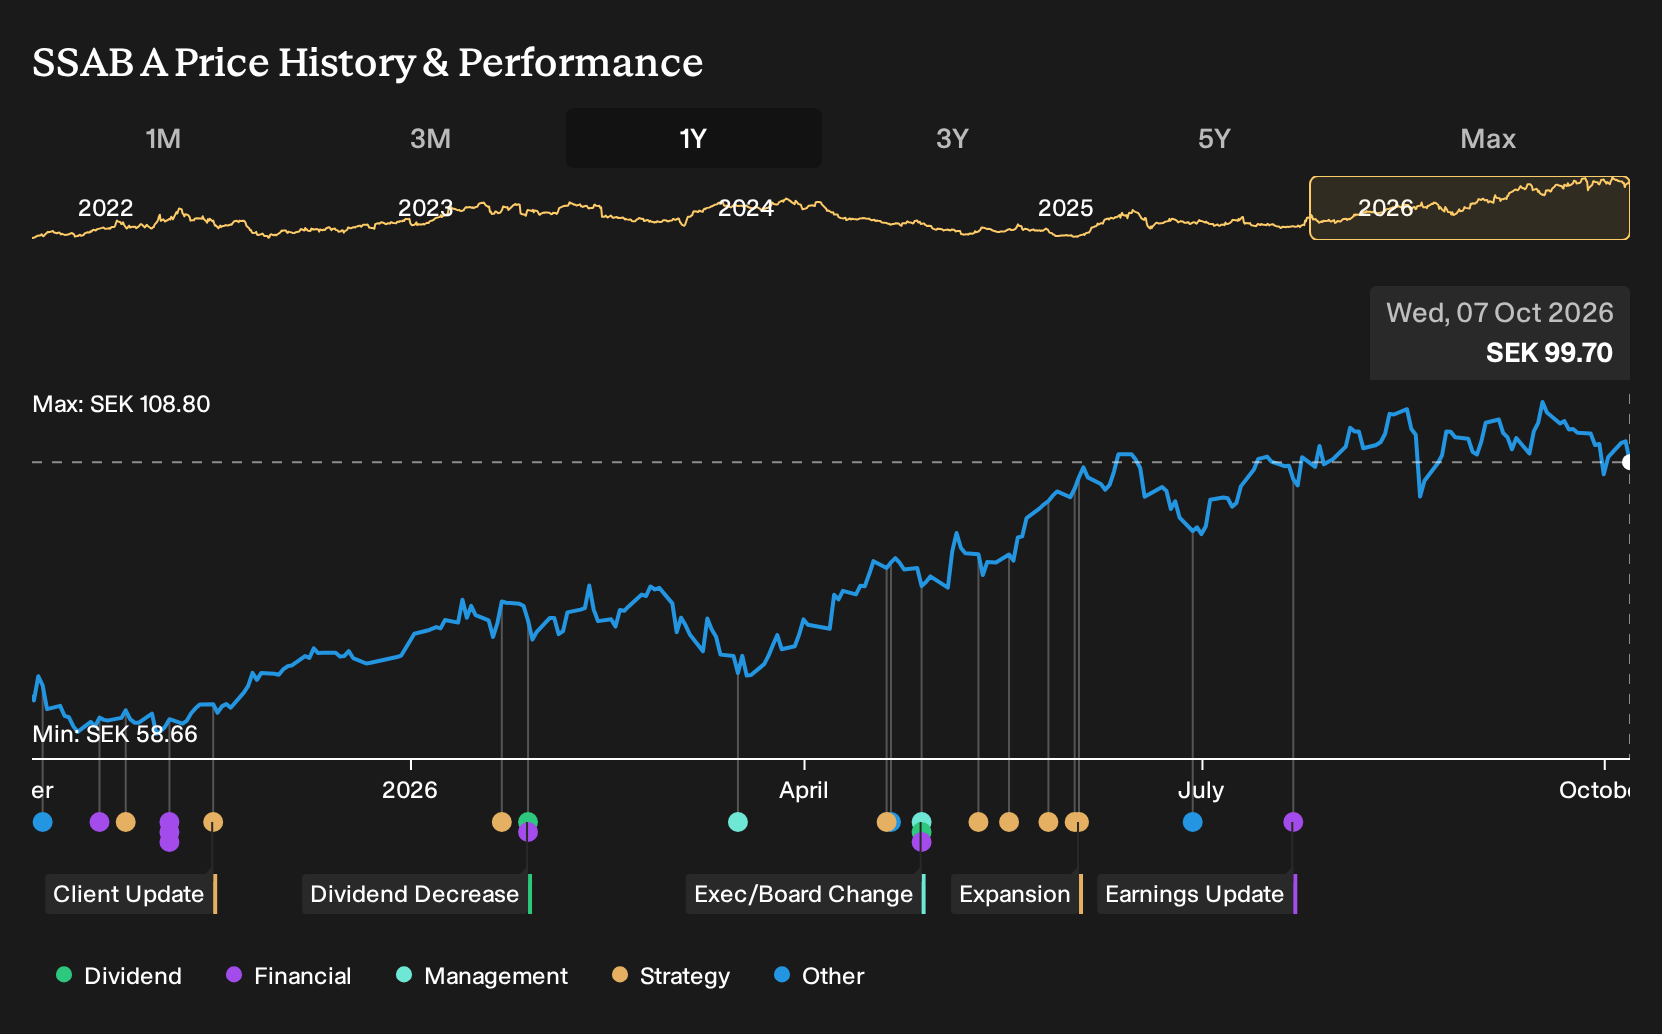
What The Evidence Did To The SSAB Argument
SSAB’s launch of Armox 500 AM Powder and the planned Oxelösund powder expansion backed the bullish idea that premium, defense-grade and fossil-free steel products could deepen its moat. Reported results showed revenue at SEK27,489m in Q2 2026 versus SEK25,631m in Q2 2025, with net income also higher and net margin moving from 7.2% to 7.6%. The period therefore supported the optimistic case.
The key lesson is about verification. When a thesis leans on higher mix and pricing power, track segment results, product launches and reported net margin to see whether the promised quality shift is actually appearing in the numbers.
What SSAB's 1 Year Rally Already Prices In
SSAB now trades at SEK99.7 after a 51.8% gain over the past year, while the selected cautious Narrative’s Fair Value sits below the current price.
That Narrative leans on tariff support, European investment and currency effects, so a buyer today must judge whether policy protection and steel demand can keep offsetting the risk of a sharp global slowdown.
"Sweden's traditional steel mill, SSAB is in an enviable position relative to its peers for three reasons: 1) Its plants are strategically well placed on both sides of the Atlantic; thus, it will not be caught between millstones when the US and the EU get entangled in a trade war centred on steel and aluminium. Indeed, the company is set to downright profit from it, when its markets both in the US and the EU will get protection from Chinese and Korean competition."
One Narrative disagrees with today's price. → See where this Narrative says SSAB should trade
SSAB And The Raw Material Question
You have looked at SSAB’s steel story. One step away sits the question of who digs up the input materials.
Steel needs iron ore, and cleaner power systems lean heavily on copper. Your attention can follow that demand upstream.
Another large miner focuses on exactly those resources. It runs sizeable iron ore operations and is building deeper exposure to copper used in electrification.
The link is simple. If builders, grids and manufacturers keep needing more steel and copper, this producer’s role in supplying those basic ingredients only becomes more central.
One Narrative has already put a figure on it. → Uncover the company trading 50% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com