


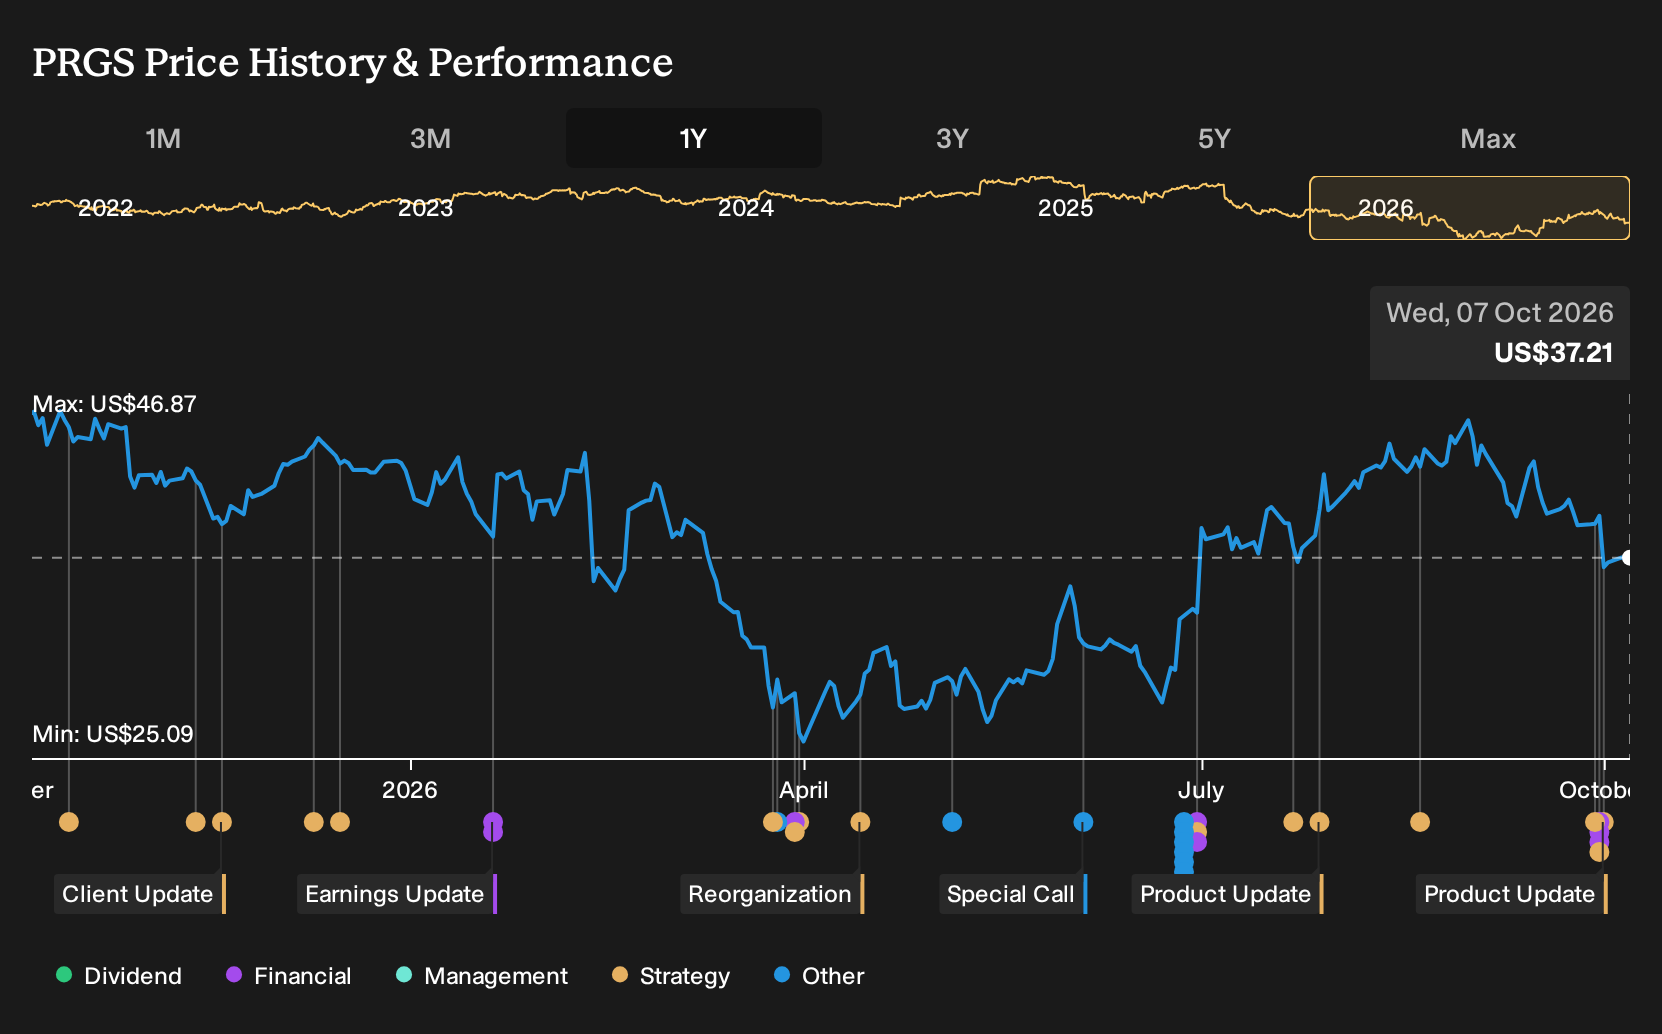
- Progress Software updated investors with a series of AI and security focused product releases and raised full year 2026 revenue and EPS guidance, now targeting US$1.044b to US$1.052b in sales and US$6.15 to US$6.23 in earnings per share.
- The firm is tying these new Agentic RAG, Domo and ShareFile Enterprise capabilities directly into existing workflows like Microsoft Teams and WordPress. This points to a push to drive adoption without costly replatforming or architectural overhauls.
- We will look at how Progress Software's investment narrative evolves given the higher 2026 outlook and expanded AI product footprint.
Scan how Progress Software's AI rollout compares to other potential breakouts by reviewing the hand picked 91 AI infrastructure stocks already pushing hard into mission critical data and security workloads.
What Is Progress Software's Investment Narrative?
To own Progress Software, you need to believe this is an execution story around compound, subscription heavy software rather than a moonshot AI bet. The raised 2026 outlook to US$1.044b to US$1.052b of revenue and US$6.15 to US$6.23 EPS, combined with Q3 profitability, speaks to a model that still prioritizes margins and cash over chasing growth at any cost. Agentic RAG, Domo and ShareFile Enterprise all point in the same direction. Management is trying to plug AI and security into existing workflows where customers already live. This helps adoption without blowing out capital intensity.
In the short term, the key swing factors are whether these new AI features and the Domo integration translate into steady demand and pricing, and whether Progress Software can keep its 38% operating margin target intact while absorbing a break even asset. The completed buyback adds a capital return angle but also matters for per share metrics if earnings flatten. Debt remains a watch item, especially with acquisition spending, so the real test is disciplined integration and cash generation rather than headline product launches.
That said, there is one structural pressure that could still trip this story up if management misjudges...
There's only one way to know the right time to buy, sell or hold Progress Software. Head to Simply Wall St's company report for the latest analysis of Progress Software's Fair Value.
Exploring Other Perspectives
Some of the lowest analysts focus on acquisition risk for Progress Software. They assume revenue hovering near US$1.0b and earnings around US$71.0m, or roughly US$1.56 per share, by 2029. That is a much more cautious story than consensus. These views were set before this AI and guidance news, so expect opinions to evolve.
Explore 2 other Progress Software fair value estimates, including one that suggests it could be worth just $40.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Progress Software research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Progress Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Progress Software's overall financial health at a glance.
Looking For More Investment Ideas Beyond Progress Software?
If you want to pressure test your view on Progress Software against other potential opportunities, the Simply Wall St Screener is an efficient way to scan for stocks that fit your preferred mix of quality, value and risk.
- If you care most about paying a fair price for strong fundamentals, start with a focused group of 29 high quality undervalued stocks that combine earnings strength with balance sheet support.
- If capital preservation ranks high for you, check out a curated 31 resilient stocks with low risk scores that filters for more resilient businesses with steadier risk profiles.
- If you want to spot companies that the market may not be fully watching yet, run through a hand picked 20 high quality undiscovered gems that still show solid underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com