


Donaldson Company (DCI) has drawn investor attention after its shares closed at $87.26, with recent returns mixed across the past week, month and past 3 months. The filtration specialist now invites closer scrutiny of its fundamentals.
Recent trading tells a mixed story for Donaldson Company. The share price slipped 3.2% on the day and is down 4.1% over the past month. However, the 1 year total shareholder return of 6.4% and 3 year total shareholder return of 48.8% suggest momentum has been built more from longer term compounding than short bursts of optimism.
Scan how Donaldson Company compares with other industrial manufacturers by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) for potential ideas in the same space.
Donaldson Company shares have slipped from recent highs while longer term holders still sit on solid gains. Does that recent pullback already offer a fair entry, or does patience make more sense once you see the valuation work up next?
Most Popular Narrative: 13% Undervalued
Compared with Donaldson Company’s last close of $87.26, the most followed narrative points to a fair value of $100.40. This frames today’s pullback as a potential valuation gap rather than a simple loss of momentum.
The main factor that has to go right is that Donaldson Company sustains pricing discipline and portfolio pruning so that recurring aftermarket revenue, currently about two-thirds of total sales, continues to support margins even as Industrial Solutions works through the impact of facility moves and Facet-related expenses.
See why 10 investors see Donaldson Company as 13% undervalued.
Result: Fair Value of $100.40 (UNDERVALUED)
Still, the Donaldson Company story can crack if bioprocessing in Life Sciences stays soft or if Industrial Solutions efforts to fix Facet related inefficiencies drag out.
Find out about the key risks to this Donaldson Company narrative.
Another Take On Donaldson Company’s Valuation
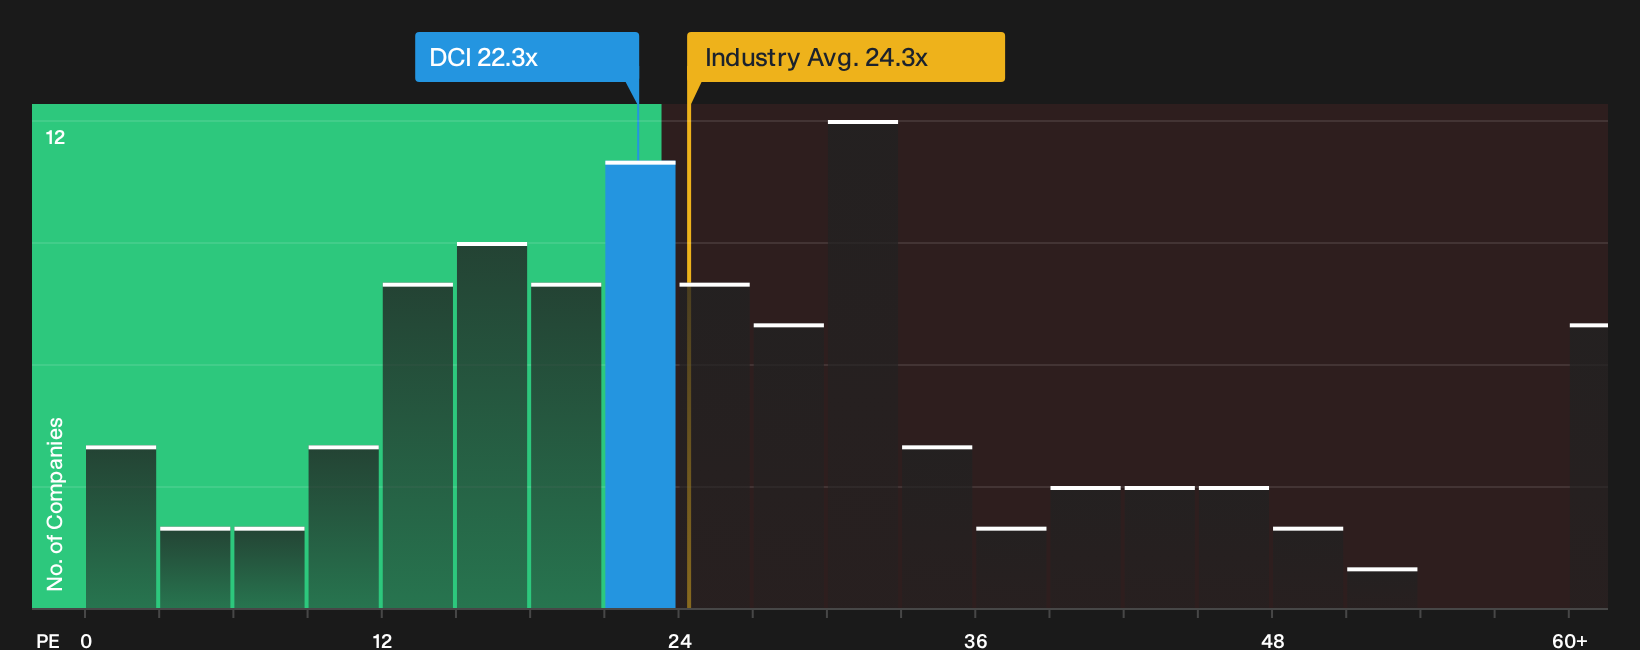
On earnings, Donaldson Company looks slightly expensive. The current P/E of 22.3x sits just above the Fair Ratio of 20.3x and only a touch below the US Machinery group at 25x. That leaves less room for error. Is the market already paying up for the quality on show?
For a closer look at how this P/E gap could close over time, and what that means for valuation risk or upside, see our See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across Donaldson Company’s valuation and narrative can feel confusing, so move quickly, review the underlying data yourself, and weigh both sides of the story. To see the full balance of concerns and positives, review the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Donaldson Company?
If Donaldson Company interests you, do not stop here. Use fresh data backed lists to spot other opportunities before they move beyond your preferred entry range.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) that filters for financial strength and durability.
- Hunt for potential mispriced opportunities by scanning the 29 high quality undervalued stocks built to surface quality businesses trading below their assessed worth.
- Strengthen your income stream by assessing the 8 dividend fortresses that focuses on higher yield payouts supported by underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com