


The United States market has shown positive momentum, rising 2.0% over the last week and climbing 12% in the past year, with earnings projected to grow by 18% annually. In such a dynamic environment, identifying promising stocks often involves looking at smaller companies that may be undervalued yet exhibit strong insider confidence through recent buying activity.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.5x | 0.5x | 30.61% | ★★★★★☆ |
| Surgery Partners | NA | 0.5x | 25.81% | ★★★★★☆ |
| Enovis | NA | 0.4x | 45.88% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.1x | 33.59% | ★★★★☆☆ |
| Five Star Bancorp | 14.4x | 6.2x | 47.80% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.7x | 2.4x | 27.73% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 45.68% | ★★★★☆☆ |
| German American Bancorp | 12.8x | 4.8x | 27.50% | ★★★☆☆☆ |
| Tennant | 61.4x | 0.9x | 20.05% | ★★★☆☆☆ |
| Orion Group Holdings | 101.9x | 0.4x | 45.00% | ★★★☆☆☆ |
We'll examine a selection from our screener results.
Mid Penn Bancorp (MPB)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Mid Penn Bancorp operates as a financial institution providing banking and financial services to individuals, businesses, and institutional clients with a market cap of approximately $0.38 billion.
Operations: Mid Penn Bancorp generates its revenue primarily from banking and financial services, with a recent quarterly revenue of $263.52 million. Operating expenses have been significant, reaching $156.44 million in the latest period, contributing to a net income margin of 25.86%.
PE: 13.3x
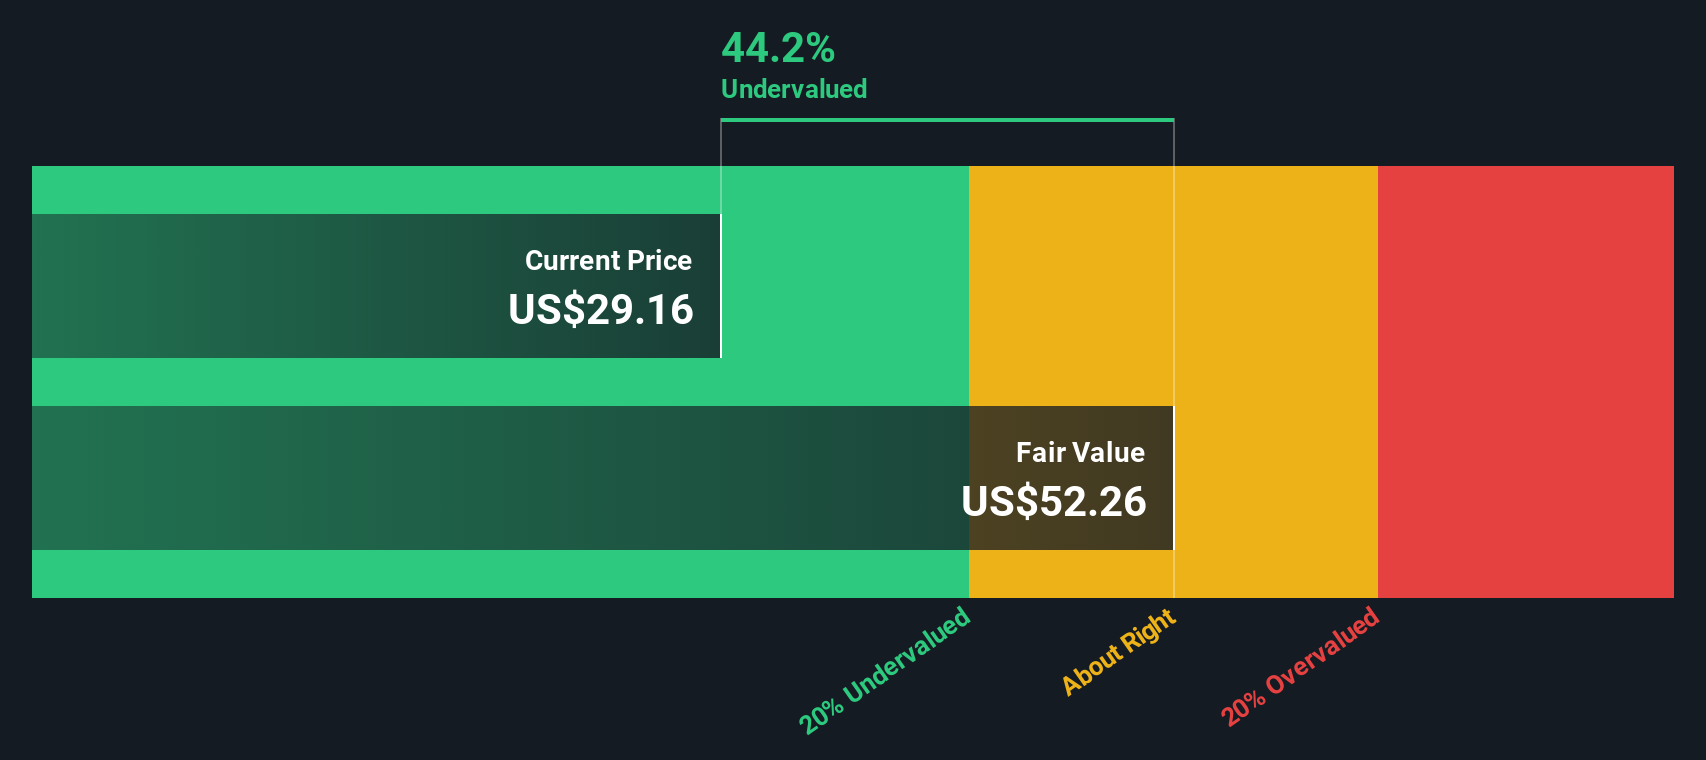
Mid Penn Bancorp, a smaller player in the U.S. banking sector, recently showcased strong financial performance with net income jumping to US$21.69 million for Q2 2026 from US$4.76 million the previous year, indicating potential value amidst its peers. Insider confidence is evident with recent share purchases totaling 76,000 shares for US$2.49 million between April and June 2026. The appointment of Gregory B. Braca as director adds seasoned leadership experience, potentially bolstering strategic growth prospects in an evolving financial landscape.
NexPoint Residential Trust (NXRT)
Simply Wall St Value Rating: ★★★★☆☆
Overview: NexPoint Residential Trust is a real estate investment trust focused on acquiring, owning, and operating multifamily properties in growth markets within the southeastern and southwestern United States, with a market capitalization of approximately $1.29 billion.
Operations: NexPoint Residential Trust generates revenue primarily from its residential real estate investment trust operations, with a recent quarterly revenue of $253.39 million. The company's cost structure includes significant components such as cost of goods sold and operating expenses, which were $101.27 million and $123.57 million respectively in the latest period. A notable trend is the gross profit margin, which was 60.03% in the most recent quarter, reflecting how efficiently it manages its core business activities relative to costs.
PE: -14.9x
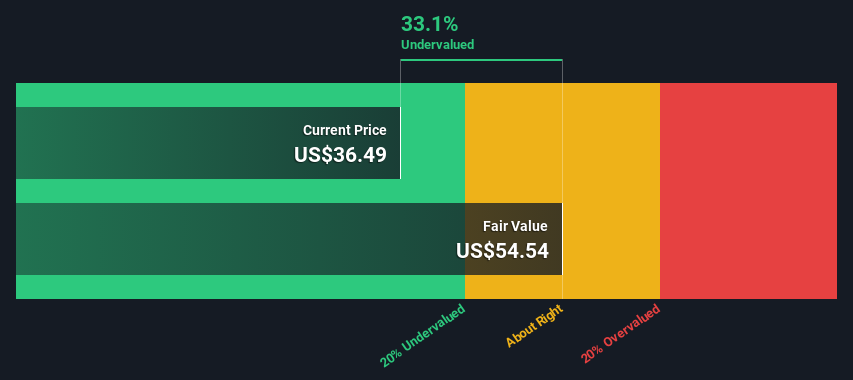
NexPoint Residential Trust, a smaller player in the U.S. market, has recently been dropped from several S&P indices as of September 2026. Despite this setback, insider confidence is evident with recent share purchases by key figures within the company. However, financial challenges persist; earnings are forecasted to decline by 15.6% annually over three years and net losses are projected for year-end 2026 at US$11 million. The company's reliance on external borrowing adds risk but offers potential for those seeking opportunities in undervalued stocks with insider backing.
Sonic Automotive (SAH)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Sonic Automotive is a diversified automotive retailer operating through its franchised dealerships, EchoPark used car stores, and powersports segment with a market cap of $1.72 billion.
Operations: The company generates revenue primarily from its Franchised Dealerships Segment, Echo Park, and Powersports. The gross profit margin has shown variation, with a recent figure of 15.70%. Operating expenses are significant, with general and administrative expenses being the largest component.
PE: 9.0x
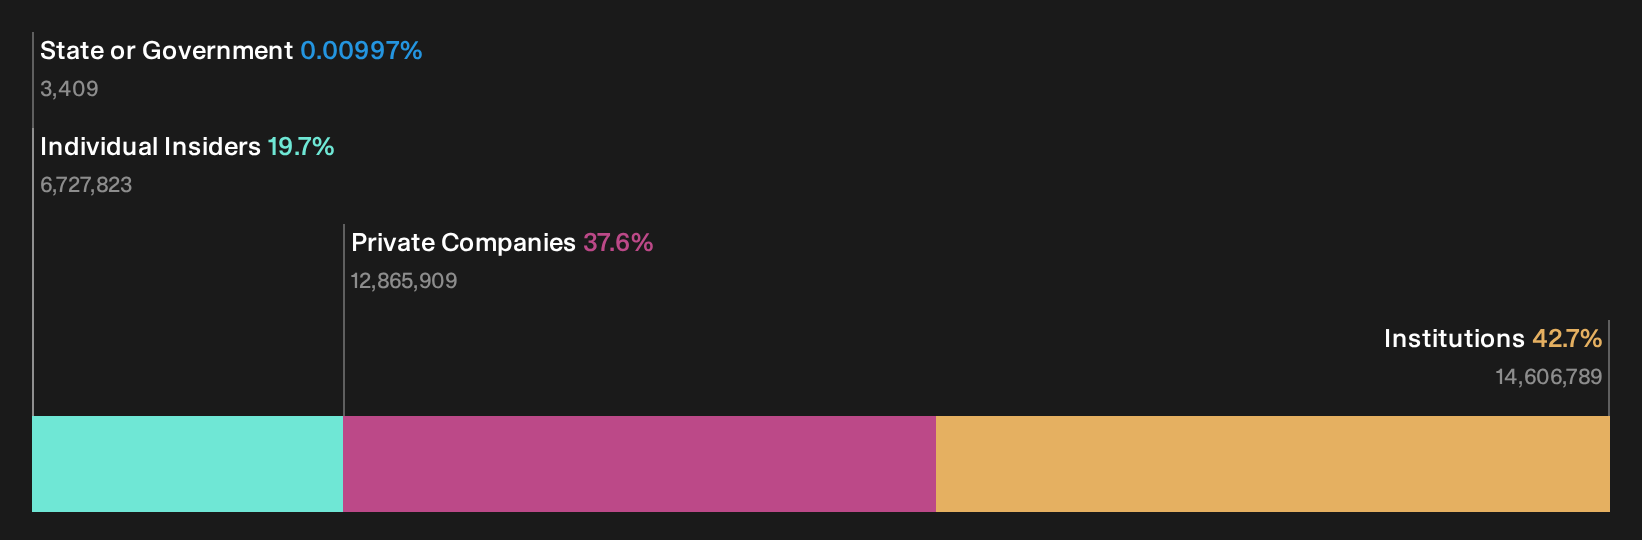
Sonic Automotive, a smaller player in the U.S. market, has been making strategic moves to enhance its position. The company recently completed a substantial share buyback program, acquiring 39.8 million shares for US$1.29 billion by June 2026, signaling strong insider confidence and commitment to shareholder value. Despite relying on riskier external funding sources and having interest payments not fully covered by earnings, Sonic's revenue climbed to US$7.62 billion for the first half of 2026 from US$7.31 billion the previous year, with net income surging significantly to US$118 million from US$25 million year-over-year. With plans for acquisitions and organic investments backed by solid liquidity and balance sheet capacity as stated in their second-quarter earnings call in July 2026, Sonic is poised for potential growth despite financial challenges.
- Take a closer look at Sonic Automotive's potential here in our valuation report.
Understand Sonic Automotive's track record by examining our Past report.
Turning Ideas Into Actions
- Unlock more gems! Our Undervalued US Small Caps With Insider Buying screener has unearthed 62 more companies for you to explore.Click here to unveil our expertly curated list of 65 Undervalued US Small Caps With Insider Buying.
- Already own these companies? Bring clarity to your investment decisions by linking up your portfolio with Simply Wall St, where you can monitor all the vital signs of your stocks effortlessly.
- Unlock the power of informed investing with Simply Wall St, your free guide to navigating stock markets worldwide.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com