


Freedom Holding (FRHC) has just been included in Newsweek's America's Greenest Companies 2026 ranking, highlighting its environmental reporting and projects in Central Asia at a time when many investors are rethinking sustainability risk.
Recent trading has been supportive, with a 7 day share price return of 4.45% and a 30 day move of 6.21% helping lift Freedom Holding to US$174.75. That short term momentum sits alongside a 40.67% year to date share price return and a 3 year total shareholder return of 105.30%, which some investors may now be weighing against the firm’s reported intrinsic discount and evolving perception of its sustainability profile.
Scan how Freedom Holding stacks up against a hand picked 31 resilient stocks with low risk scores that may appeal if this sustainability story has you rethinking where you take risk.
Freedom Holding now trades near US$174.75 while internal valuation work points to an intrinsic discount close to 2%. Does that narrow gap signal fair value, or a wider range of outcomes than the recent move implies?
Preferred P/E of 75.5x for Freedom Holding: Is It Justified?
On simple valuation math, Freedom Holding screens as expensive. The stock closed at $174.75 while trading on a P/E of 75.5x against much lower peer and industry levels.
The P/E ratio compares what investors pay for each dollar of current earnings. For a diversified financial group providing brokerage, banking, insurance, and other services, this measure often reflects what the market is willing to assign to the stability and growth profile of those profits rather than just near term results.
One key tension is that Freedom Holding has strong recent profit momentum alongside a weak longer term earnings track record. Earnings grew 86.3% over the past year and current net profit margins of 8.4% are above the 5.1% level reported last year, yet earnings declined 17% per year over the past 5 years. That kind of mix can leave investors debating whether the current multiple implies a sustained improvement or simply prices in a good recent period.
The comparison with peers is stark. Management is running a business valued on a 75.5x P/E, while the US Capital Markets industry average sits at 39.7x and the direct peer average is 12.5x. That wide gap suggests the market is placing a much richer value on Freedom Holding earnings than on both the broader industry and closer comparables.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 75.5x (OVERVALUED)
Still, any slip in Freedom Holding earnings or a shift in sentiment toward high P/E financial stocks could quickly test how durable this premium really is.
Find out about the key risks to this Freedom Holding narrative.
Another View On Freedom Holding’s Value
The P/E argument paints Freedom Holding as expensive, yet the SWS DCF model sends an even starker message. On those cash flow assumptions, an estimated value of about $60.30 per share sits a long way below the current $174.75 level. That kind of gap raises a simple question for investors: Is this a mispriced risk, or is the market betting that today’s cash flow profile understates what Freedom Holding can deliver over time?
Look into how the SWS DCF model arrives at its fair value.
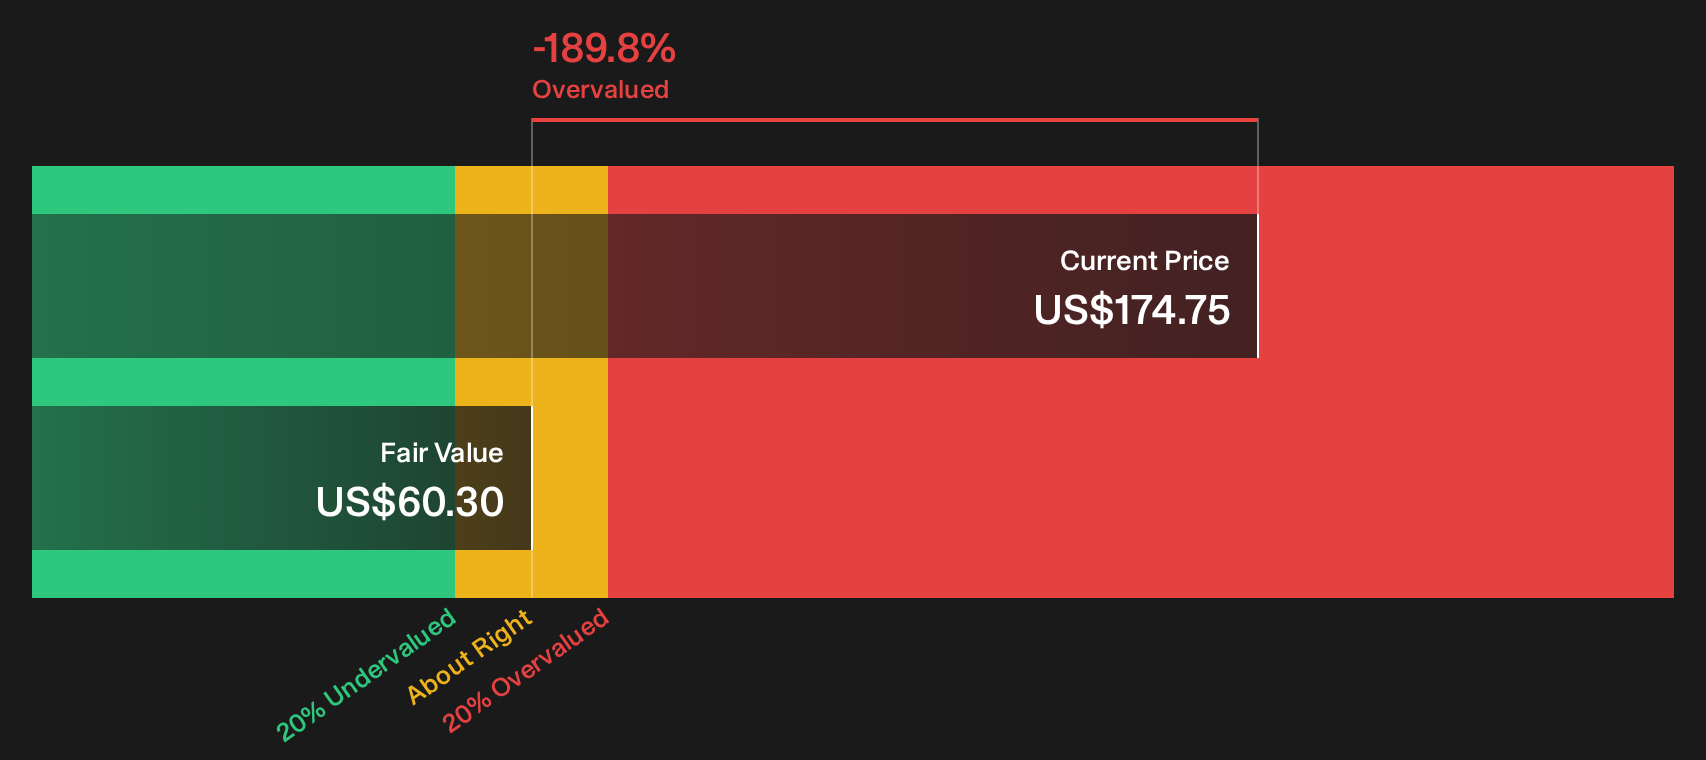
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Freedom Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With extensive debate around Freedom Holding’s valuation and sustainability profile, it can be helpful to review the evidence yourself, compare the potential upside and the weak spots, and then weigh the 1 key reward and 2 important warning signs
Looking for more Freedom Holding sized ideas?
If Freedom Holding has you rethinking where you want risk and reward, do not stop here. The next move could come from a very different corner of the market.
- Target resilience first by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on businesses with financial strength at the foundation.
- Hunt for potential mispriced opportunities through a curated 29 high quality undervalued stocks that filters for quality alongside compressed expectations.
- Stack potential income on top of capital returns by reviewing a 8 dividend fortresses built around higher yielding payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com