


Golar LNG (GLNG) has put another marker down in floating liquefied natural gas. The company is buying the 2013-built LNG carrier Grace Dahlia to convert into its fourth FLNG unit, featuring larger storage capacity and earlier delivery timing.
Recent trading shows Golar LNG giving back some ground in the very short term, with a 1-day share price decline of 1.78% and a 30-day share price return down 5.72%, while the year-to-date share price return is 29.49% and the 1-year total shareholder return is 31.43%.
Scan how Golar LNG compares with other energy infrastructure players by reviewing our hand-picked 43 power grid technology and infrastructure stocks that is shaping long-term capacity and cash flow potential.
Golar LNG has surged this year even as the share price has cooled in recent weeks, leaving a wide gap between the current US$49.14 level and published value estimates. Where does fair value actually land in that spread?
Most Popular Narrative: 25.9% Undervalued
On the most followed view of Golar LNG, a fair value of $66.28 sits well above the recent $49.14 close. This puts the current price squarely against a higher long term cash flow story built around FLNG contracts and backlog.
The company has secured long-term (20-year) charters for its existing FLNG units, providing $17 billion in contracted EBITDA backlog and 20 years of cash flow visibility. This is expected to drive a significant (4x) increase in EBITDA and contracted free cash flow by 2028, indicating the market may be undervaluing its forward earnings stability and revenue growth.
See why 25 investors see Golar LNG as 26% undervalued.
Result: Fair Value of $66.28 (UNDERVALUED)
Still, the Golar LNG story leans heavily on continued LNG demand and smooth execution on capital intensive FLNG projects. Delays, cost overruns or weaker contracts could quickly challenge the current fair value narrative.
Find out about the key risks to this Golar LNG narrative.
Another View: Golar LNG Looks Expensive On Earnings
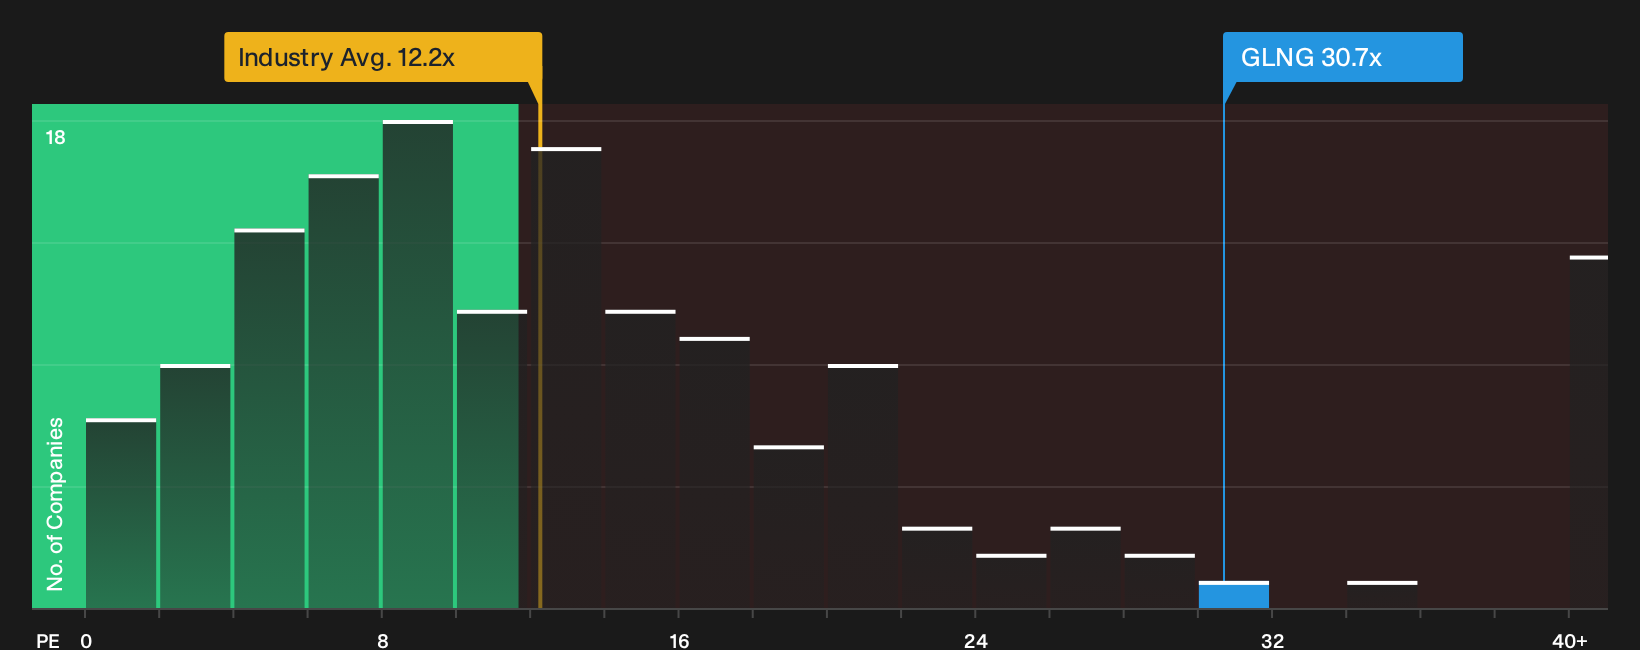
There is a very different picture when Golar LNG is viewed through simple earnings ratios instead of long term cash flow models. The stock trades on a P/E of 30.7x, while the US Oil and Gas industry sits at 12.3x and peers average 12.5x. The fair ratio is 29.6x, which points to Golar LNG as slightly expensive on this yardstick and raises a basic question for you. Is this premium something you are comfortable paying for the story outlined above, or not?
To see how that premium lines up against the underlying numbers and future assumptions, take a closer look at our valuation breakdown, including the fair ratio and peer comparisons, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Golar LNG is clearly split, with both concerns and bright spots on the table. Move quickly, review the underlying data, and decide how it fits your own risk tolerance and time horizon using the 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Golar LNG?
If Golar LNG has sharpened your focus on pricing, do not stop here. Broaden your watchlist now or you risk missing your next strong idea.
- Target resilient balance sheets by scanning companies on the list of solid balance sheet and fundamentals (25 results) that combine financial strength with room for future capital allocation.
- Hunt for mispriced opportunities using the 29 high quality undervalued stocks that highlight businesses with quality fundamentals trading below fair value estimates.
- Spot early-stage potential by reviewing the 12 elite penny stocks with strong financials that filters for smaller companies with stronger financial profiles than the typical microcap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com