


China Mengniu Dairy buybacks put capital returns in focus
China Mengniu Dairy (SEHK:2319) has been active in the market, completing share repurchases under its 2025 and 2026 buyback programs. Together, these repurchases retired more than 41 million shares for over HK$587 million.
Recent buybacks land at a time when China Mengniu Dairy’s share price has moved to HK$17.55, with a year to date share price return of 17.55% but a 5 year total shareholder return that has declined 56.35%. This points to improving short term momentum after a difficult longer stretch.
Spot opportunities with similar capital return stories by scanning our hand picked 184 high quality undervalued stocks, which also pair buybacks and balance sheet strength.China Mengniu Dairy has a fresh buyback story, a share price around HK$17.55 and a long term chart that still shows heavy damage. Is this an entry to lean into now, or one to wait on while you weigh the valuation?
Most Popular Narrative: 25% Undervalued
China Mengniu Dairy’s most followed valuation story points to a fair value of around HK$23.49, compared with the last close at HK$17.55, which frames the recent buybacks as part of a wider rerating argument.
Diversification into high-growth segments such as fresh milk, cheese, yogurt, and overseas expansion in Southeast Asia, Africa, and Latin America broaden Mengniu's addressable market and reduce domestic concentration risk, likely contributing to stronger and more resilient top-line revenue growth.
See why 8 investors see China Mengniu Dairy as 25% undervalued.
Analysts building this narrative are using a 7.07% discount rate and assume annual revenue growth a little above 5%, with profit margins eventually settling above 6%. On those inputs, the implied fair value of HK$23.49 sits well above the current HK$17.55 share price, which is where the 25% undervalued label comes from.
That story links directly to the capital return angle. Analysts expect earnings to grow quickly while the share count edges lower by around 0.15% a year, which means any future profit pool is being spread across slightly fewer shares. For investors watching China Mengniu Dairy, the combination of repurchases, margin assumptions and revenue growth expectations is central to whether this valuation gap looks justified or too optimistic.
Result: Fair Value of HK$23.49 (UNDERVALUED)
Still, the narrative around China Mengniu Dairy can unravel if weak demand in core liquid milk persists or if investment losses like those tied to Modern Dairy continue to weigh on profits.
Find out about the key risks to this China Mengniu Dairy narrative.
Another View on China Mengniu Dairy’s Valuation
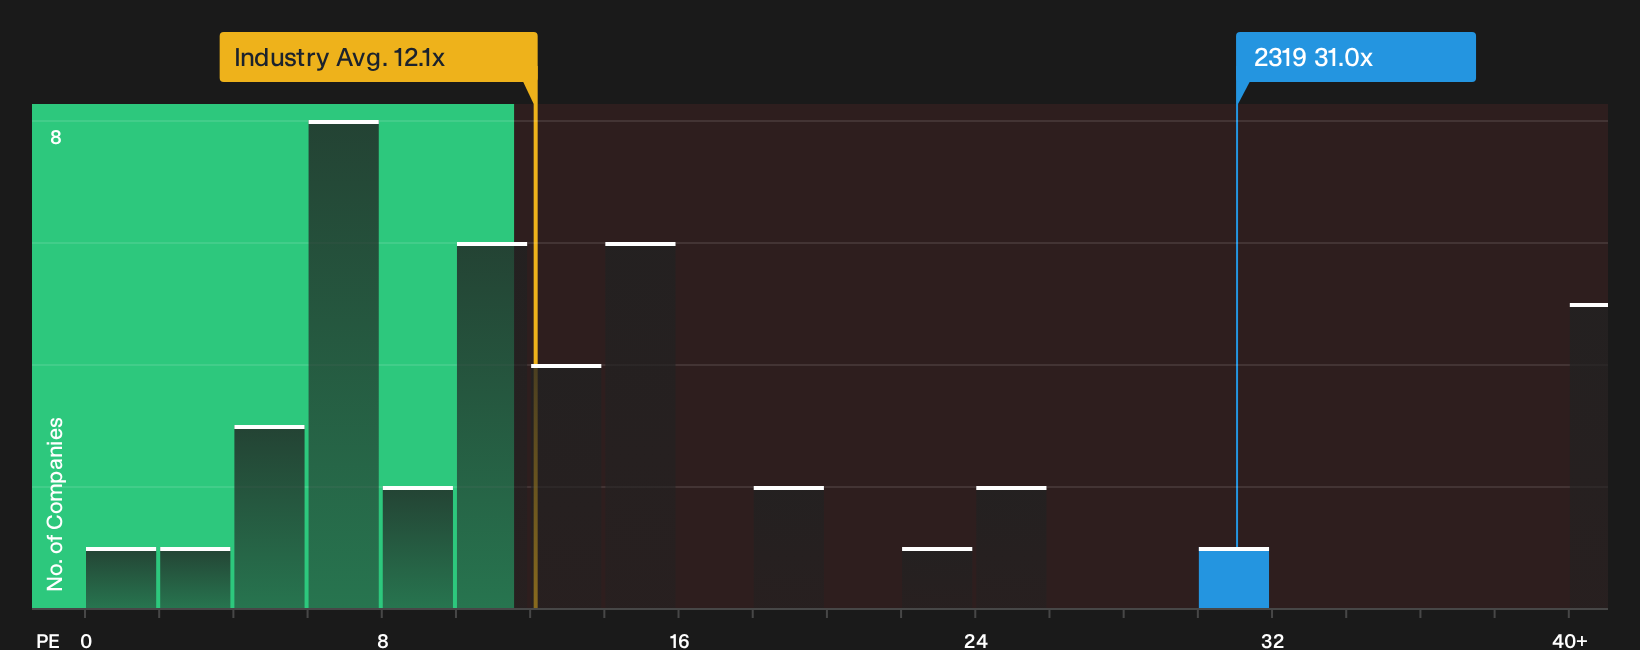
The story shifts once the focus moves away from discounted cash flows and onto what investors are paying for each dollar of earnings today. On a P/E of 31x, China Mengniu Dairy trades at more than 2.5x the Hong Kong Food industry average of 12.1x and above its own fair ratio of 20.4x. That sort of premium points to higher valuation risk if earnings or sentiment slip, so the question is whether you see enough earnings momentum to justify paying a higher price.
For a closer look at how this earnings multiple compares across peers and against that fair ratio the market could move toward over time, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around China Mengniu Dairy’s buybacks and valuation can feel messy, so move fast, pull up the numbers yourself and pressure test both sides by weighing the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond China Mengniu Dairy?
Do not stop with one stock story. Use this momentum to widen your watchlist and pressure test fresh ideas that could suit your own approach.
- Target potential mispricings by scanning the 184 high quality undervalued stocks that combine solid fundamentals with what may be attractive entry points.
- Strengthen income potential by reviewing the 225 dividend fortresses that focus on higher yielding businesses with robust payout profiles.
- Reduce portfolio stress by hunting through the 225 resilient stocks with low risk scores designed to highlight companies with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com