


- Loblaw Companies has refreshed its PC Nutrition First pet food line with veterinarian formulated dry dog and cat recipes, positioned in grocery aisles at up to 40% lower price per 100g than comparable specialty store products and tailored to varied life stages, breeds, and nutritional needs without artificial flavours or synthetic colours.
- This push into higher quality private label pet nutrition highlights how Loblaw Companies is using everyday categories to reinforce value, widen its grocery appeal, and potentially deepen loyalty across households that already visit its stores for food, pharmacy, and other essentials.
- We will now look at how Loblaw Companies' value focused, veterinarian formulated pet food refresh could influence the broader investment narrative.
Scan beyond Loblaw Companies and this pet food refresh to compare it with other value focused retailers on our hand picked 7 high quality undervalued stocks list.
Loblaw Companies Investment Narrative Recap
Loblaw Companies may appeal to you if you believe a broad food, pharmacy, and financial services platform can keep pulling in steady traffic while squeezing more value from private label and loyalty data. The recent PC Nutrition First refresh fits that view but does not fundamentally change the near term story, which still hinges on consistent same store sales and disciplined costs.
The biggest short term swing factor remains margin resilience as shoppers lean harder into discount formats and value banners. Key risk sits around pricing scrutiny and cost inflation. Any squeeze on gross margin or added regulatory burden would matter more to the investment case than this specific pet food update.
The reformulated PC Nutrition First line is most relevant because it touches several existing catalysts in one move. Investors get a higher quality private label offer, tighter health and wellness positioning, and another reason for households to keep more of their weekly spend inside Loblaw Companies stores and digital channels.
Execution detail matters here. Success depends on supply chain reliability for pet products, clear in store communication, and effective use of PC Optimum data to target pet owners without giving up margin through excessive promotional activity. If Loblaw scales this kind of value focused, specialty style offering, it could support both traffic and category mix over time.
Loblaw Companies' current analyst narrative points to CA$71.4b in revenue and CA$2.8b in earnings by 2029, based on an assumed 3.1% yearly revenue growth rate and an earnings increase of about CA$0.1b from CA$2.7b today.
Discover why Loblaw Companies' fair value indicates an 11% potential upside to its current price that could close faster than many investors expect.
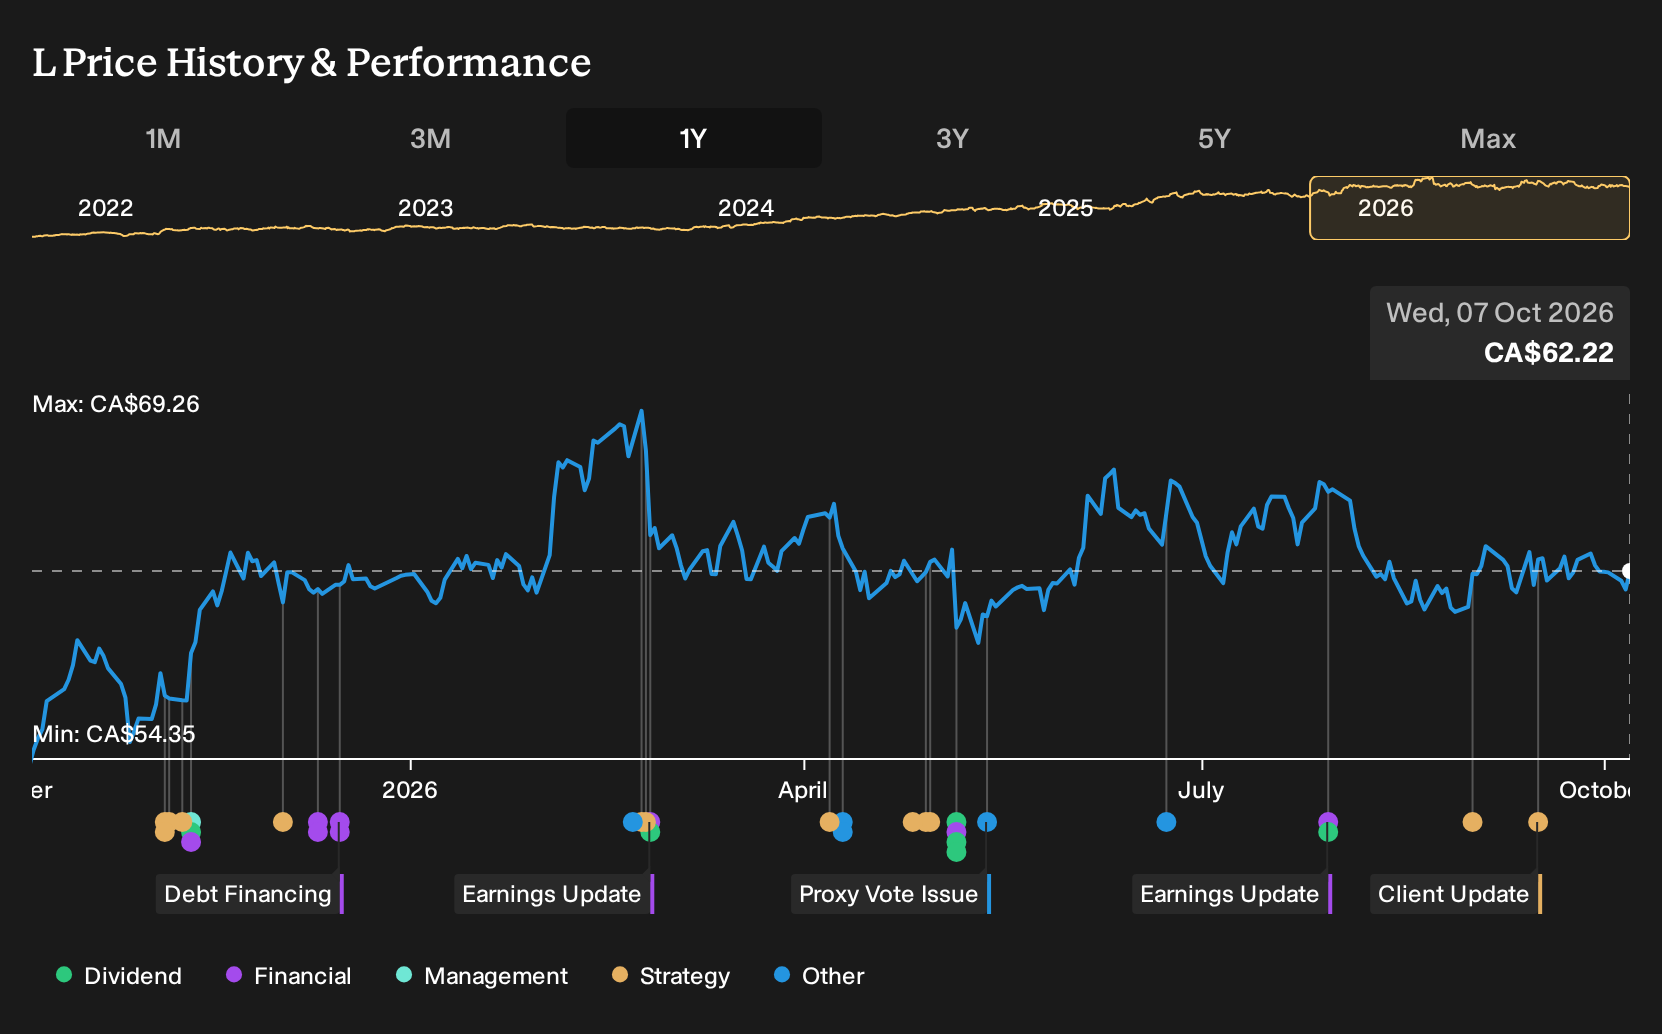
Exploring Other Perspectives
One alternate view leans hard into Loblaw Companies’ expansion plans as a potential upside swing factor. The most optimistic analysts were already assuming revenue of about CA$72.3b and earnings near CA$2.8b by 2029. This new pet food push could nudge those expectations, or challenge them, depending on how you see private label power.
Explore 4 other Loblaw Companies fair value estimates, including one that suggests up to 21% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Loblaw Companies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Loblaw Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Loblaw Companies' overall financial health at a glance.
Looking for more Loblaw Companies sized investment ideas?
Loblaw Companies is only one piece of a much larger opportunity set. If you want to keep building a watchlist that fits your own risk, income, and quality preferences, the Simply Wall St Screener can help you filter the market quickly without losing sight of fundamentals.
- For investors who want mispriced quality on their radar, start with a curated group of value focused candidates through the 7 high quality undervalued stocks.
- If capital preservation and balance sheet strength sit at the top of your checklist, filter for resilient businesses using the list of solid balance sheet and fundamentals (7 results).
- For readers looking to step off the beaten path and research lesser known opportunities, scan a curated pool of underfollowed stocks with the 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com