


National Energy Services Reunited has seen its share price move sharply in recent years, which puts a spotlight on what you are paying for its earnings today. With that kind of track record in the rear-view mirror, the key issue now is whether the current US$23.63 price can be explained by the profit the business is generating.
- Over the past 3 years, National Energy Services Reunited has delivered a total return of about 329.6%, which raises the question of how much future earnings strength is already reflected in the valuation.
- The business model depends heavily on converting energy service activity into consistent profit, which can shape how much investors are willing to pay for each dollar of earnings and how sensitive the stock may be to any change in margins or contract quality.
- There is a second opinion on National Energy Services Reunited worth weighing. See what analysts think National Energy Services Reunited's shares could be worth.
The issue now is whether National Energy Services Reunited's current share price is appropriately aligned with its earnings power.
If you are weighing whether National Energy Services Reunited's recent 3 year return of roughly 329.6% lines up with its earnings, it can help to compare that question across 29 high quality undervalued stocks.
Does National Energy Services Reunited Look Fairly Valued on Earnings?
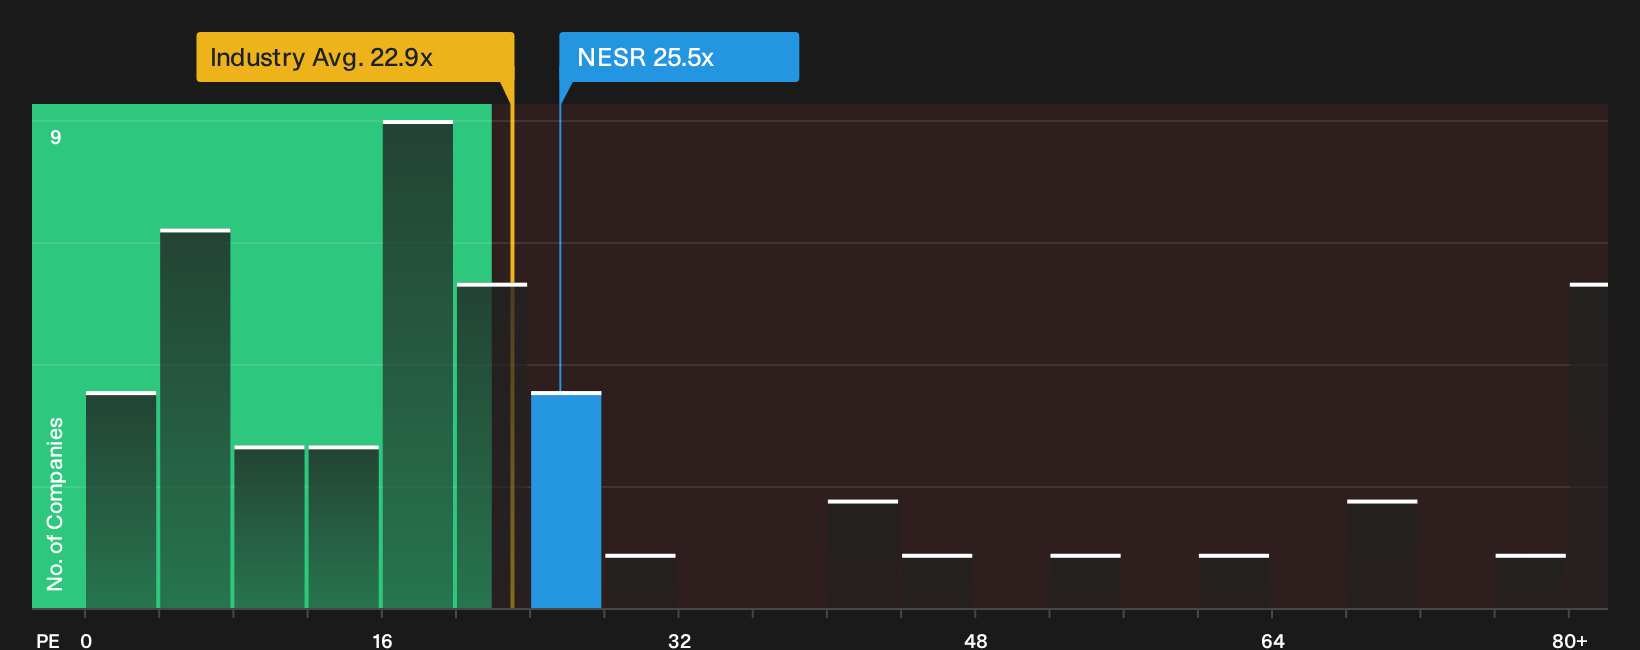
The P/E ratio suits National Energy Services Reunited because earnings are a key focus for investors in an energy services business. On this measure, the stock trades on a P/E of about 25.5x, which is below the peer group average of roughly 38.2x but above the Energy Services sector mean of about 22.9x. This indicates that investors are paying a higher multiple than the broad industry, yet not as much as for many directly comparable companies.
The valuation model suggests a tailored fair P/E level that reflects National Energy Services Reunited's own mix of growth, profitability, size and business risks, and the current 25.5x sits close to that reference point. For anyone assessing the shares, the key question is whether the quality and durability of those earnings justify paying roughly mid 20s times profits, given both the higher sector positioning and the relative discount to peers. Explore the numbers behind National Energy Services Reunited's P/E valuation.
The National Energy Services Reunited Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St extend the P/E debate for National Energy Services Reunited by outlining what kind of future growth, margins and earnings profile would need to hold for the stock to be worth meaningfully more or less than it is today. Each idea presents National Energy Services Reunited's fair value as a specific, testable view of the business that you can track over time, rather than a one-off snapshot.
One of the top community narratives on National Energy Services Reunited: 44% undervalued
"Secured multi year contract durations, growing awards, and a backlog that extends to 2030+ give NESR a high degree of earnings visibility..."
Discover why this Narrative puts National Energy Services Reunited at 44% undervalued.
The price tag on National Energy Services Reunited is only one piece of the decision
National Energy Services Reunited might look reasonable on earnings, but the research checks have also flagged areas of concern that deserve your attention before you place any capital at risk. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com