


Nucor (NUE) is back in focus after a recent pullback, with the stock closing at US$246.44 on 7 October 2026. Investors are weighing that move against strong multi year total return figures.
Recent trading shows that momentum in Nucor has cooled slightly, with the share price down 5.6% over the past month but still up 45.5% year to date. The 1 year total shareholder return of 80.9% underlines how strong the longer term trend has been.
Scan beyond Nucor to see which other steel and materials stocks show similar momentum and valuation profiles using our curated list of 29 high quality undervalued stocks.
After that kind of run, a 5.6% pullback raises a simple issue: Does Nucor still offer enough potential reward for the risks you take at roughly US$246 a share, once valuation enters the discussion?
Most Popular Narrative: 13.1% Undervalued
Nucor is trading at $246.44 against a widely followed fair value estimate of $283.63. The key question is whether the cash flow story behind that gap still holds up after such a strong run.
Nucor's multi year capital program of roughly US$15b to US$20b, with several mills and downstream assets already EBITDA positive and capital expenditure guiding to about US$2.5b in 2026, is moving from the build phase toward cash generation, which can support higher earnings and free cash flow.
See why 100 investors see Nucor as 13% undervalued.
Result: Fair Value of $283.63 (UNDERVALUED)
Still, the story for Nucor only holds if steel demand from nonresidential and infrastructure projects holds up and new mills like West Virginia ramp without prolonged start up issues.
Find out about the key risks to this Nucor narrative.
Another View On Nucor's Valuation
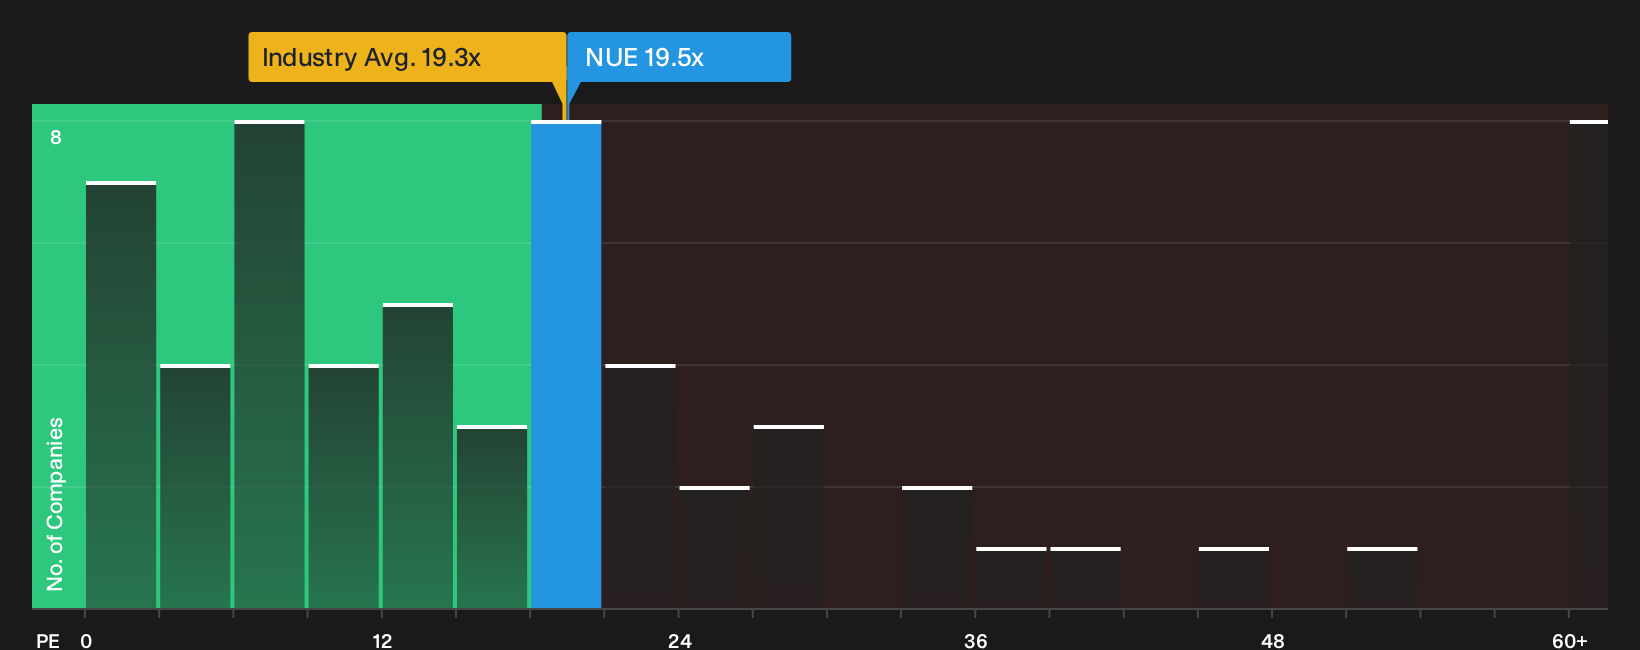
The first take on Nucor leans on fair value estimates tied to future cash flow. A second angle comes from the earnings multiple. The stock trades on a P/E of 19.5x, slightly above both US Metals and Mining peers at 19.3x and its own fair ratio of 22.5x.
This mix tells a different story. Nucor looks expensive next to the industry and peer group on headline P/E, yet still below the level that the fair ratio suggests the market could move toward. That gap raises a simple question for investors: Is the bigger risk overpaying today or underestimating how long the earnings strength can last?
To pressure test that view, it is worth digging into what the numbers say at different earnings levels and multiples, rather than relying on one headline ratio alone. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Nucor's recent gains and pullback only matter if you act on them. Move quickly and pressure test the story yourself by weighing the 3 key rewards and 1 important warning sign
Looking for more ideas beyond Nucor?
If Nucor has your attention, do not stop there. Broader research across sectors gives you more ways to balance risk, income, and long term potential.
- Target steadier potential outcomes by focusing on companies with healthier finances through a curated list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by scanning a 20 high quality undiscovered gems that combines quality fundamentals with quieter market attention.
- Strengthen your income stream by reviewing a focused 8 dividend fortresses that highlights higher yielding payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com