


EBITDA Guidance Pulls Focus After Omnicell Earnings Beat
Omnicell (OMCL) slightly topped revenue expectations in its latest quarter, but management’s EBITDA outlook for the coming period fell well short of market forecasts, shifting investor attention squarely toward cost pressures and future profitability.
At a share price of US$35.21, Omnicell has seen short-term momentum firm up, with a 7-day share price return of 3.41% and a 30-day gain of 2.44%. However, the 90-day share price return has declined 22.77% and the 5-year total shareholder return is down 77.95%, leaving the stock in a longer-term hole. This comes despite a 1-year total shareholder return of 11.96%, which hints at shifting views on its risk and earnings path.
Spot undervalued healthcare tech stories similar to Omnicell by reviewing the hand picked 34 healthcare AI stocks.Omnicell now trades at a steep discount to both analyst targets and some intrinsic value estimates, even after the recent bounce. Is this caution around EBITDA guidance disciplined risk pricing, or is it an overly harsh penalty on the stock’s reset earnings profile?
Most Popular Narrative: 43% Undervalued
Compared with Omnicell's last close of $35.21, the most followed narrative points to a fair value of about $61.29, framing the current price as a steep discount built on specific assumptions about earnings and cash flows discounted at 7.7%.
The continued rollout and adoption of the cloud-native OmniSphere platform across Omnicell's customer base will simplify enterprise-wide medication management, make adding new features and integrating advanced analytics much easier, and accelerate the company's transition to higher-margin, recurring SaaS-based revenues, supporting improved revenue predictability and net margins.
See why 6 investors see Omnicell as 43% undervalued.
Result: Fair Value of $61.29 (UNDERVALUED)
Still, tariff costs projected at about US$15 million and potential pressure on hospital capital budgets could quickly challenge the optimism that underpins the Omnicell fair value story.
Find out about the key risks to this Omnicell narrative.
Another Look At Omnicell Using Earnings Multiples
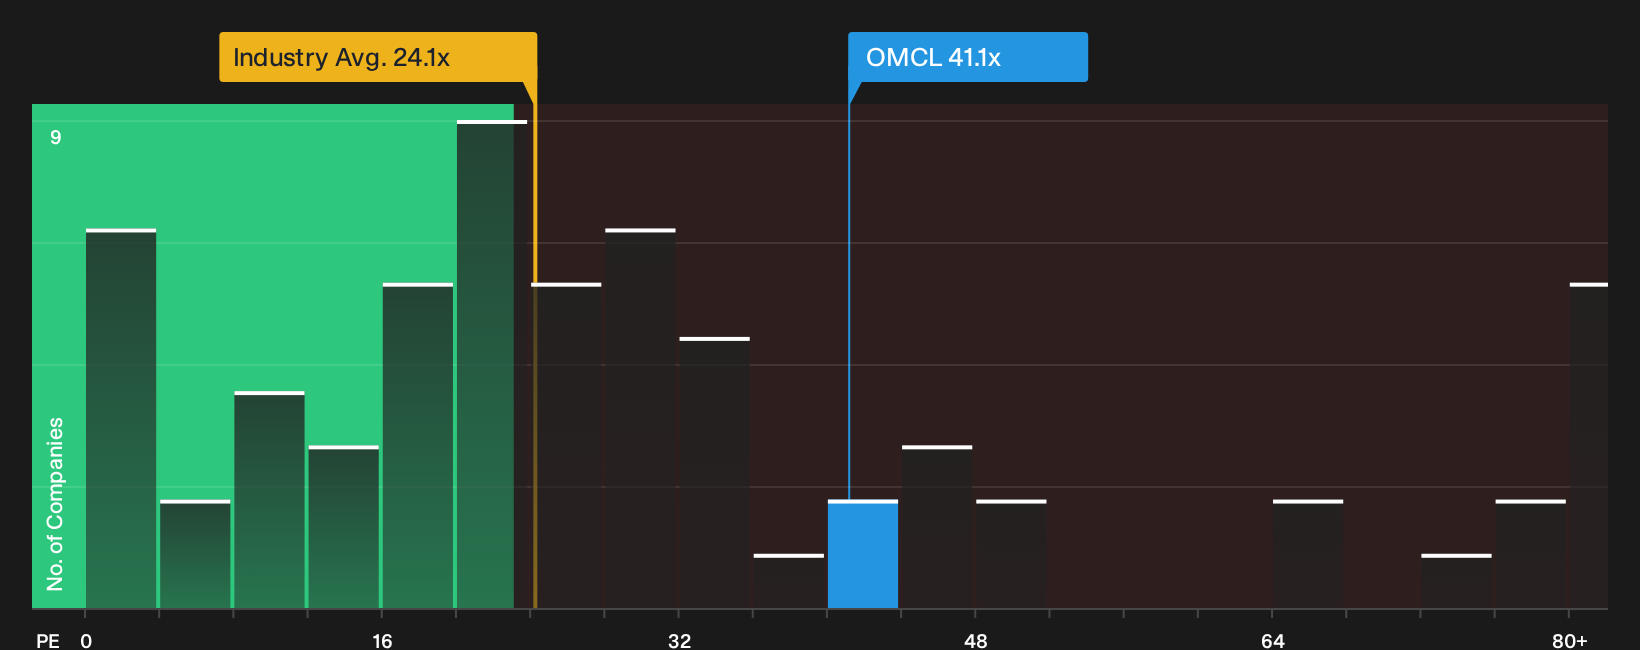
The SWS fair value work paints Omnicell as undervalued, yet the current P/E of 41.1x tells a different story. That multiple sits well above the US Medical Equipment industry at 24.5x, the peer average at 28.2x, and the 27.7x fair ratio that the market could eventually move toward. If sentiment cools on the earnings outlook, is this premium multiple a cushion or a risk zone for late buyers?
See what the numbers say about this price in the detailed valuation breakdown, and how the current earnings multiple compares across peers and against the fair ratio, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this Omnicell story feels split between caution and optimism, move quickly to review the underlying data and pressure test every assumption against your own expectations. To understand what investors see as the bright spots, start with the 4 key rewards.
Looking For More Investment Ideas Beyond Omnicell?
Omnicell may be on your radar today, but the next opportunity you are glad you did not ignore could be sitting quietly in a different corner of the market.
- Target reliable income streams by scanning for rock solid payers using the 8 dividend fortresses.
- Hunt for mispriced quality by filtering for companies that look attractively valued through the 29 high quality undervalued stocks.
- Prioritise capital resilience by focusing on businesses with sturdy finances using the list of solid balance sheet and fundamentals (25 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com