


Warrior Met Coal (HCC) is back in focus for investors after recent trading swings and shifting medium term returns. The share price closed at US$89.57 on 7 October 2026.
Recent trading tells a mixed story for Warrior Met Coal. The share price has slipped 14.3% over the past month but is still up 13.3% across 90 days, while the 1 year total shareholder return of 38.5% and 5 year total shareholder return of 268.4% reflect stronger performance over longer periods.
Scan beyond Warrior Met Coal and compare it with hand picked peers using our screener of 29 high quality undervalued stocks that combine strong fundamentals with potential mispricing.
After a sharp pullback but strong multi year returns, Warrior Met Coal now poses a simple question to buyers: Does the current price still leave enough upside to justify the risk?
Most Popular Narrative: 18% Undervalued
At a last close of $89.57 versus a narrative fair value of $109.33, Warrior Met Coal screens as materially cheaper than the most widely followed thesis suggests. This puts the focus squarely on how sustainable its current cash generation really is.
The ahead-of-schedule and on-budget launch of the Blue Creek longwall in early Q1 2026 accelerates Warrior Met Coal's transition from capital investment to higher-volume revenue generation. Q2 2026 record sales volumes of 3.7 million short tons and a 45% increase in production indicate further potential impact on revenue and net margins as low-cost volumes continue to ramp.
See why 36 investors see Warrior Met Coal as 18% undervalued.
Result: Fair Value of $109.33 (UNDERVALUED)
Still, the thesis around Warrior Met Coal can crack if seaborne steel demand remains weak or if higher freight costs and lower realized prices put pressure on the Blue Creek cash engine.
Find out about the key risks to this Warrior Met Coal narrative.
Another View on Warrior Met Coal’s Valuation
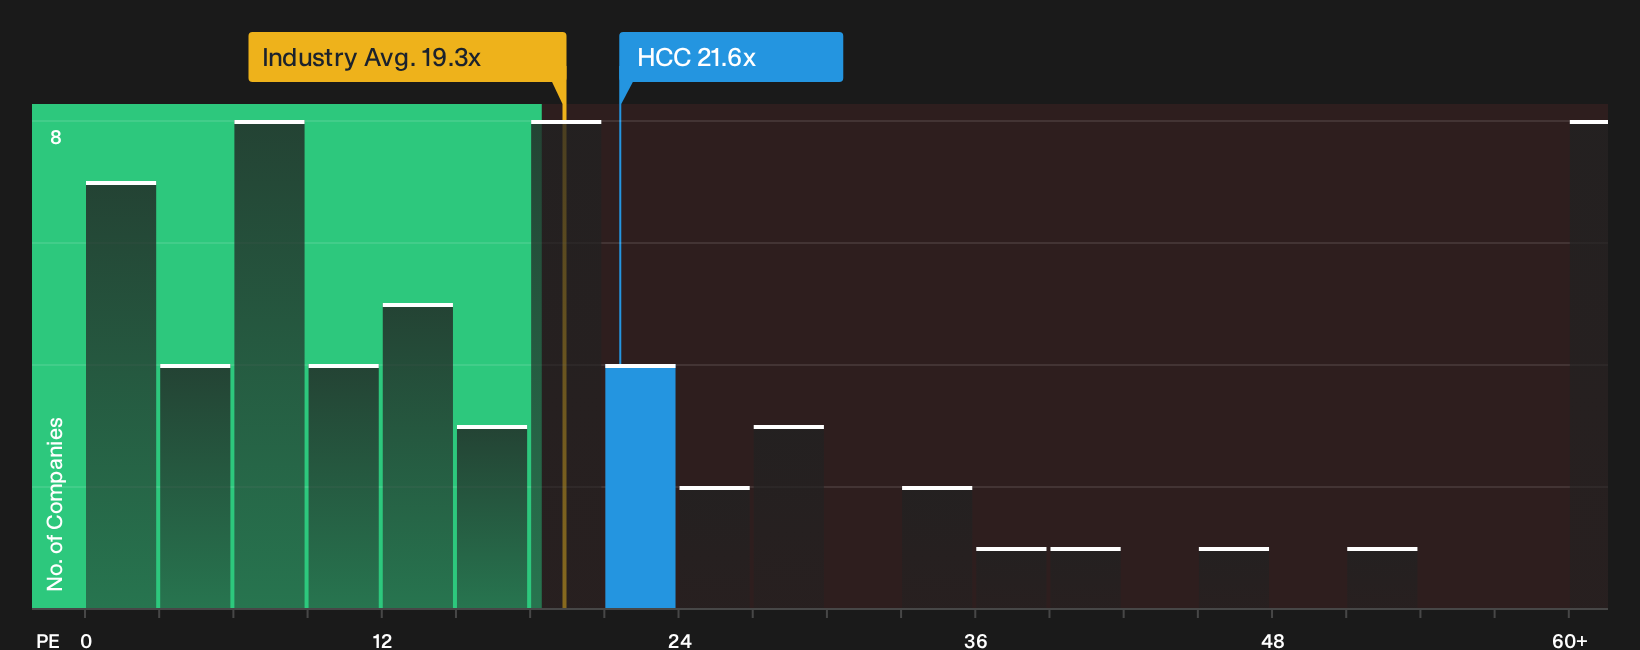
On earnings multiples, Warrior Met Coal screens very differently. The stock trades on a P/E of 21.6x, which is richer than both the US Metals and Mining sector at 19.8x and the peer group at 18.2x, yet close to a fair ratio of 22.7x. That points to less of a clear bargain and more of a debate about how much valuation risk you are willing to hold.
For a closer look at what this pricing gap might mean in practice, including how it could close over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Warrior Met Coal's value often create the sharpest opportunities. Move quickly, look through the data, and decide where you stand after weighing 4 key rewards and 1 important warning sign.
Looking for more Warrior Met Coal style investment ideas?
If Warrior Met Coal has sharpened your focus on price, quality, and risk, do not stop here. Push your research wider and give yourself more options.
- Target resilient balance sheets and fundamentals by reviewing our list of solid balance sheet and fundamentals (25 results) that can help you stress test ideas beyond the latest headline moves.
- Hunt for mispriced strength with the 20 high quality undiscovered gems that spotlight companies where solid business performance is not yet fully reflected in market expectations.
- Prioritise capital preservation while still seeking upside by scanning 31 resilient stocks with low risk scores before fresh money goes into your next position.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com