


With a market capitalization of about $118.4 billion, Booking Holdings Inc. (BKNG) is the world’s leading online travel services provider, operating a portfolio of travel brands across more than 220 countries and territories. Headquartered in Norwalk, Connecticut, the company simplifies global travel through technology, driving innovation, collaboration and customer-focused solutions while supporting millions of travel experiences worldwide.
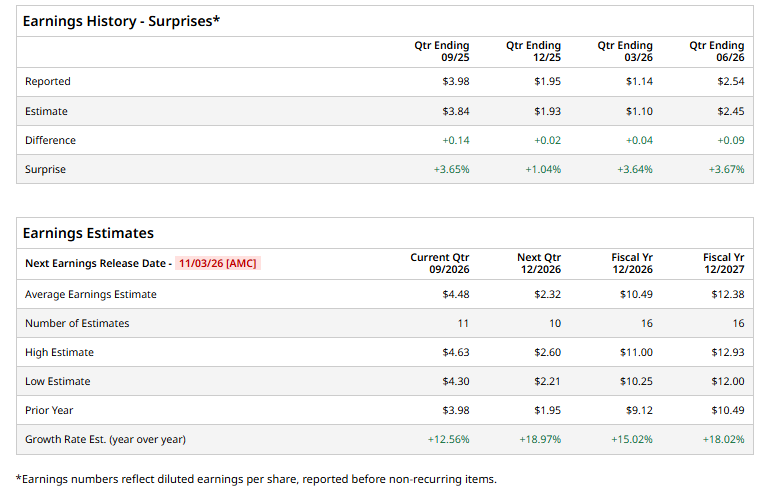
BKNG is set to report its Q3 earnings on Tuesday, November 3, 2026, after the market closes. Ahead of the release, analysts expect the company to report diluted EPS of $4.48, up 12.6% from $3.98 in the year-ago quarter. BKNG has exceeded Wall Street’s EPS estimates in each of the past four quarters, which is impressive.
For fiscal 2026, analysts expect the company to report EPS of $10.49, up 15% from $9.12 in fiscal 2025. Moreover, its EPS is projected to increase another 18% year over year to $12.38 in fiscal 2027.
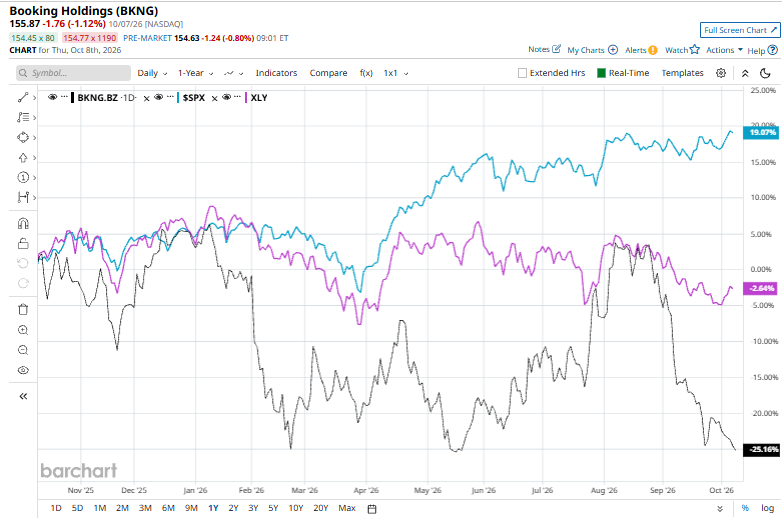
BKNG stock has plunged 25.7% over the past 52 weeks, significantly underperforming the S&P 500 Index ($SPX), which returned 16.2%, as well as the State Street Consumer Discretionary Select Sector SPDR ETF (XLY), which declined 5.5% over the same period.
BKNG’s underperformance has been weighed down by relatively weak customer spending growth and regulatory setbacks that have constrained its expansion strategy. Average revenue per booking increased just 4.1% over the past two years, pointing to limited growth in customer spending and monetization compared with peers.
More recently, regulatory concerns added to the pressure. On September 9, BKNG shares fell 4.8% after the European General Court upheld the EU antitrust decision blocking Booking’s €1.63 billion ($1.83 billion) acquisition of ETraveli Group. The ruling prevented Booking from completing the deal and raised concerns about regulatory hurdles facing its broader acquisition and expansion plans.
Nevertheless, analysts remain bullish on BKNG, with the stock carrying a consensus "Strong Buy" rating. Among the 37 analysts covering the stock, 25 recommend a "Strong Buy," two rate it a "Moderate Buy," and 10 recommend a "Hold." Additionally, the average price target of $236.38 implies potential upside of 51.7% from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.