


Oppenheimer Holdings (OPY) has drawn investor attention after moving sharply in recent trading, with the share price closing at US$118.22. This move comes alongside strong year to date and 1 year total returns.
Recent trading has been choppy, with the 1 day share price return down 1.96% and the 1 month share price return down 3.80%. However, Oppenheimer Holdings still carries strong momentum given a 62.75% year to date share price return and a 74.18% 1 year total shareholder return.
Scan beyond Oppenheimer Holdings and see how it stacks up against 29 high quality undervalued stocks, which also pair strong fundamentals with resilient share price momentum.
Oppenheimer Holdings has already rewarded holders with strong recent gains, while short term performance has cooled. Does the current valuation still offer an attractive balance between upside potential and downside risk for new buyers?
Preferred P/E of 12.3x: Is it justified?
Oppenheimer Holdings trades on a P/E of 12.3x at a share price of $118.22, which sits well below both the US market and sector averages. That pricing suggests investors are paying less for each dollar of current earnings compared with many alternatives in the US capital markets space.
The P/E ratio links what you pay today to the company’s profit stream. For an investment bank and broker dealer such as Oppenheimer Holdings, earnings can be cyclical, so this kind of measure helps you judge what the market is willing to pay for a given level of profitability at this point in the cycle.
Earnings have declined by 8.9% per year over the past 5 years, even though the most recent year showed 17.5% profit growth and high quality earnings. That mix of longer term profit pressure and a recent rebound can help explain why the market is not assigning a richer multiple despite the strong 1 year total return.
The market is assigning a P/E of 12.3x to Oppenheimer Holdings, compared with 18x for the broader US market and 39.7x for the US capital markets industry, which is a steep discount and signals far more cautious expectations than peers.
Result: Price-to-Earnings of 12.3x (UNDERVALUED).
Still, Oppenheimer Holdings relies heavily on revenue from the Americas and cyclical investment banking activity, so any deal slowdown or regional shock could quickly pressure earnings.
Find out about the key risks to this Oppenheimer Holdings narrative.
Another view on Oppenheimer Holdings valuation
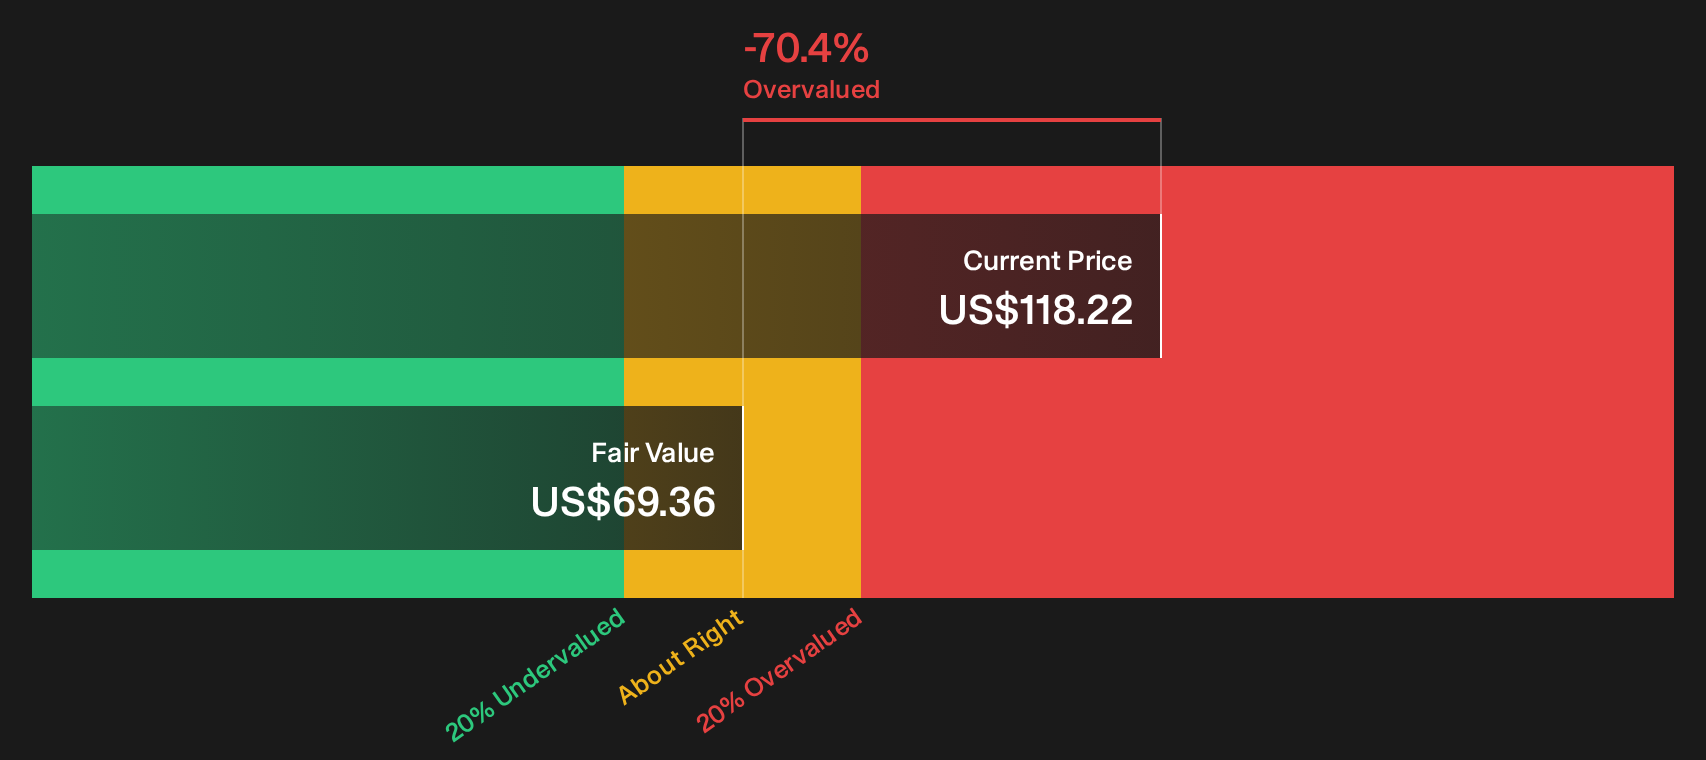
The low P/E makes Oppenheimer Holdings look inexpensive, yet the SWS DCF model paints a different picture. At a share price of $118.22, the stock is trading above an estimated future cash flow value of $69.36, which points to an overvalued reading on this framework.
This gap suggests investors are paying a premium over the cash flow estimate, possibly for current momentum or business mix rather than modeled fundamentals. The question is whether that premium reflects durable strengths, or whether it simply stretches the margin of safety too far for your risk tolerance.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Oppenheimer Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Oppenheimer Holdings can feel confusing, so move quickly from reading to reviewing the numbers yourself, and then weigh both sides of the story using the 1 key reward and 1 important warning sign.
Looking for more ideas beyond Oppenheimer Holdings?
If Oppenheimer Holdings has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist with a few targeted, data driven stock ideas.
- Target sturdier potential performers by scanning for resilient balance sheets and solid fundamentals through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by reviewing companies that combine quality metrics with appealing valuations in the 20 high quality undiscovered gems.
- Prioritise capital preservation by assessing companies flagged for lower overall risk using the 31 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com