


Why H&R Real Estate Investment Trust Is In Focus
H&R Real Estate Investment Trust (TSX:HR.UN) moved into the spotlight after large unitholder Daniel Farb of Mill Pond Capital said he plans to vote against its proposed transaction with GO Residential REIT.
Farb, who holds 2.2 million units, argues the deal does not offer fair value for public investors and raises concerns about leverage, governance and tax treatment compared with the consideration reportedly available to the chief executive's family group.
At a share price of CA$9.26, H&R Real Estate Investment Trust has seen its 90 day share price return fall 16.5%, while the 1 year total shareholder return declined 15%. However, the 3 year total shareholder return is still up 18.6%, which suggests recent momentum has been fading as unitholders digest the GO Residential REIT proposal and other developments around the portfolio.
Scan how H&R Real Estate Investment Trust compares with other real estate plays facing similar pressure points by reviewing our hand picked list of solid balance sheet and fundamentals (7 results).H&R Real Estate Investment Trust now trades at a clear discount to analyst targets, yet its own intrinsic value estimate points closer to fair. Is the current price compressing too much of the recent deal risk, or not enough?
Most Popular Narrative: 21% Undervalued
H&R Real Estate Investment Trust is framed as undervalued in the most followed narrative, with a fair value of CA$11.79 against the last close at CA$9.26. That gap rests heavily on how its Sunbelt residential and balance sheet plans play out.
Asset recycling, including planned sales of selected office, retail and land assets and the use of proceeds to repay debt, is expected to reduce leverage from an already stated pro forma debt to total assets level of 41.8% and debt to EBITDA of 8.7x. This can support interest expense coverage and future earnings stability.
See why 2 investors see H&R Real Estate Investment Trust as 21% undervalued.
Result: Fair Value of CA$11.79 (UNDERVALUED)
Still, the H&R Real Estate Investment Trust story can change quickly if Sunbelt apartment supply continues to keep rent pressure in place or if industrial softness proves to be longer lasting.
Find out about the key risks to this H&R Real Estate Investment Trust narrative.
Another View On H&R Real Estate Investment Trust
There is a catch with the H&R Real Estate Investment Trust story. The SWS DCF model points to a fair value of CA$8.67, which sits below the current CA$9.26 unit price and frames the units as overvalued on cash flow assumptions. Which lens do you trust more: the multiple based narrative or the cash flow math?
Look into how the SWS DCF model arrives at its fair value.
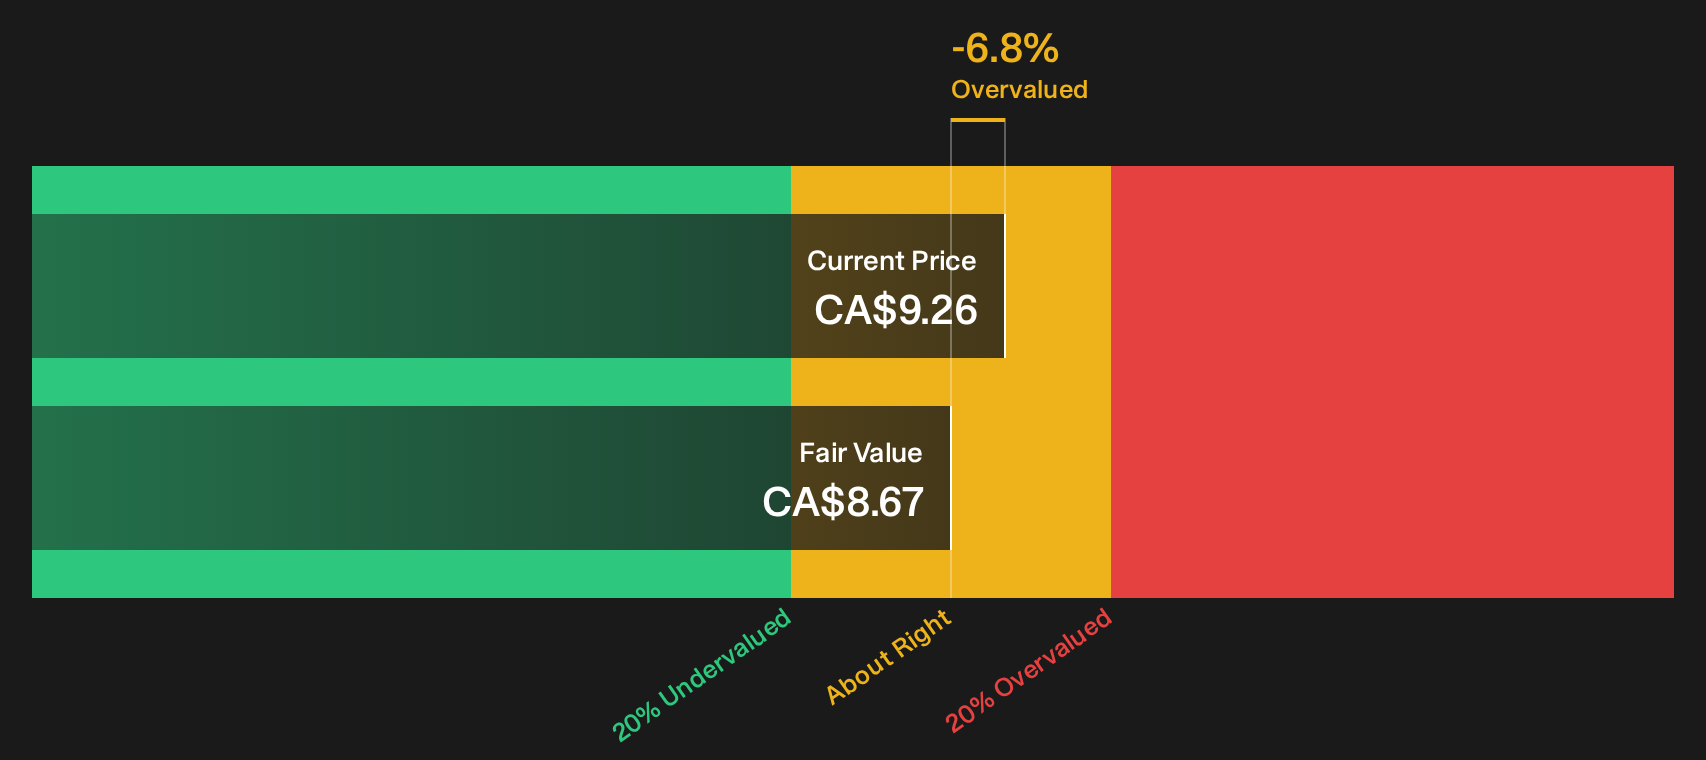
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out H&R Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 7 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With mixed signals around H&R Real Estate Investment Trust, the real question is how you weigh the trade off between concern and optimism. Act quickly, review the underlying numbers and sentiment drivers for yourself, and then anchor your own stance using the balance of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond H&R Real Estate Investment Trust?
If the H&R Real Estate Investment Trust story has you weighing risk and reward, consider broadening your view and adding a few fresh candidates to your watchlist.
- Target stronger balance sheets by scanning companies in the list of solid balance sheet and fundamentals (7 results) that pair financial resilience with more flexibility.
- Look for potentially mispriced opportunities using the 7 high quality undervalued stocks and see which businesses combine quality fundamentals with compressed expectations.
- Build a bench of potential future candidates by checking the 9 high quality undiscovered gems before attention and pricing change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com