


Investor focus on Hubbell ahead of Q3 earnings
Hubbell (HUBB) is back in the spotlight as investors position around its upcoming fiscal third quarter earnings report, with expectations shaped by demand in grid upgrades and AI driven power infrastructure.
Attention is centering on how those themes intersect with Hubbell's cash generation, free cash flow margin, and ongoing share repurchases, which together influence how the business balances growth projects, buybacks, and dividends.
Recent trading has been choppy for Hubbell, with the share price falling 2.1% on the day to US$475.41 but still up 4.8% over the past week as investors position around the upcoming results.
That short term share price momentum sits against a steadier backdrop, with a 2.7% year to date share price return and a 1 year total shareholder return of 14.7%. Meanwhile, the 5 year total shareholder return of about 182% reflects how investors have been rewarding the grid and utility infrastructure story over a longer stretch.
Spot emerging grid and AI power plays alongside Hubbell by scanning our hand-picked 43 power grid technology and infrastructure stocks.Hubbell appears to be a strong cash engine tied to long-term grid and AI power themes, yet after a sharp multi-year run and a recent bounce, investors may question whether the current price still offers enough value for that level of quality.
Most Popular Narrative: 16% Undervalued
Against Hubbell's last close at $475.41, the most followed narrative points to a fair value of $563.25. This implies appreciable upside that is linked to long horizon grid and data center spending rather than short term trading swings.
Hubbell is entering a long period of elevated spending on grid hardening and modernization, supported by a strong Utility Solutions order book, a first half 2026 book to bill of about 1.2x and projects already extending into 2027, which can support revenue and earnings growth visibility.
See why 17 investors see Hubbell as 16% undervalued.
Result: Fair Value of $563.25 (UNDERVALUED)
Still, the Hubbell narrative depends on NSI integration delivering on expectations and on Electrical Solutions margins recovering from recent pressure, rather than drifting lower.
Find out about the key risks to this Hubbell narrative.
Another View on Hubbell's valuation
The earlier narrative leans on future earnings power to argue that Hubbell could be worth about $563.25, yet the SWS DCF model tells a different story. On that future cash flow view, the stock screens as overvalued at $475.41 versus an estimated value of $391.91. That gap raises a simple question for investors: which story feels more realistic for the next decade of cash generation?
Look into how the SWS DCF model arrives at its fair value.
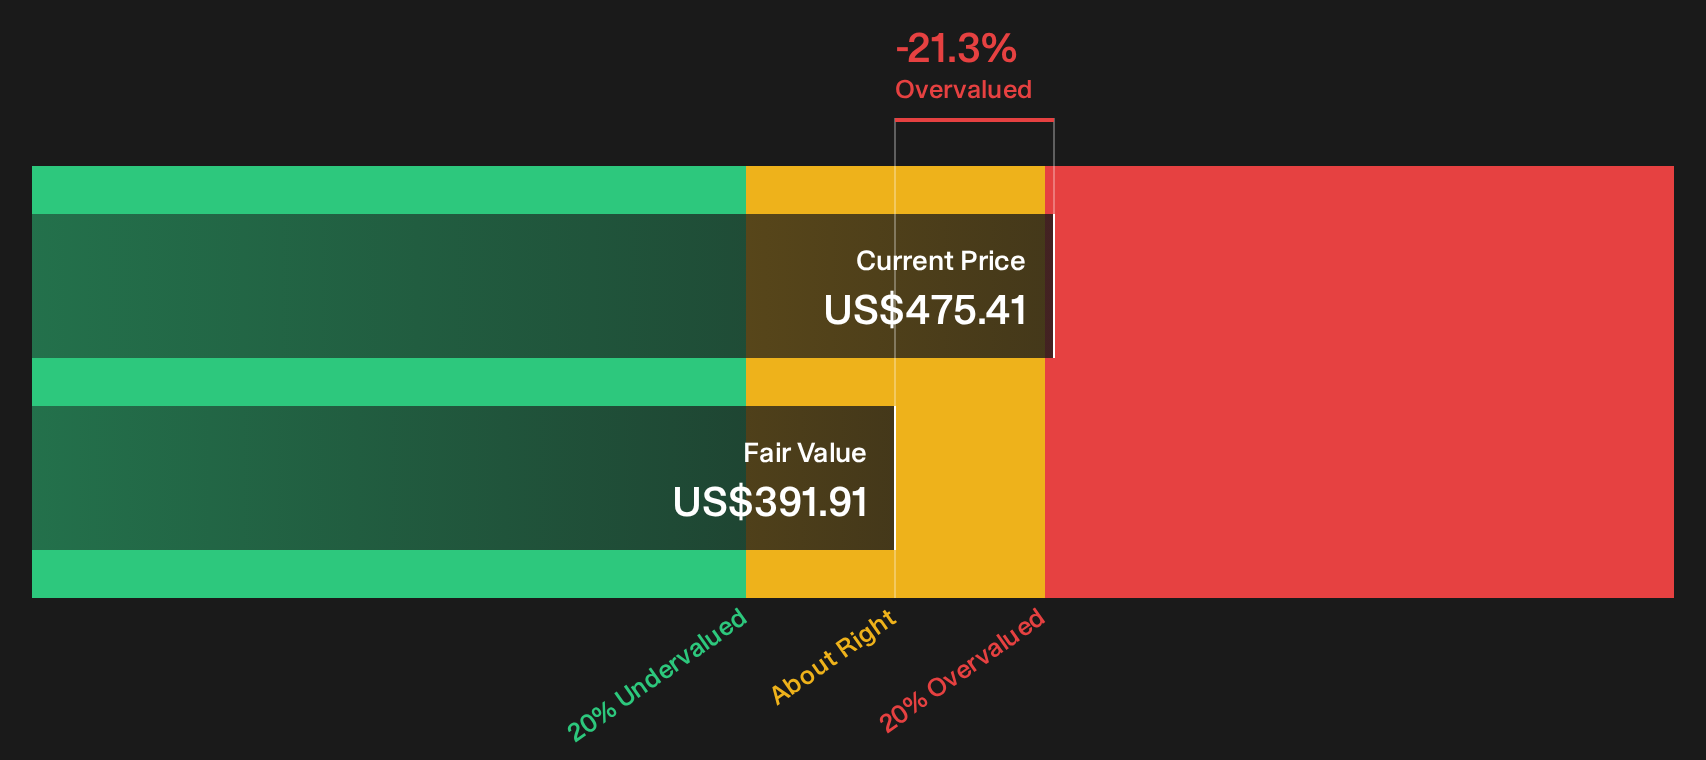
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hubbell for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Hubbell's value and risk profile can be confusing, so consider the information carefully and weigh the upside against the red flags yourself with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hubbell?
If Hubbell has sharpened your focus on quality, do not stop here. Broader opportunity sits across the market, and the Simply Wall Street Screener can help you surface it fast.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (25 results) to help keep financial risk in check.
- Hunt for potential mispricings by scanning the 29 high quality undervalued stocks to find companies that pair strong cash flows with disciplined capital structures.
- Lock in income-focused ideas by tracking the 8 dividend fortresses to identify higher yields alongside more robust underlying businesses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com