


LGI Homes (LGIH) has drawn fresh attention after a recent pullback, with the stock down about 19% over the past month and roughly 23% over the past 3 months.
Over a longer stretch, momentum for LGI Homes has been fading, with the 1-year total shareholder return down 5.9% and the 3-year total shareholder return down 54.3%, even though the share price is still up 7% year to date from a low base.
Compare LGI Homes' pullback with other builders under pressure and see which ones still show solid fundamentals in our curated list of solid balance sheet and fundamentals (25 results) for this corner of the housing market.
The question now is timing. After LGI Homes fell hard yet still sits above its early year levels, do you lean into the current reset, or wait for the valuation work to flag a clearer entry point?
Most Popular Narrative: 52% Undervalued
LGI Homes closed at $44.61, while the most followed valuation framework still points to a fair value anchor of $93 using an 11.6% discount rate. That gap rests on a view that the lot pipeline, land economics and community growth can translate into stronger earnings power than the recent share price implies.
The main thing that has to go right is that LGI Homes maintains margin resilience through its self-developed land, owned lot base and controlled construction costs, despite pressure on entry-level buyers and potential cost inflation.
The current narrative that LGI Homes is undervalued implies that the share price does not fully reflect its owned land position, backlog of contracted homes and guidance for homebuilding gross margins and community growth.
See why 7 investors see LGI Homes as 52% undervalued.
Result: Fair Value of $93 (UNDERVALUED)
Still, the narrative on LGI Homes can break if affordability pressure keeps cancellations near 49.4% or if higher material costs erode its lot cost edge.
Find out about the key risks to this LGI Homes narrative.
Another View: LGI Homes Through The P/E Lens
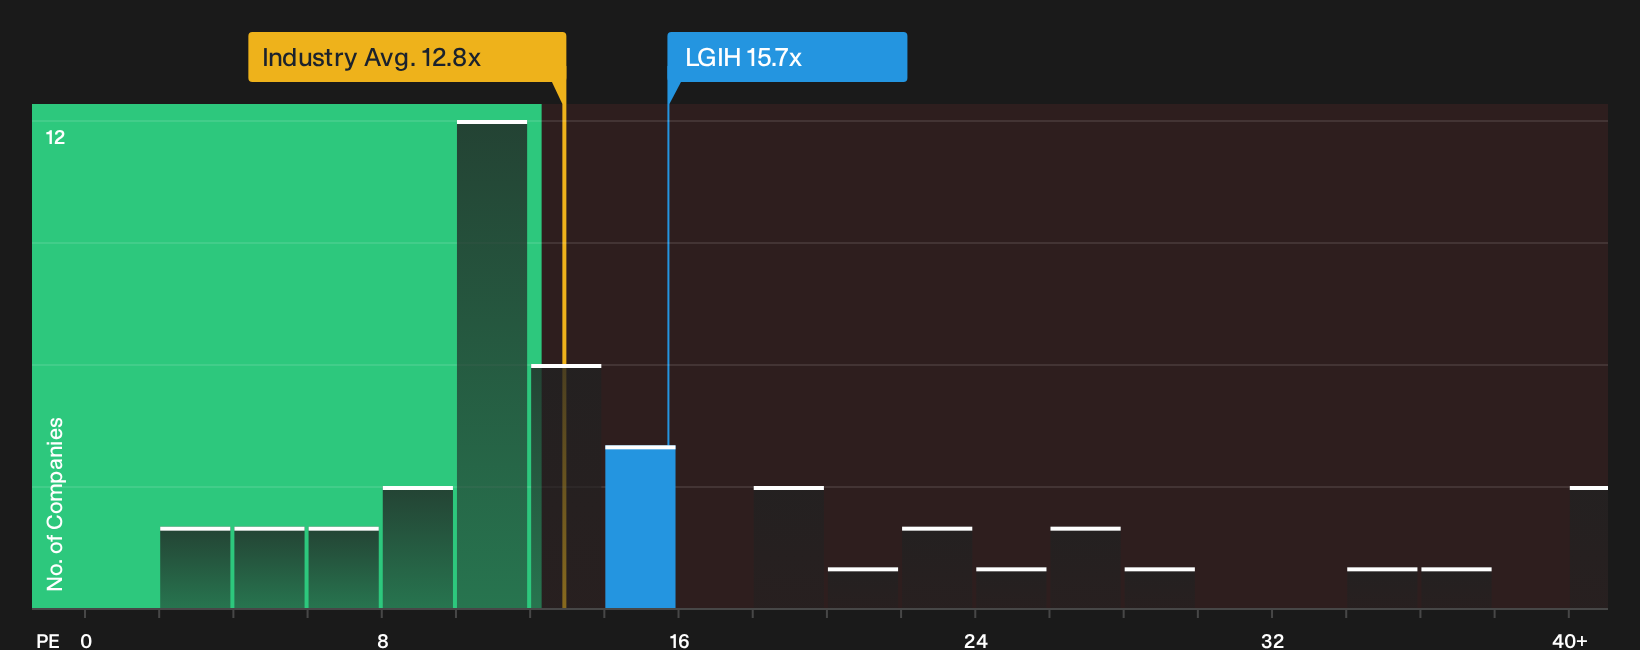
There is a very different picture when LGI Homes is viewed through its P/E ratio instead of the $93 fair value anchor. The shares trade on 15.7x earnings, below the US market at 18x and well under peers at 32.4x, while the fair ratio sits at 20.4x. That gap can look like a valuation cushion or a signal the market is pricing in real business risk. Which side do you think it reflects?
To pressure test that question against hard numbers rather than a single narrative, take a closer look at how this earnings multiple compares with the fair ratio and sector peers in our breakdown See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LGI Homes for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mixed tone around LGI Homes and its valuation reset. Act quickly, assess the data yourself, and weigh both the upside case and the risks in the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond LGI Homes?
If LGI Homes has sharpened your focus on value and risk, do not stop here. Broader opportunity sits in other corners of the market waiting for your review.
- Target resilient cash generators and tighten your risk profile with a focused shortlist of 31 resilient stocks with low risk scores that already clear strict balance sheet filters.
- Hunt for future leaders before attention crowds in by scanning a curated pool of 20 high quality undiscovered gems with solid underlying fundamentals.
- Lock in potential income streams by screening for 8 dividend fortresses that pair higher yields with an emphasis on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com