


Mitsubishi Motors (TSE:7211) has been drawing investor attention after recent share price moves, with the stock up about 0.9% on the latest trading day and mixed returns across recent periods.
Recent trading in Mitsubishi Motors reflects this tension between short swings and longer history, with the latest 1-day share price return of 0.91% in contrast to a year-to-date share price decline of 7.31% and a 1-year total shareholder return down 11.6%.
Scan how Mitsubishi Motors stacks up against peers by reviewing a curated set of 14 high quality undervalued stocks that combine share price pressure with stronger fundamentals.
The share price has nudged higher while longer term returns remain weak, which puts Mitsubishi Motors in an awkward middle ground. Is most of the easy upside already gone, or is the real rerating still ahead as valuation comes into focus?
Most Popular Narrative: 6% Undervalued
Mitsubishi Motors last closed at ¥345.1 against a widely followed fair value estimate of about ¥368.7, which frames the recent price drift as a modest discount rather than a runaway move.
Strategic focus on hybrid and plug in hybrid vehicle rollouts, especially in the ASEAN and Japanese markets, positions Mitsubishi to capitalize on consumer shifts to cleaner vehicles and anticipated regulatory tightening, likely boosting top line revenue and supporting higher market share. Introduction of globally strategic models, such as the new midsized SUV Destinator and hybrid variants of the XForce, is targeting both mature and growth markets, setting the stage for incremental volume increases and improvements in sales mix, which can drive operating margin recovery.
See why 1 investors see Mitsubishi Motors as 6% undervalued.
This widely followed narrative applies an 11.08% discount rate to those future cash flows and arrives at a fair value of roughly ¥368.7, which is about 6% above the current share price and broadly in line with the analyst consensus target near ¥369. The result reflects expectations for moderate revenue expansion alongside a profit margin assumption of about 1.9%, as well as a future P/E level that is lower than both Mitsubishi Motors' current multiple and the wider JP auto industry benchmark cited in the narrative.
For readers comparing that fair value to shorter term pricing moves, it is worth noting that the stock is trading around 23.4% below one separate future cash flow estimate of ¥450.73 in the Simply Wall St DCF workup, which sketches a wider valuation gap than the narrative based price target. As always, those are model driven outputs that rest on explicit assumptions about revenue growth, profitability and discount rates, so any change in those inputs can shift the implied range quite meaningfully.
Result: Fair Value of ¥368.67 (UNDERVALUED)
Still, Mitsubishi Motors faces pressure from rising competition that could squeeze margins, and higher R&D spending that might weigh on earnings if new models underperform expectations.
Find out about the key risks to this Mitsubishi Motors narrative.
Another View On Mitsubishi Motors Valuation
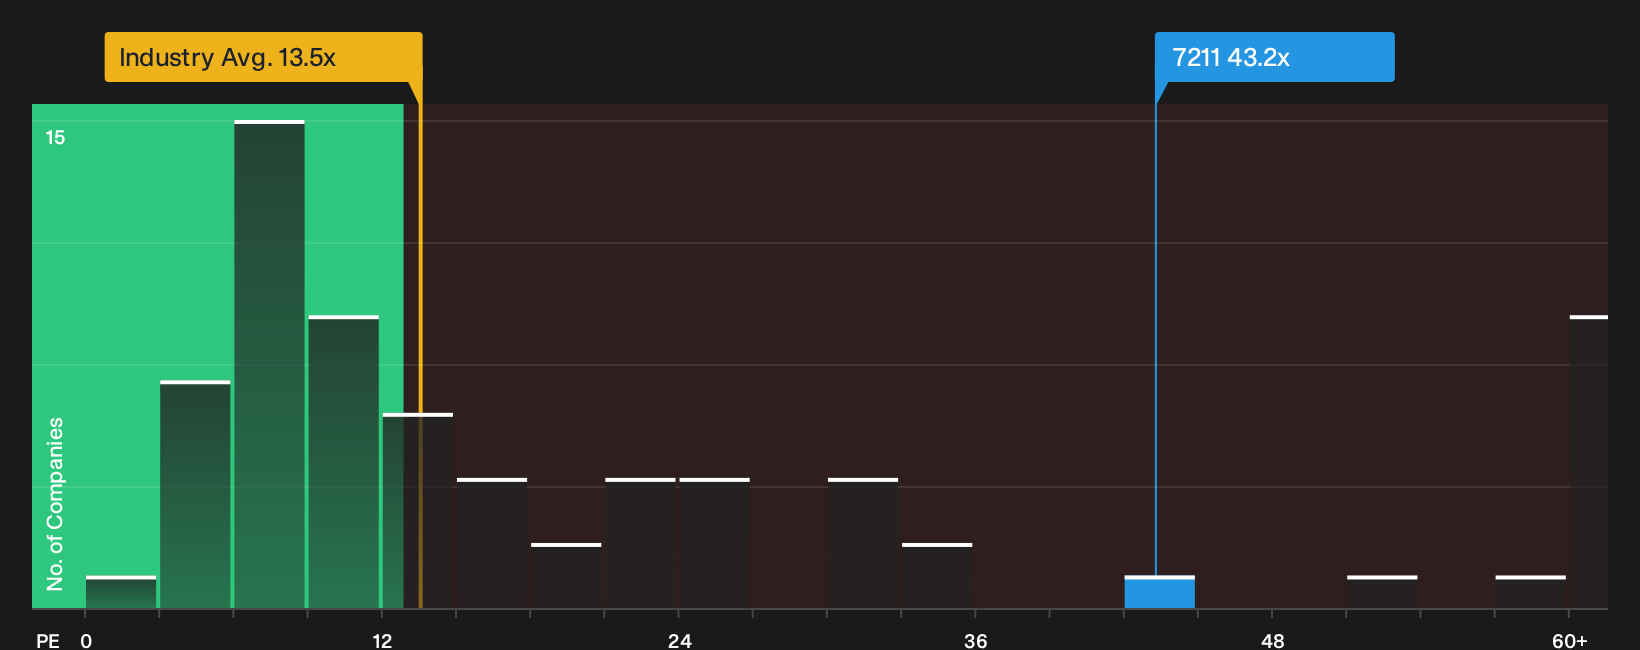
On the flip side of the fair value narrative, Mitsubishi Motors screens as expensive on simple P/E math. The shares trade around 43.2x earnings, compared with an Asian auto sector average of 13.5x, a peer group near 12.8x, and a fair ratio estimate of 23.7x that the market could gravitate toward over time.
If sentiment shifts back toward those lower multiples, that gap could mean valuation risk rather than upside, especially if earnings progress does not keep pace with expectations. Which lens do you trust more when you weigh Mitsubishi Motors today, the discounted cash flow story or the earnings multiple signal?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Mitsubishi Motors can feel confusing, so move quickly from reading to testing the numbers yourself and decide where you land on the risk reward trade off. To frame that decision with both the caution flags and the upside arguments laid out side by side, start with these 2 key rewards and 3 important warning signs.
Looking for more Mitsubishi Motors style investment ideas?
If Mitsubishi Motors has sharpened your interest, do not stop here. Broaden your watchlist with fresh ideas sourced from data driven screeners built to surface clear stories.
- Target dependable cash generators by scanning a list of solid balance sheet and fundamentals (23 results), which filters for resilient finances and sturdier fundamentals.
- Hunt for mispriced opportunities through a curated 75 high quality undiscovered gems, which highlights strong underlying metrics the wider market may be overlooking.
- Prioritize smoother portfolio swings by focusing on a 22 resilient stocks with low risk scores, tailored to companies with more stable risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com