


Analyst Rating Upgrade Puts VeriSign in Focus
A fresh rating upgrade for VeriSign (VRSN) to a Zacks Rank #2, driven by higher earnings estimates, has pulled the internet infrastructure provider back onto investor watchlists this month.
Recent trading tells a story of building momentum for VeriSign, with the share price at US$294.22 and a 90 day share price return of 8.98%. The 1 year total shareholder return of 11.20% and 5 year total shareholder return of 42.67% point to steady compounding alongside this latest upgrade-driven interest.
Compare VeriSign’s upgrade to other potential breakouts by reviewing the hand picked list in our 29 high quality undervalued stocks.
After an 8.98% gain over 90 days and a fresh upgrade, VeriSign is no longer flying under the radar. Is this a sensible entry point now, or does patience offer better value?
Most Popular Narrative: 9% Undervalued
The most followed narrative on VeriSign pegs fair value at $324.40, above the last close of $294.22. This frames the recent rating upgrade against a modest implied discount that investors are now dissecting closely.
The announced wholesale price increases for .com in November 2026 and .net in March 2027, together estimated to add more than US$120 million of annual revenue, are expected to feed directly into operating income and earnings given VeriSign's capital light cost structure.
See why 32 investors see VeriSign as 9% undervalued.
Result: Fair Value of $324.40 (UNDERVALUED)
Still, this VeriSign narrative can be knocked off course if .com and .net contract renewals tighten or if recent domain registration momentum loses steam.
Find out about the key risks to this VeriSign narrative.
Another View On VeriSign’s Valuation
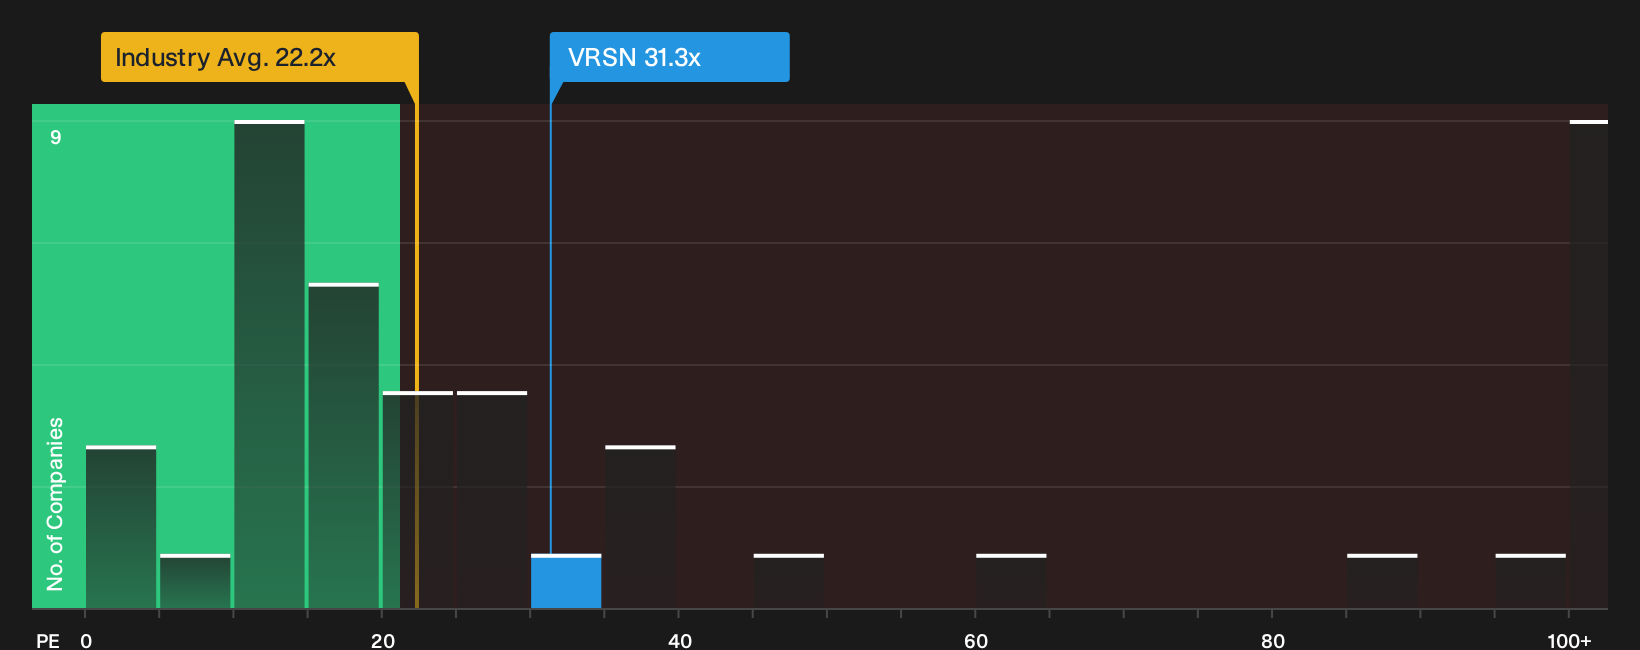
That 9% perceived discount to fair value leans heavily on earnings forecasts. A different lens uses the current P/E of 31.3x versus the US IT industry at 22.2x and an estimated fair ratio of 25.7x. This comparison points to richer pricing and less margin for error if growth expectations disappoint.
For a closer look at how this earnings multiple stacks up against both peers and that fair ratio, the valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown. can help you judge whether paying up for VeriSign still feels comfortable.
Next Steps
Mixed signals or a clear tilt toward opportunity? Only you can weigh VeriSign's risks against its potential rewards. Act while the details are fresh and review the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond VeriSign?
If VeriSign has sharpened your focus, use that momentum. Fresh ideas often come from scanning outside your comfort zone, not circling the same tickers.
- Target potential mispricings by reviewing a curated 29 high quality undervalued stocks that filters for quality businesses trading below their estimated worth.
- Strengthen your downside protection by scanning a list of solid balance sheet and fundamentals (25 results) that can help you focus on financially resilient companies.
- Hunt for tomorrow's potential standouts with a 20 high quality undiscovered gems that spotlights under-followed opportunities with strong fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com