


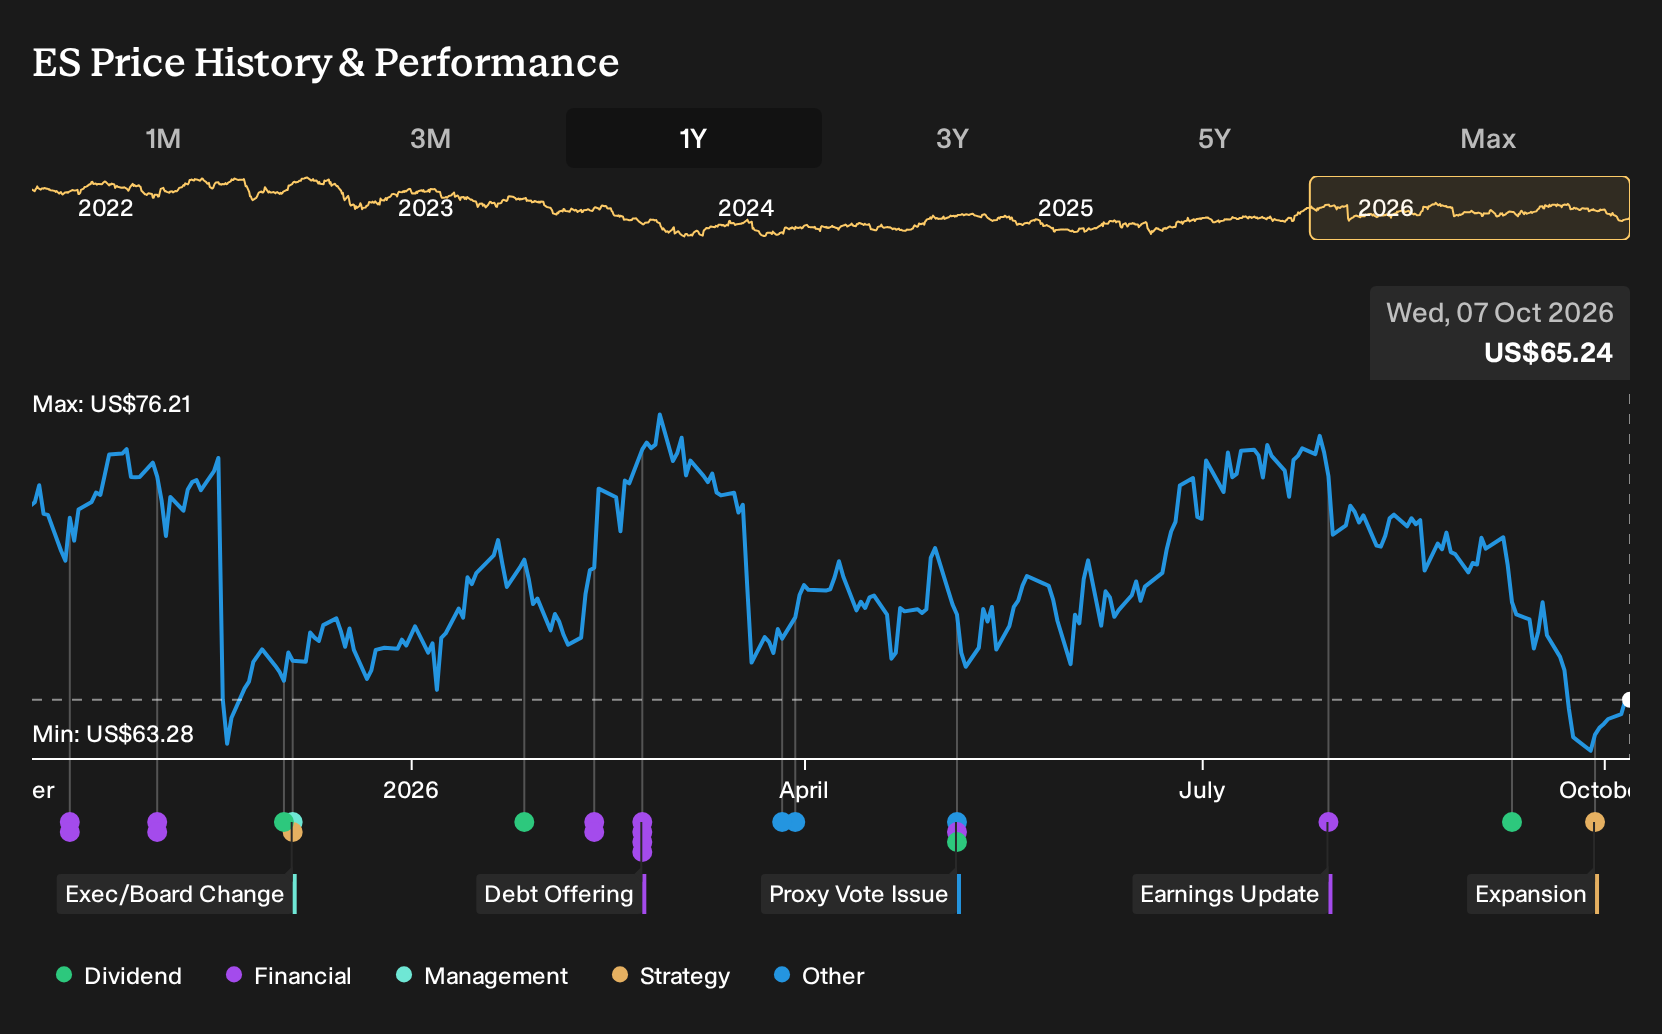
- In late September 2026, the U.S. Department of Energy selected Eversource Energy and Dartmouth Engineering for the DREAM initiative. This project plans to use dynamic line rating technology and related grid tools across about 4,000 miles of transmission lines and could receive up to US$47.7 million in funding after award negotiations.
- The project gives Eversource Energy a large scale test bed for grid enhancing technology. It directly links reliability, real time system visibility and customer affordability to its core regulated transmission operations.
- We will now look at how Eversource Energy's investment narrative could be shaped by the large scale dynamic line rating rollout.
Scan the grid upgrade theme beyond Eversource Energy by reviewing the hand picked 43 power grid technology and infrastructure stocks that could benefit as transmission capacity projects and reliability investments scale up across the sector.
Eversource Energy Investment Narrative Recap
Eversource Energy appeals to investors who want a regulated utility focused on grid reliability, capital investment and fairly steady earnings rather than rapid expansion. The big belief is that regulators will keep supporting cost recovery on its planned US$26.5b capital program, even as customer affordability pressure remains intense. The DREAM project fits cleanly into that grid modernization story.
In the near term, the key swing factor still appears to be regulatory outcomes, especially around CL&P rate cases and cost recovery for past storms. DREAM funding itself does not overhaul the risk profile. The bigger watchpoint remains earnings pressure from the lower allowed transmission return on equity and any fresh charges on large projects.
The DREAM initiative connects to Eversource Energy's broader push to grow its regulated rate base through transmission and distribution work that supports rising electrification and new regional generation. If the award negotiations conclude successfully, it could give the utility another tool to use existing lines more efficiently while staying within its regulated framework.
There is no fresh disclosure yet on how DREAM might interact with the company’s US$26.5b capital plan, storm securitizations or the shift toward a pure play regulated electric and gas utility. For now, investors are mainly weighing how this potential US$47.7m of DOE support fits alongside existing risks around interest coverage, dividend funding and ongoing regulatory scrutiny of bill impacts.
Eversource Energy's current analyst narrative points to about US$15.5b in revenue and US$2.1b in earnings by 2029, built on an assumed 3.5% yearly top line expansion and a shift from US$1.4b of earnings today to that higher level. This would mean an earnings increase of roughly US$700m over the period.
Uncover how Eversource Energy's fair value indicates a 13% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
One alternate view on Eversource Energy focuses less on projects like DREAM and more on pressure from tighter allowed returns. The most cautious analysts were working off about US$14.8b of 2029 revenue and a US$56.68 fair value target before this news, which is a far more pessimistic setup. Use it as a reference point while you explore how the new DOE backed project might shift these assumptions.
Explore 3 other Eversource Energy fair value estimates, including one that suggests as much as 24% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Eversource Energy research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Eversource Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Eversource Energy's overall financial health at a glance.
Looking For More Ideas Beyond Eversource Energy?
If Eversource Energy is only one piece of the watchlist you are building, it can help to scan for other companies that line up with your risk tolerance, income needs and return expectations using the Simply Wall St Screener.
- If you want potential value combined with quality fundamentals, start with a group of 29 high quality undervalued stocks that already screen well on both earnings strength and balance sheet support.
- If capital preservation is higher on your list than chasing every rally, consider a basket of 31 resilient stocks with low risk scores that score well on financial resilience and volatility filters.
- If you are hunting for tomorrow's potential compounders before they hit the spotlight, scan through 20 high quality undiscovered gems that pair solid metrics with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com