


Itoham Yonekyu Holdings (TSE:2296) has come back into focus after recent share price weakness, with the stock down about 5% over the past month and 15% year to date.
That recent weakness comes on top of a softer trend. Itoham Yonekyu Holdings has posted a year-to-date share price decline of 15.05%. The 1-year total shareholder return is down 9.85% but still sits on a 67.48% gain over five years, suggesting momentum has faded in the short term even though long-term holders remain ahead overall.
Compare Itoham Yonekyu Holdings' recent pullback with other hand picked food producers by reviewing the list of solid balance sheet and fundamentals (23 results) for potential alternatives in the same space.
After a pullback of this size in Itoham Yonekyu Holdings, some investors will be tempted to step in, while others may prefer to sit tight for a deeper discount. How does the current valuation stack up?
Price-to-Earnings of 13.7x: Is it justified?
Itoham Yonekyu Holdings currently trades on a P/E of 13.7x, which sits below both its peer group and the broader Japanese food sector based on the latest checks. For investors watching a stock that has pulled back in price, that kind of discount naturally raises the question of whether the market is being too cautious about its earnings profile.
The P/E ratio compares the current share price to earnings per share. For a mature food producer like Itoham Yonekyu Holdings, it is a simple way to express what buyers are willing to pay for each unit of profit. It is widely used for established, cash generating businesses where earnings are a key driver of value.
Here the current P/E of 13.7x is described as good value relative to both the JP Food industry average of 16.4x and a peer average of 21.4x. The ratio is also below an estimated fair P/E of 15.9x, which implies the market is pricing the stock more cautiously than the level that regression based fair value work suggests it could move toward over time.
Explore the SWS fair ratio for Itoham Yonekyu Holdings.
Result: Price-to-Earnings of 13.7x (UNDERVALUED)
Uncover how None investors see Itoham Yonekyu Holdings as None% None
Still, the Itoham Yonekyu Holdings story can change quickly if meat input costs spike, or if demand for higher margin processed products softens.
Find out about the key risks to this Itoham Yonekyu Holdings narrative.
Another view on Itoham Yonekyu Holdings’ value
The P/E work paints Itoham Yonekyu Holdings as modestly cheap. The SWS DCF model is more restrained. At ¥4,825, the shares sit only about 2% below an estimated future cash flow value of roughly ¥4,925, which points to a stock that screens only mildly undervalued. Is that small gap enough to compensate you for the business and governance risks on show?
Look into how the SWS DCF model arrives at its fair value.
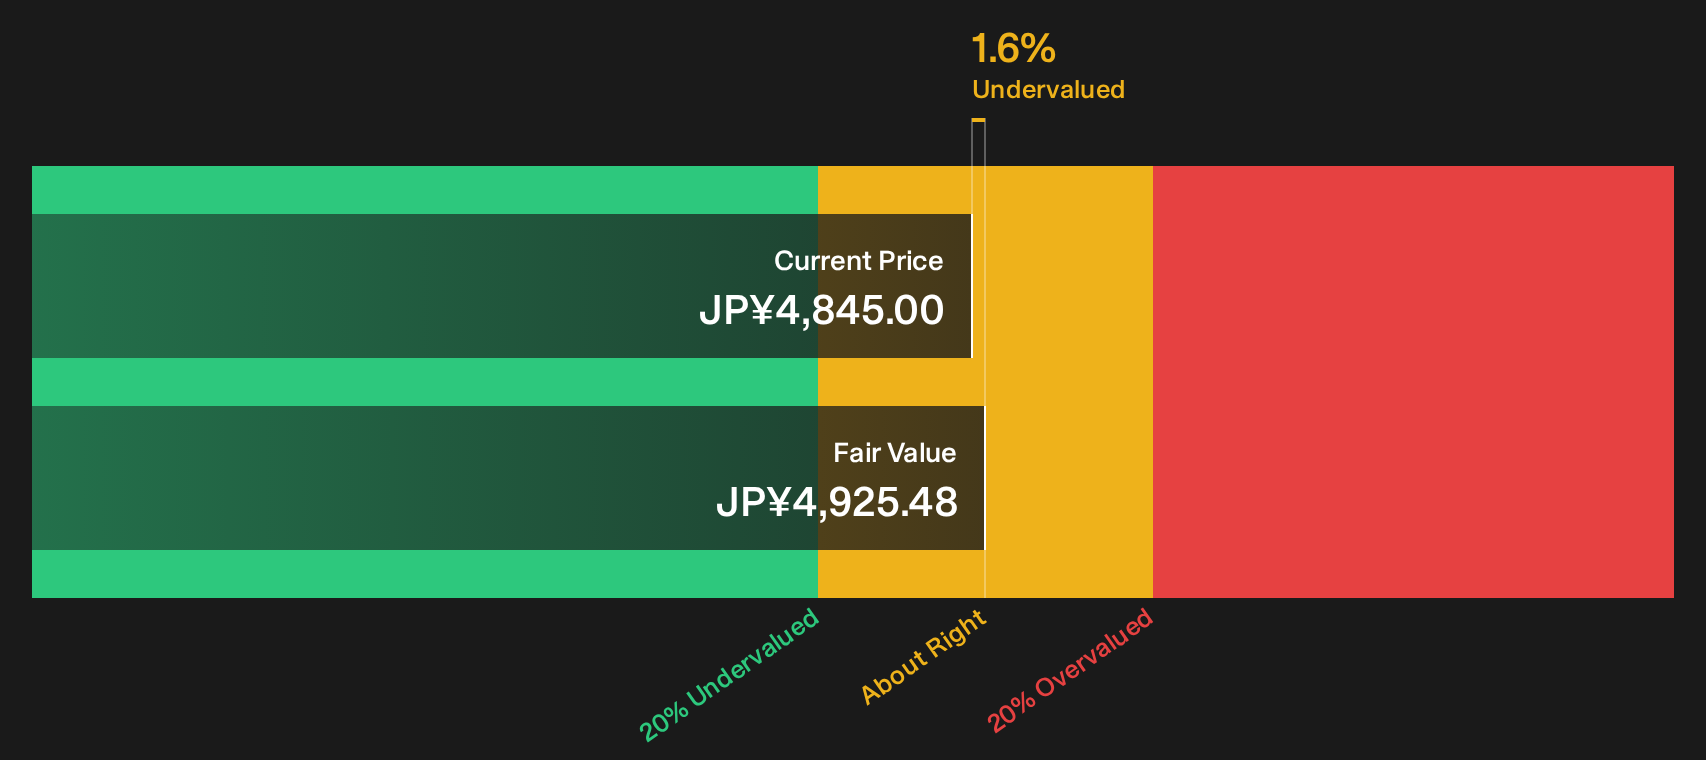
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Itoham Yonekyu Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Itoham Yonekyu Holdings is clearly mixed, with both pressure points and bright spots in view, so you should move quickly and weigh the evidence yourself while it is fresh. To understand the balance of issues and potential upsides in a single place, review the 3 key rewards and 1 important warning sign.
Looking for more Itoham Yonekyu investment ideas?
If Itoham Yonekyu Holdings has sharpened your focus, do not stop here. Broader idea generation can help you compare risks, quality and income potential.
- Target quality at a discount by scanning companies that combine strong fundamentals with attractive valuations through the 14 high quality undervalued stocks.
- Prioritise resilience by reviewing a 22 resilient stocks with low risk scores that highlights businesses with more robust risk profiles.
- Hunt for overlooked potential by checking a 75 high quality undiscovered gems that may not yet be widely followed by the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com